September 23, 2026
Bonus Content: Kalshi Filed to Add Margin to Prediction Markets
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader,
When this man warned of the 2008 crisis two years before it ever happened…
The CIA began circulating his warning among its senior staff.
And his full thesis was so in depth that it appeared in the CIA journal “Studies in Intelligence”.
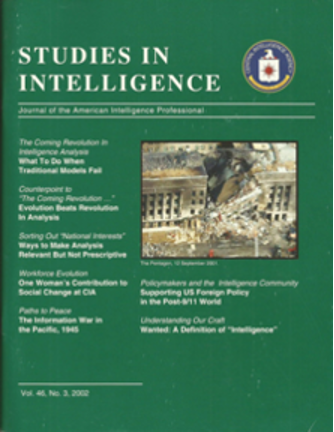
That information remains classified to this day.
Even still, in 2016 when he went on national television to predict the election of Donald Trump…
Most people tried to dismiss him saying that “Hillary is ahead in every poll”…
But events shaped up just the way he said.
Then in 2019, a full 4 months before the coronavirus hit..
He said that a global pandemic could be the cause of the next financial crisis…and that a crisis of this proportion would happen with “near 100% certainty” within the next few years…
Most people thought he finally lost it.
But we all know what happened next…the world was nearly brought to its knees by this “unforeseen” event.
Now this former advisor to the CIA and the Pentagon is issuing a shocking new warning.
One that has to do with the brewing bubble in AI – and an event set to take place just DAYS from now.
If you have money in the markets, or wealth to protect, then you need to heed his warning.
Because once this crisis hits…it will already be too late.
>>> Click Here to See His New Warning <<<
Regards,
Matt Insley
Publisher, Paradigm Press
Kalshi Filed to Add Margin to Prediction Markets
In today’s U.S. regulated event contract markets, trading is generally run on a fully collateralized basis, meaning participants post funds up front that cover the maximum potential loss before an order is accepted. Kalshi Klear, the company’s clearinghouse, filed Tuesday, September 22, 2026 to change that defining feature for certain participants by seeking permission to introduce margin on some event contracts.
Kalshi filed with the Commodity Futures Trading Commission seeking approval to offer leverage on its event contracts, a move the company says is aimed at drawing institutional traders to its prediction markets. The filing was submitted under CFTC Regulation 40.5(a) as a voluntary submission for Commission review and approval, following months of informal discussions with the regulator.
Margin trading allows a trader to borrow funds to take larger positions than their posted cash alone would support. In traditional derivatives markets, margining is a standard feature across major exchanges, including CME Group and ICE.
Kalshi’s rollout, if approved, would not be open to retail traders. Access to leverage would be restricted to qualified participants with direct clearing relationships with Kalshi Klear and specified capital thresholds. The company said it would not offer margin on sports event contracts, or on its culture and “mention” markets. Contracts tied to economic data, financial developments, politics, and commercial activity could qualify.
The risk framework is built around a key mechanical feature. Kalshi Klear built the proposal around what it calls “risk-based, side-specific margining,” evaluating YES and NO positions on a contract separately rather than treating them as mirror images. The filing says the framework targets at least 99 percent per-side confidence that losses on a position will not exceed the margin posted against it, a threshold the company describes as more stringent than baseline regulatory standards in other cleared derivatives contexts. Even for qualified participants, the leverage would shrink as a contract nears its outcome, with requirements tightening as the risk of a sudden yes-or-no resolution rises.
If approved, changes could take effect after a 45-day review, beginning no earlier than the first business day after the review period ends. That timeline matters for how to read the attached names.
Robinhood routes some event contract activity through third-party venues including KalshiEX, making HOOD a downstream beneficiary if institutional liquidity deepens on the venues it connects to. Robinhood CEO Vlad Tenev recently told CNBC’s Jim Cramer he believes crypto-linked contracts will ultimately become the dominant category for event contracts, rather than sports. For HOOD shareholders, the Kalshi filing is a reminder that one piece of the prediction market infrastructure Robinhood relies on is pushing to expand its addressable pool of capital.
The competitive implications extend further. Polymarket, Kalshi’s most prominent competitor by brand in U.S. prediction markets, has been exploring U.S. regulatory pathways. DraftKings, meanwhile, launched its proprietary exchange DKeX on June 26, 2026, having already forecast a 2026 prediction market investment of $200 million to $300 million. A CFTC-approved margin regime at Kalshi would raise the competitive bar for platforms still operating under full-collateral trading rules.
What Traders Should Watch
- CFTC timeline: Kalshi is asking the Commission to approve changes under the Regulation 40.5 review process before any margin offering can go live. The 45-day review window is the first gate.
- HOOD: Watch for any commentary from Robinhood on how an institutional push at connected venues affects contract flow through its hub.
- CME and ICE: If the CFTC blesses a margin framework for event contracts, incumbents face a more structurally competitive prediction market sector. Neither has a formal event contract product today.
- DKNG: DraftKings built its exchange knowing full collateral was the industry standard. A change in that standard shifts the competitive landscape it is pricing into its 2026 investment.