October 7, 2026
Enterprise software consolidation is accelerating in 2026, and the companies selling point solutions are the ones paying the price.
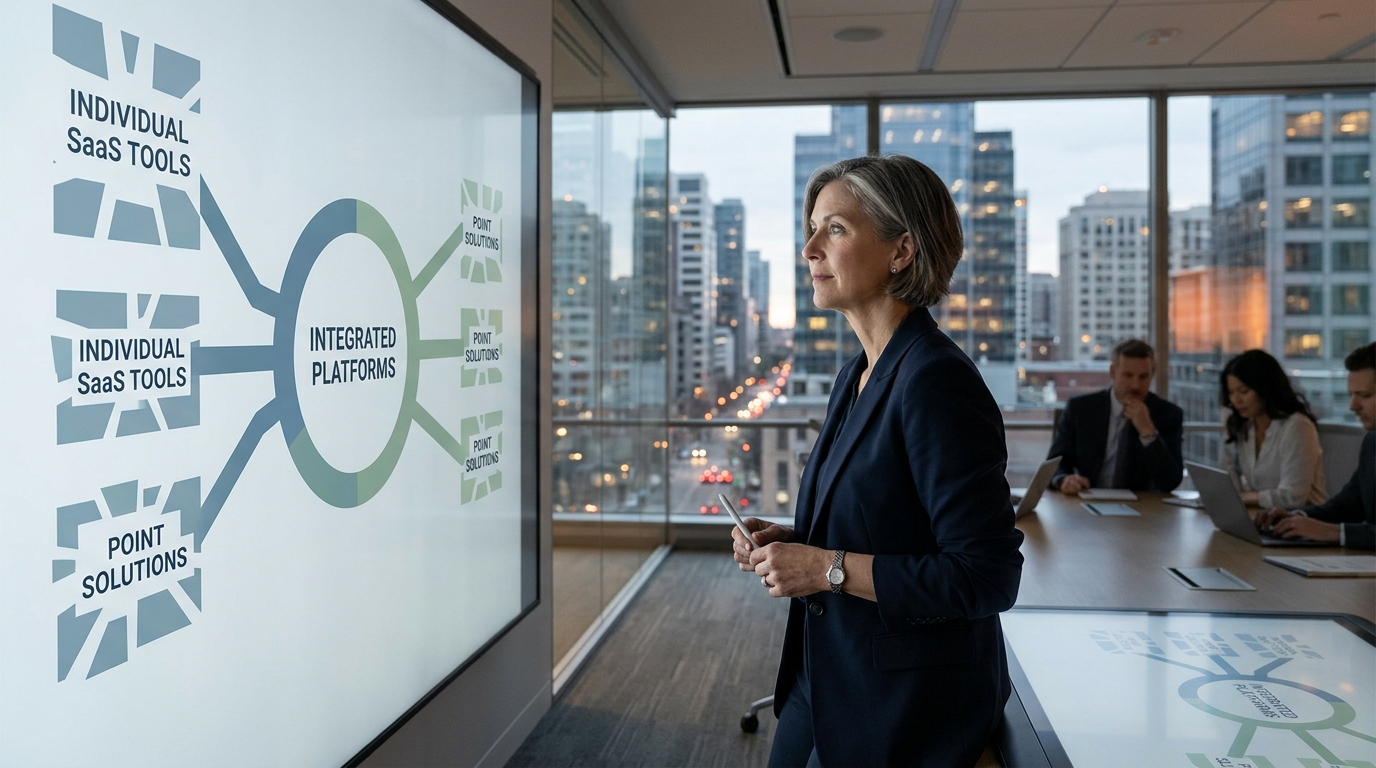
The logic was always inevitable. When the average large enterprise runs hundreds of SaaS tools inside a total portfolio of more than 2,000 applications, someone eventually does the math. That reckoning is now happening at scale, and the beneficiaries are the mega-cap platforms already sitting at the center of the corporate tech stack.
Your Download Link Will Expire
If you still haven’t downloaded my free “Safe Trade Options Formula” guide…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy on your computer.
Make sense?
The numbers are hard to argue with. Analysts and SaaS-management firms routinely estimate that roughly a quarter of SaaS spend is wasted through unused entitlements and overlapping tools, a figure Gartner has echoed in its own work. Consolidated stacks, meanwhile, can cut costs and shorten implementation timelines, according to recent analyst and vendor-commissioned studies. For a CFO staring at a $280 million annual software bill, those figures are a mandate, not a suggestion.
The M&A activity reflects that pressure with unusual clarity. The first half of 2026 alone produced IBM’s $11 billion acquisition of Confluent, ServiceNow’s $7.75 billion purchase of Armis, and Google’s $32 billion bet on Wiz, one of the largest cybersecurity acquisitions on record. These are not purely financial plays. They are platform-extension moves, each one designed to eliminate a category of point-solution spending inside the enterprise buyer’s existing contract relationship.
Most People React After the Change. That’s Too Late.
By the time a new economic direction is obvious, the window to position early has usually closed. Reagan Gold Group’s free 2026 Wealth Protection Guide explains how economic shifts reach retirement accounts, why some investors are diversifying beyond paper assets now, and what a Gold IRA actually involves.
The strategic logic runs in both directions. On the supply side, OpenAI has been among the most active acquirers of technology and SaaS companies in 2026, with deal trackers showing roughly 10 announced acquisitions through early October, spanning vertical AI, developer tooling, and enterprise workflow capability. On the demand side, one widely circulated March 2026 CIO survey found 54% of CIOs are actively consolidating vendors, while only 3% expect AI to lead to more vendors. The irony is sharp: the AI wave that initially multiplied point-solution purchases is now driving the consolidation that eliminates them.
The pressure on standalone SaaS businesses is real. Public SaaS multiples have compressed dramatically from 2021 peaks, with Freshworks, for example, falling from roughly a $10 billion-plus market cap around its 2021 IPO window to roughly $3 billion to $4 billion in early October 2026. That valuation reset is precisely what makes the acquisition math work for well-capitalized buyers: targets are cheaper, integration synergies are real, and the enterprise customer already wants fewer vendor relationships to manage.
“Frontier AI” is a point of no return when AI surpasses human intelligence and gains free will.
Elon Musk warns this moment could hit by the end of 2026. According to 60-year Wall Street legend, Marc Chaikin, Frontier AI could soon become the only thing that determines which companies make money and which grind to a halt. That’s why he’s giving away a list of stocks to buy and sell absolutely FREE to help you position your money for a world driven by Frontier AI technology.
For traders, the cleaner read is not which niche SaaS names get acquired next. It is which platforms are positioned to absorb the most spending as enterprises prune their stacks. Microsoft has said Microsoft 365 has over 450 million paid commercial seats, and every category it expands into with Copilot is a renewal conversation a competitor loses. ServiceNow, Salesforce, and Google Workspace sit in similar positions: deeply embedded, expanding scope, and collecting the consolidation dividend that vendors selling a single function cannot match.
The best-of-breed era is not ending overnight. But the purchasing committee is smaller now, the budget scrutiny is higher, and the vendor that already has the enterprise’s data is winning the next contract without a competitive bake-off. That structural shift is where the durable trade lives.