October 8, 2026
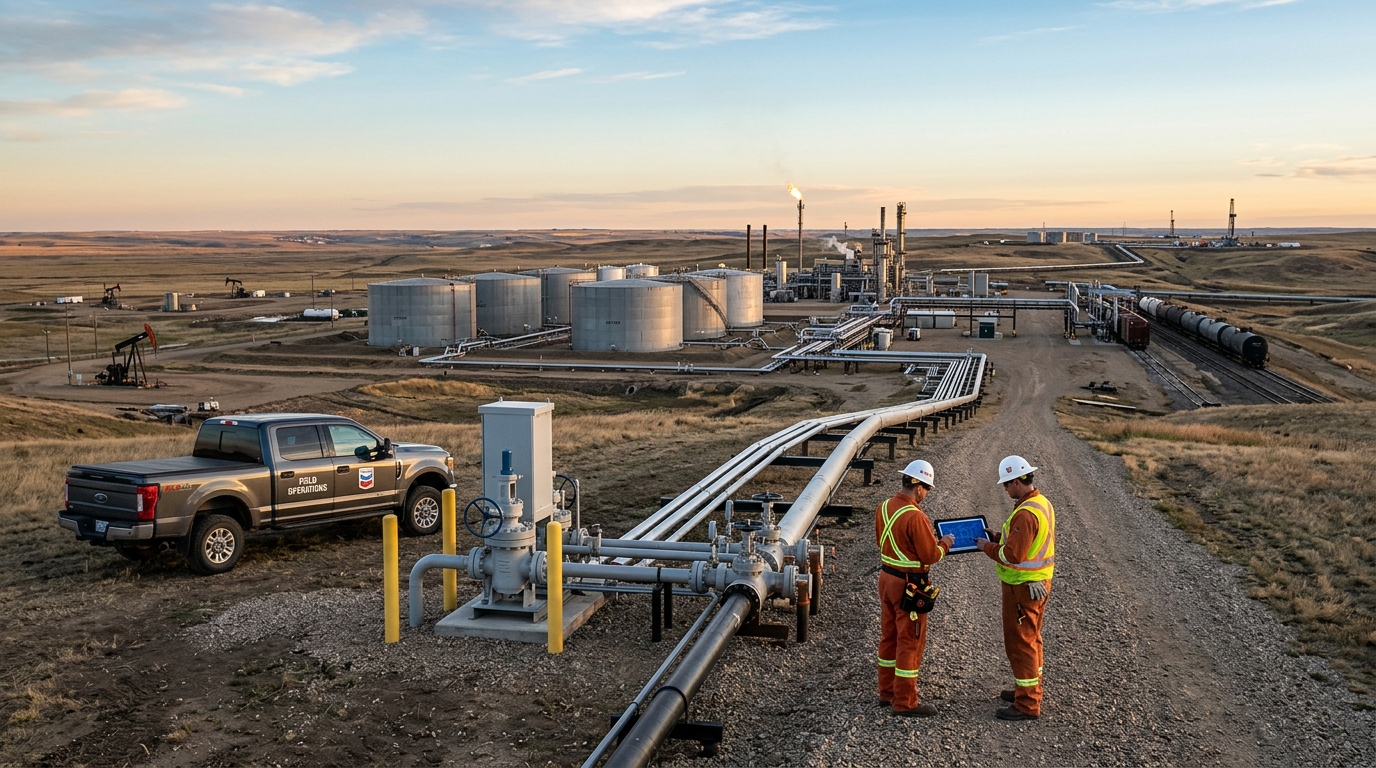
Bonus Content: Chevron Takes a $3-4 Billion Loss to Cut Its Bakken Costs in Half
Wall Street loves a new story.
But sometimes the more interesting opportunity is a company that has been waiting years for the market to catch up.
One little-known Nasdaq company has spent more than 25 years developing professional drone technology that is now a priority in Washington.
This is not a company trying to invent itself around D.C.’s latest push.
It was developing these technologies long before America’s current drone demand started.
That experience matters as the Pentagon looks for scale and Washington directs more attention toward domestic manufacturers.
Yet the company is still trading under $5… for now.
If America’s drone industry is entering a much bigger chapter, investors may want to know why this pioneer remains so overlooked.
Chevron Takes a $3-4 Billion Loss to Cut Its Bakken Costs in Half
Chevron made an unusual trade on October 6, 2026: it agreed to give back assets in exchange for a better bill. The company will transfer its ownership interests and general partner position in Hess Midstream, plus its DJ Basin crude oil midstream assets, to Hess Midstream. In return, CVX collects $200 million in cash and a renegotiated commercial framework that extends Bakken contracts through 2045. The accounting consequence is steep: Chevron expects to recognize a one-time after-tax loss of approximately $3 to $4 billion at closing, because the company cannot recognize future Bakken midstream cost savings as an asset.
The logic is straightforward even if the optics are not. The revised agreements are expected to reduce Chevron’s Bakken unit midstream costs by approximately 50%, enhancing future earnings and return on capital employed. Pair that with a balance sheet benefit: Chevron expects to fully deconsolidate Hess Midstream, including approximately $3.7 billion of Hess Midstream’s debt. Removing that liability alone changes how CVX looks to investors assessing leverage.
Chevron inherited its Hess Midstream position through its acquisition of Hess Corp. The midstream stake came with the deal but was never a natural fit for an upstream-focused major. Exiting it is a clean-up move, not a distress sale. Chevron expects the transaction to be accretive to return on capital employed by 0.5% on an absolute basis and generate long-term future economic value through a lower cost structure and improved earnings.
Stocks in Focus
HESM is the name to track today. The buyer in this transaction is Hess Midstream LP itself. The publicly traded partnership is acquiring Chevron’s ownership interests and general partner position, giving it a path to operate as a fully independent company. That structural shift matters for how the unit is priced, and the market moved fast: HESM fell 14.63% on October 7, 2026, the first full trading day after the October 6 announcement. A drop of that size typically reflects two things: digestion of the ownership change and uncertainty about what revised tariff rates mean for distributable cash flow. The deal includes new long-term midstream contracts with Chevron in both the Bakken and DJ Basin, which should help support future volumes and cash flows. The pricing terms of those contracts will matter more than the ownership change itself.
For CVX, the $3-4 billion loss will be treated as a special item, so headline EPS takes the hit but the recurring earnings profile arguably improves. The deal is expected to close by year-end 2026, which means the loss lands in Q4 if the close happens in the fourth quarter. Worth noting: Chevron is expected to move from three to two drilling rigs in the Bakken in December 2026, signaling that cost reduction, not growth, is the current Bakken priority.
The Cheat Sheet
- Top Theme: Major integrated energy companies are trading asset ownership for contractual access, prioritizing cost structure over control.
- Stock to Watch: HESM. The 14%-plus decline prices in uncertainty; the question is whether revised tariff terms adequately offset the loss of CVX as a controlling sponsor.
- Sector to Watch: Midstream energy. When a supermajor restructures this aggressively, it signals where margin pressure is concentrated in the value chain.
- Biggest Risk: HESM contract pricing details. If the new tariff rates are materially lower than the old ones, distributable cash flow projections need to come down.
- Biggest Opportunity: CVX on weakness tied to the headline loss. The recurring cost benefit is real, the debt removal is real, and the $3-4 billion charge is non-cash in character.
- One Thing to Remember: The loss is the price of a cheaper future. Traders pricing CVX on the charge alone are reading the wrong line.