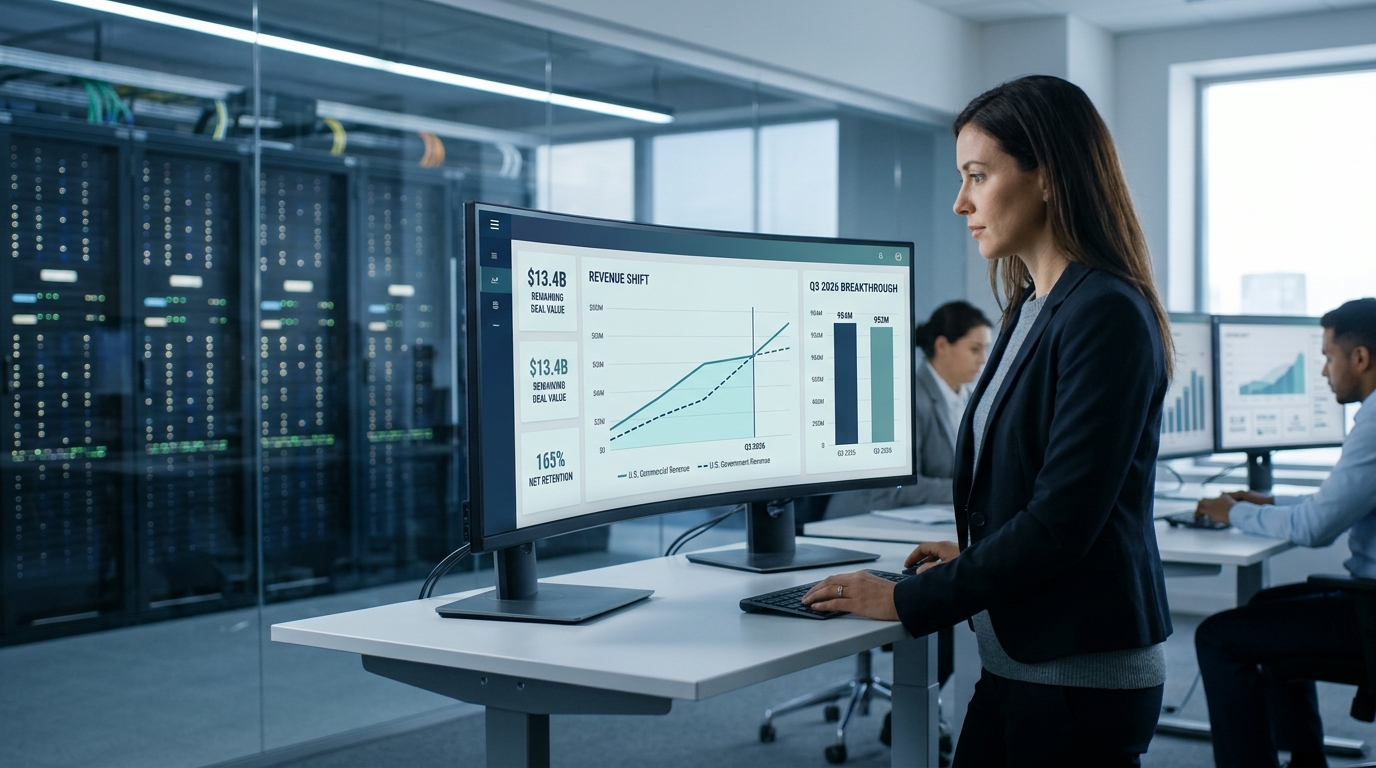
For the first time in Palantir’s history, enterprise software customers outspent the Pentagon. U.S. commercial revenue hit $984 million in Q3 2026, surpassing U.S. government revenue of $953 million as enterprise AI adoption accelerated. That crossover is not a rounding error. It is a structural shift in what this company actually is.
The numbers behind that shift are worth examining closely, because they tell a more complicated story than the headline growth rates suggest.
The Backlog Is the Business Case
Net dollar retention reached 165%, up 800 basis points from the prior quarter. Total remaining deal value hit $13.4 billion, up 55% year over year, while remaining performance obligations were $4.9 billion, up 88%. Those are not vanity metrics. Net dollar retention at 165% means existing customers are expanding their Palantir footprint far faster than any churn. The pipeline is not theoretical demand; it is contracted money.
The U.S. commercial customer count reached 686, up 29% year over year. Chief Revenue Officer Ryan Taylor noted that an industrial materials company converted a nearly $3 million pilot from Q2 into a $29 million annual contract value deal in Q3. Last quarter, a global athletic company converted a $1.6 million pilot that began in Q1 2026 into an approximately $21 million ACV deal. The pattern is consistent: AIP bootcamps pull companies in at low cost, and the expansion contracts are substantially larger.
Where the Concern Lives
The Q3 TCV figures introduced a complication that the market priced in quickly. U.S. commercial TCV fell from $2.132 billion in Q2 to $1.463 billion in Q3, a sequential decline of about 31%, with annual TCV growth dropping from 153% to 11%. Management’s explanation: CFO David Glazer said Palantir signed multiple eight-figure deals in Q3 that were shorter in duration than usual as customers rapidly adopted initial sovereign AI capabilities. Shorter contracts compress reported TCV without necessarily signaling weaker annual spending.
Shorter contract durations compressing reported backlog is not unique to Palantir. Dell’s $95 billion AI server backlog shows how enterprises are committing capital to AI infrastructure in ways that distort traditional contract metrics.
That defense is plausible. Remaining deal value still grew 79% year over year in the U.S. commercial segment. But the sequential TCV drop is real, and TCV and remaining deal value can include contract options that customers may never exercise. Traders watching PLTR need to separate contracted revenue from contracted optionality.
The Valuation Is the Trade
Palantir raised full-year 2026 revenue guidance to $8.530 billion to $8.534 billion, implying about 91% growth at the midpoint. U.S. commercial revenue guidance was lifted to in excess of $3.559 billion, representing at least 143% growth. The operating leverage is real: adjusted income from operations reached $1.427 billion in Q3, a 62% margin, with the Rule of 40 score hitting 158%.
The problem is what has already been priced. Palantir shareholders have been paying roughly 57 times sales recently, compared with about 3.6 times for the S&P 500. According to commentary aired by Charles Schwab’s George Tsilis, the primary concern for Palantir remains its valuation, with the company trading at roughly 124 times forward earnings compared to an average of 22 times for peers in application software.
Palantir shares have previously fallen much further than the broader market, dropping about 63% peak to low during the 2022 bear market when the S&P 500 fell about 25%. Its beta and volatility depend heavily on the lookback window and the data provider, but the practical point remains: this is a high-volatility stock. The growth is real. The question traders are actually answering when they buy PLTR is not whether AIP works. It is whether the execution over the next three years will be flawless enough to justify a multiple that already assumes it will be.