October 12, 2026
Bonus Content: TSMC’s Price Hike Is Squeezing Nvidia and AMD. Thursday Shows Who Pays Next.
Dear Reader,
The alarm bells are going off inside the world of AI.
Because a pair of specific metals that are critical to its success is running out rapidly.
Data centers, semiconductors and quantum computing all desperately need one of these critical minerals …
While the other is critical to solving the massive energy crisis that’s holding AI back.
In 2024, AI data centers used as much energy as New York and Chicago …
COMBINED.
This crisis is now facing an even scarier prospect.
Currently, China controls 90% of the production of the elements needed to keep AI rolling.
They could shut off our supply in an instant … immediately crippling our way of life.
Former Secretary of State Condoleezza Rice stated …
“We absolutely have to win this race so that a democracy wins the race for these frontier technologies, not an authoritarian state.”
Jamie Dimon echoed that sentiment, saying …
“It has become painfully clear that the United States has allowed itself to become too reliant on unreliable sources of critical minerals …”
That’s why the CEO of the country’s biggest bank is investing trillions of dollars into rebooting a decades-old government project called Project Phoenix.
Tapping Rice and Jeff Bezos, amongst others, to spearhead the effort.
Not only that …
He’s investing millions into two tiny companies that trade for under $10 a share.
The reason is simple.
They are the ONLY operations that can currently mass produce these precious metals.
My research says their value is going to explode as they take on a central role in Project Phoenix.
Now could be your last chance to get involved in the best opportunity in this sector in quite some time.
Click here to get all the important information right away.
Sincerely,
Sean Brodrick
Weiss Ratings
TSMC’s Price Hike Is Squeezing Nvidia and AMD. Thursday Shows Who Pays Next.
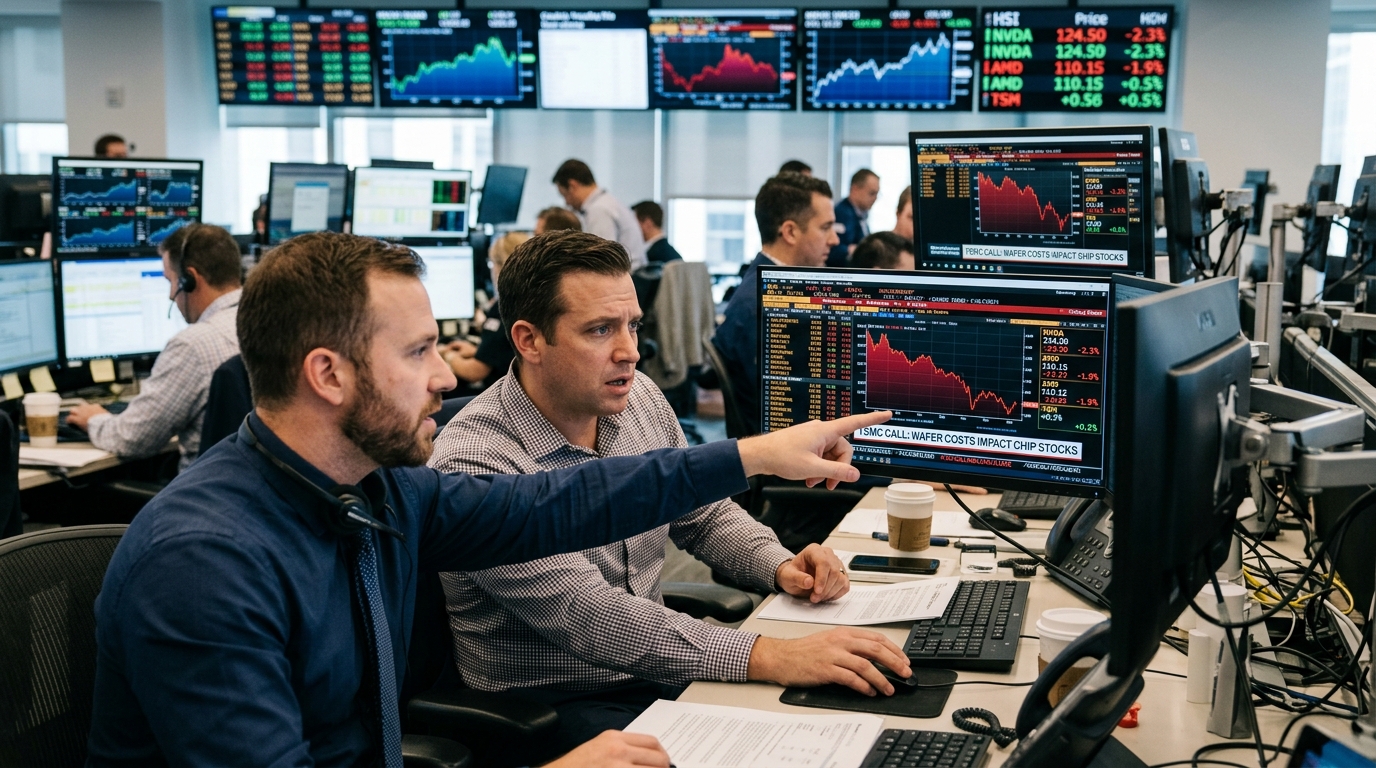
Thursday’s TSMC earnings call is about more than a sixth consecutive record profit. It is the first public forum where management faces questions about who absorbs the cost of the most aggressive foundry pricing campaign in two decades, and what that means for every chip stock in the AI complex.
Market Snapshot
TSMC reported record Q3 revenue of $46.7 billion on October 8, up 50% from a year earlier and above its own guidance, making Thursday’s full-earnings release largely a confirmation exercise. The company is expected to post its sixth straight quarter of record profit, with the LSEG SmartEstimate drawn from 16 analysts pointing to net profit rising roughly 65% to NT$746.3 billion. Gross margin consensus sits near the mid-66% range, against company guidance of 65% to 67%.
The Philadelphia Semiconductor Index plunged about 3.4% last Thursday, after a Financial Times report said OpenAI’s annualized revenue neared $50 billion, about $20 billion below the $70 billion figure that had been circulating. That gap knocked the AI demand story off its axis heading into this week’s print.
Stocks in Focus
TSM: UBS has raised its TSMC capital expenditure forecasts to $90 billion for 2027 and $105 billion for 2028. That figure lands on top of a 2026 range TSMC already lifted twice. When TSMC raised its 2026 capex guidance in July, it said the newest node would dilute second-half gross margin by 3 to 4 percentage points. Whether Thursday’s guidance update revises that margin headwind or expands it is the swing variable for the stock.
NVDA: TSMC plans base price increases of 5% to 10% and a 10% to 15% surcharge on excess high-performance computing orders starting in early 2027. Nvidia alone has locked down roughly 60% of the advanced packaging expansion for the 2026 and 2027 production years. That concentration insulates Nvidia’s supply position but concentrates its cost exposure. Nvidia’s gross margin reached 75.0% in its most recent quarter, up from 72.4% a year earlier, driven by improved Blackwell Ultra product mix. Whether that buffer holds as 2nm ramp costs hit invoices is the central Nvidia question Thursday surfaces.
AMD: The company has less room. AMD has reportedly informed partner customers of plans to raise prices by about 10% starting in Q4 2026, covering AI accelerator chips, consumer GPUs, and motherboard chipsets. Since the vast majority of AMD’s chip products are manufactured by TSMC, the rise in wafer foundry costs has directly squeezed AMD’s product gross margins, prompting the company to initiate downstream cost pass-through.
ASML, AMAT: UBS’s recent industry work finds no sign of slowing cloud AI demand, with stronger prospects than previously expected for CPUs, GPUs, and custom chips in 2027 and 2028. A $90 billion TSMC capex figure flows directly into equipment order books at both companies.
Sector Watch
The pricing wedge between foundry and fabless is widening. The list of companies affected includes Nvidia, Apple, AMD, and Qualcomm, all heavily reliant on TSMC’s most advanced manufacturing processes, and none of them have a viable alternative manufacturer for their most advanced products at comparable scale. Nvidia and Apple sit at the high pricing-power end because hyperscalers and premium consumers tolerate absolute price increases for performance. AMD and Qualcomm sit at the low end because their customers push back hard on price. That divergence is the sector trade Thursday’s call clarifies.
Catalyst Calendar
- Thursday, Oct. 15: TSMC Q3 full earnings and conference call, 2:00 AM ET. Watch the 2nm gross margin commentary and any update to 2027 capex or pricing language.
- Q4 2026: TSMC has told customers it is planning base price increases of 5% to 10% across advanced and mature nodes effective early 2027, plus a distinct 10% to 15% surcharge for high-performance computing orders exceeding initial volume commitments.
- 2027 ramp: Nvidia’s Vera Rubin platform, AMD’s MI400 series, and Apple’s A20 chip are all widely expected to be tied to TSMC’s 2nm generation. All three face a higher per-wafer baseline that has been widely reported around $30,000.
Technical Radar
TSM pulled back alongside the SOX after the October 8 OpenAI revenue report. Thursday’s revenue beat is already priced in. Support and resistance will be set by management tone on 2027 margins, not the Q3 numbers themselves. Taipei-listed TSMC shares are up sharply this year. With another record profit widely expected, the risk is that meeting forecasts may not be enough to lift the stock.
Risk Radar
Management has repeatedly signaled that leading-edge and advanced packaging capacity remains tight into 2027, and any change in tone or timeline on that is a key risk. A softer forward margin guide would reset the entire AI chip supply chain simultaneously. AMD is the most exposed name given its thinner margin buffer and the reported pass-through already underway. A stronger-than-expected 2027 capex number, conversely, would validate the AI spending cycle and lift ASML and AMAT alongside TSM.
The Cheat Sheet
- Top Market Theme: TSMC holds monopoly pricing power over the AI chip stack, and Thursday’s call is where traders find out how much of that cost each customer can actually swallow.
- Stock to Watch: AMD. It is passing higher foundry costs downstream already and has the least pricing cover among the major next-node customers.
- Sector to Watch: Semiconductors. The SOX just took a roughly 3.4% hit on demand doubt; a strong TSMC capex forecast Thursday is the fastest cure.
- Biggest Risk: A softer 2027 margin outlook from TSMC management that signals the newest node is more dilutive than guided, pulling down every fabless name simultaneously.
- Biggest Opportunity: ASML and AMAT on a confirmed $90 billion TSMC 2027 capex figure, which translates directly to equipment orders neither company has fully priced in.
- One Thing to Remember: A 2nm wafer price around $30,000 is widely reported. That bill is already in the system. Thursday tells you who built it into their margins and who is hoping the market does not notice yet.