Let’s be real for a second.
While most traders are still squinting at lagging indicators and trying to “guess” where the next move is coming from…
My top AI trading engine is already light years ahead.
I’ve spent months and a small fortune making sure this engine outclasses any other trading tool you’ll find out there.
And right now, it’s flagging the kind of setups that typically stay hidden behind the velvet ropes of hedge funds and institutional banks.
I’m talking about the ability to:
- Identify moves before they even register on a standard chart.
- Target “time-warp” returns that can compress years of gains into days.
- Choose your own risk so you never have to “bet the farm” to see results.
If you still haven’t grabbed your free access, I have to ask… What are you waiting for?
The market isn’t going to slow down for you. The robots running the show today certainly won’t wait for you to catch up.
You can keep doing things the hard way… dealing with the stress, the overthinking, and the emotional roller coaster…
Or you can let AI do the heavy lifting for you.
Claim your FREE access to the AI engine right here (No credit card required)
The proof is waiting inside.
Till the next trade,
Lance Ippolito
CEG Reports Monday. The PPA Revenue Isn’t Here Yet.
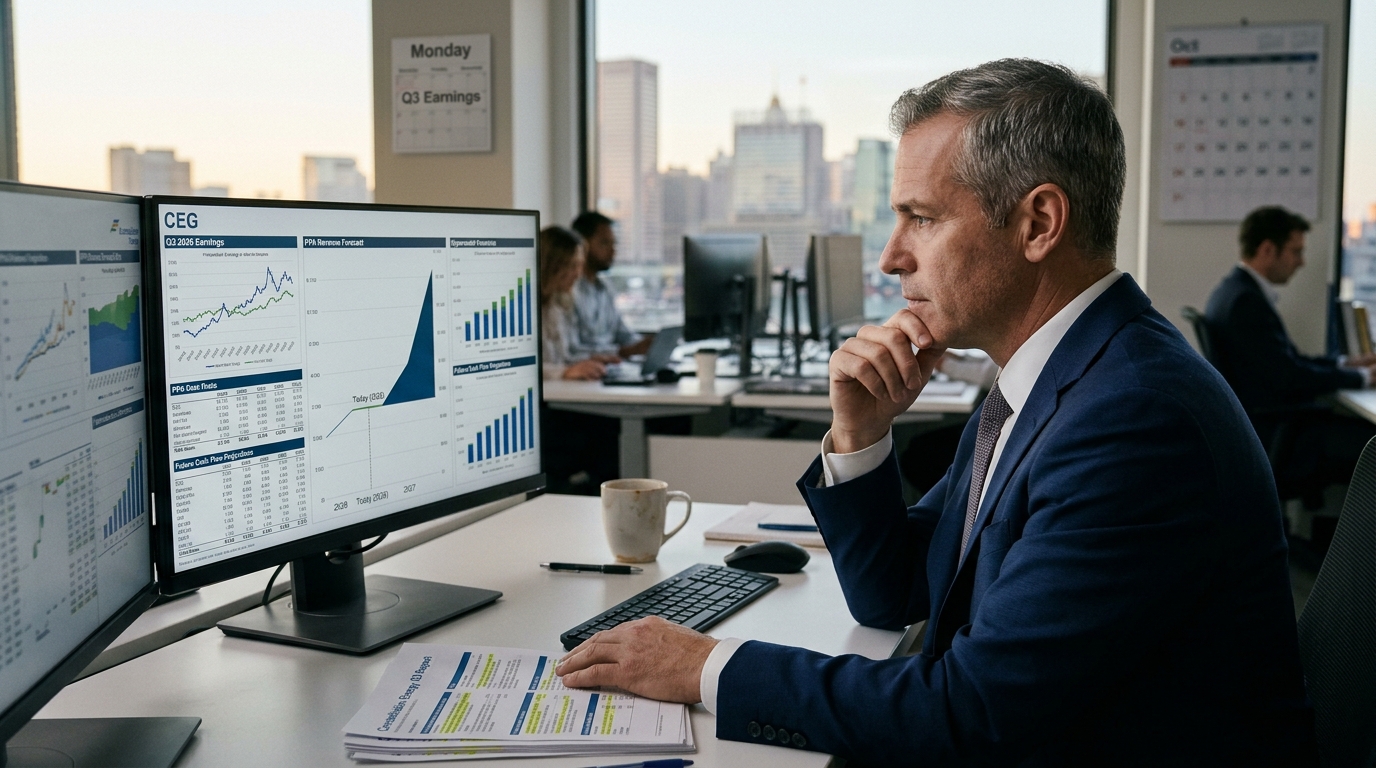
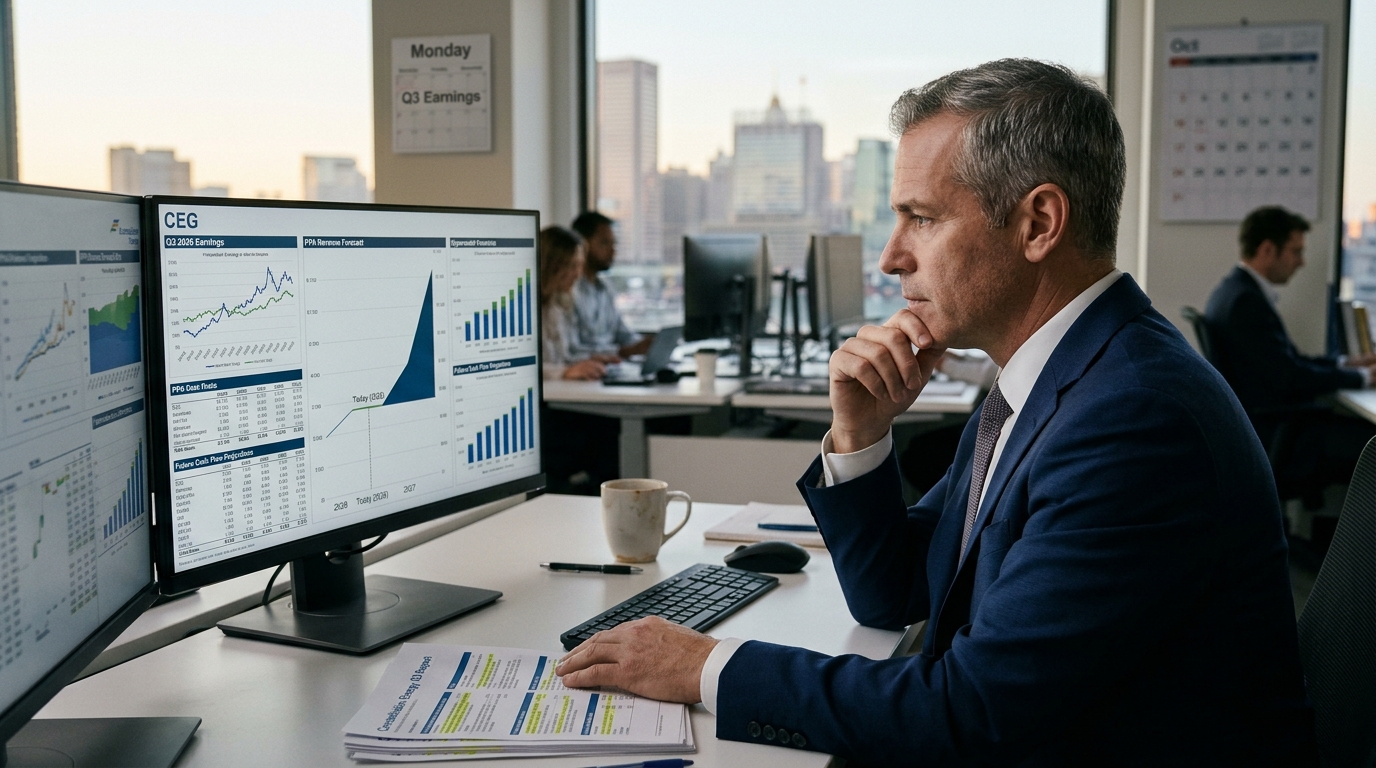
Constellation Energy reports Q3 2026 results before the open this Monday, with analysts expecting about $3.88 per share on roughly $9.2 billion in revenue. The stock has been one of the most crowded AI-power trades of the cycle. The question traders actually need to answer today is simpler and more uncomfortable: how much of the multi-decade hyperscaler contract value is actually generating cash right now?
Almost none of it. That is the structural tension hiding inside every bullish slide deck on CEG.
The Microsoft deal, a 20-year agreement tied to the restart of Three Mile Island Unit 1 (to be renamed the Crane Clean Energy Center), was announced on September 20, 2024, with the plant expected to be ready for service in 2028. Key milestones still ahead include Nuclear Regulatory Commission approvals required for restart. Revenue from that anchor contract is not on the income statement today.
The October 2026 Google deal adds 890 MW of new nuclear capacity under a 20-year PPA and supports more than $4.3 billion in upgrades to 11 CEG-owned nuclear units, with the first uprate expected by 2028. The Amazon agreement covers 690 MW under a 20-year PPA, including a 190 MW uprate at Calvert Cliffs. The 920 MW of long-term PPAs signed in Q2 2026 are structured so contracts begin in 2029 through 2032.
The market is pricing the destination. Earnings today reflect the journey.
Q2 2026 operating income came in at $580 million on $7.50 billion in revenue, an operating margin of roughly 7.7%, down from 15.6% in the prior year, as the Calpine acquisition absorbed into the cost base. Management raised full-year adjusted earnings guidance to $11.50 to $12.50 per share after Q2, alongside an EPS beat, though revenue missed expectations. The gap between strong EPS and missed revenue is precisely the tension today’s Q3 call needs to resolve.
Constellation is not the only utility absorbing a large acquisition cost base while signing long-dated nuclear PPAs. The Oracle-WEC nuclear deal in Wisconsin shows how hyperscalers absorbing fuel costs can structurally improve utility margins.
Management has guided to approximately $8.4 billion in free cash flow over 2026 and 2027, stepping up to $11.5 to $13 billion over 2028 and 2029. That step-change in 2028 and 2029 is contingent on Crane coming online, reactor uprates executing on schedule, and PJM capacity markets staying supportive. In the 2028/2029 PJM capacity auction, Constellation cleared 15,700 MW of nuclear capacity in its PJM portfolio at $325 per megawatt-day, locking in an earnings floor, but it is still a floor built on projections, not delivered megawatt-hours.
Analysts forecast Q3 EPS of about $3.88, a roughly 28% increase year-over-year, and revenues of roughly $9.2 to $9.35 billion, up about 40% to 42% from the prior year. A beat today is likely. The harder read is what management says about Crane timeline confidence and whether any of the new Google or Amazon capacity begins contributing earlier than 2028.
Traders long CEG on AI power demand are right about the direction. The debate is about timing. If this morning’s call reaffirms the 2028 ramp without slippage and Q3 EPS clears $3.88, the stock has a clear path higher into year-end. Any hint of delay on Crane or softness in capacity revenue flips that immediately. Watch the CFO commentary on operating cost absorption, not just the headline beat.