Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
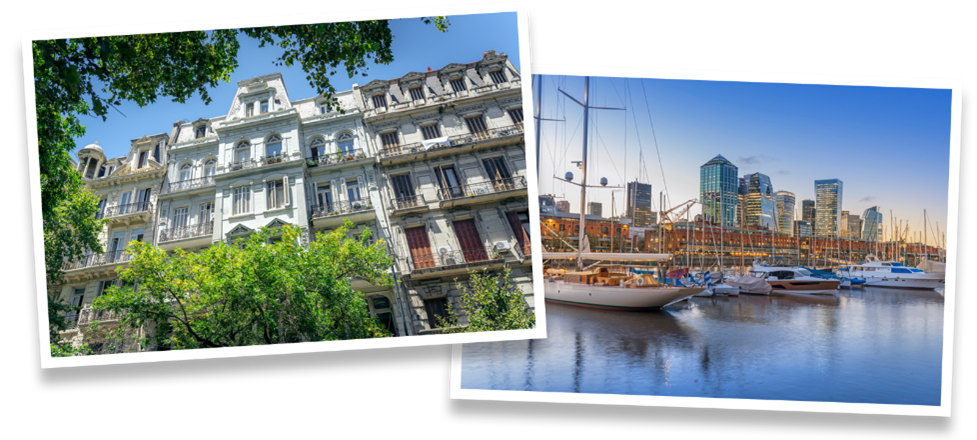
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
Alibaba Reports Thursday. Cloud Has to Carry Everything.
BABA is trading around $106, down roughly 28% year-to-date, and the Q2 FY2027 earnings on November 19 before the open are the clearest test yet of whether the AI cloud pivot is moving fast enough to offset everything pulling against it.
Market Snapshot
BABA has shed nearly 18% since the August 20 earnings report, when the stock fell to an intraday low near $122 before recovering to close around $130. That post-earnings bounce has since been fully erased. At roughly $106, the stock sits well below its 50- and 200-day moving averages, and analysts carry an average 12-month price target near $184, implying more than 70% upside that the market is plainly not willing to pay for yet.
Stocks in Focus
BABA – Reporting Thursday, November 19, Before Open
Last quarter, cloud was the saving grace. AI Cloud and Compute Services revenue surged 45% year-over-year to $7.1 billion, the fastest pace in 22 quarters, while AI-related product revenue delivered triple-digit growth for the twelfth consecutive quarter. The problem is what sat beneath that headline: net income fell 75%, free cash flow was a negative RMB 44.7 billion outflow, and non-GAAP diluted earnings per ADS of $1.26 missed consensus estimates. Capital expenditures jumped 75% year-over-year to RMB 67.7 billion as Alibaba pressed into the three-year, RMB 380 billion infrastructure commitment it announced in late February 2026.
Consensus for Q2 FY2027 is $1.61 in EPS on $40.25 billion in revenue. The revenue bar is achievable: last quarter beat the revenue estimate by about $124 million even while missing on earnings. The harder question is whether cloud sustains its acceleration or shows the first signs of deceleration as the comp gets tougher.
The domestic commerce side offers little cushion. Customer management revenues fell 7% reported last quarter, and even stripping out contra-revenue effects from Alibaba’s business development program, like-for-like growth came in at just 1%, down sharply from 8% the prior quarter. The macro backdrop hasn’t improved: China’s retail sales grew 0.4% year-on-year in August, and household loan contraction has persisted into autumn as falling home prices keep consumers in balance-sheet repair mode rather than spending mode.
Sector Watch
The result will read across China internet broadly. If AliExpress cross-border logistics shows continued margin improvement, it reached operating profit last quarter for the first time, that signals sustainable international diversification. If quick commerce (up 45% last quarter) maintains momentum while unit economics keep improving, it argues the domestic spend on fulfillment is not a margin-destruction story but a market-share acquisition play.
Technical Radar
- Key support: $100 is the psychological and structural floor, tested but not broken in October.
- Key resistance: $115 to $120 is where the stock failed after the August bounce; reclaiming that zone requires a clean result.
- Watch: Options traders are pricing roughly an 8% implied move into the event.
The Cheat Sheet
Top theme: AI capex cycle versus near-term profitability. The question isn’t whether Alibaba is investing correctly – it’s whether cloud growth is accelerating fast enough to justify the income statement damage.
What to watch: Cloud revenue growth rate. If it sustains at or above 45%, the AI monetization case holds. If it decelerates meaningfully, the miss pattern that has plagued four consecutive quarters gets harder to wave away. Domestic CMR is secondary but confirms consumer health.
Biggest risk: A third consecutive large EPS miss combined with slowing cloud growth would be the worst combination, removing the one offset the bulls rely on.
One thing to remember: Alibaba Cloud’s growth rate ranked among the fastest of the major global cloud providers last quarter. That position only holds if the capex being spent now converts into durable enterprise AI contracts. Thursday tells traders whether the conversion is on schedule.
The deceleration risk is not hypothetical. AWS and Azure both saw cloud growth stall when enterprise customers slowed migration spending during a prior macro downturn.