Editor’s Note: Former $900 million hedge-fund manager Larry Benedict completed 20 consecutive years without a losing year and took his fund into the top 1% worldwide. Today, he says one long forgotten American giant already possesses what Elon Musk needs to bring his $119 billion plan to life. Click here to get the ticker completely free or read more below.
Dear Reader,
Nvidia CEO Jensen Huang issued a blunt warning about Elon Musk’s new $119 billion plan.
He says it will be “extremely hard” to pull off.
For most investors, that sounds like a reason to stay away.
But Wall Street legend Larry Benedict sees a rare opportunity forming in one particular ticker.
It’s a once-great American company that Wall Street dismissed after years of setbacks.
And Larry says it could be the key to potentially making all the money you need, in any market.
That is a bold call… but if anyone has earned the right to make it, it’s Larry…
You see, between 2004 and 2012 alone, his hedge fund generated more than $274 million in audited net income.
And during his career, Larry managed more than $900 million. .
He built that record by recognizing market-moving opportunities before Wall Street caught on.
Now he says this could be one of them.
Even a small move in its shares could give you a shot at doubling your money with the right strategy.
Regards,
Lauren Wingfield
Managing Editor, The Opportunistic Trader
P.S. Whether Elon succeeds with his plan or not, Larry believes you will have chances to profit. But you need to be positioned before November 30 – or risk missing out completely.
Birkenstock’s December Report Has One Number That Matters
Birkenstock is about to answer the question its stock has been asking since August. The company will release fourth-quarter and full fiscal year 2026 results on December 10, before the U.S. market opens. That report closes a year defined less by sandal volume and more by a structural change in what Birkenstock actually sells.
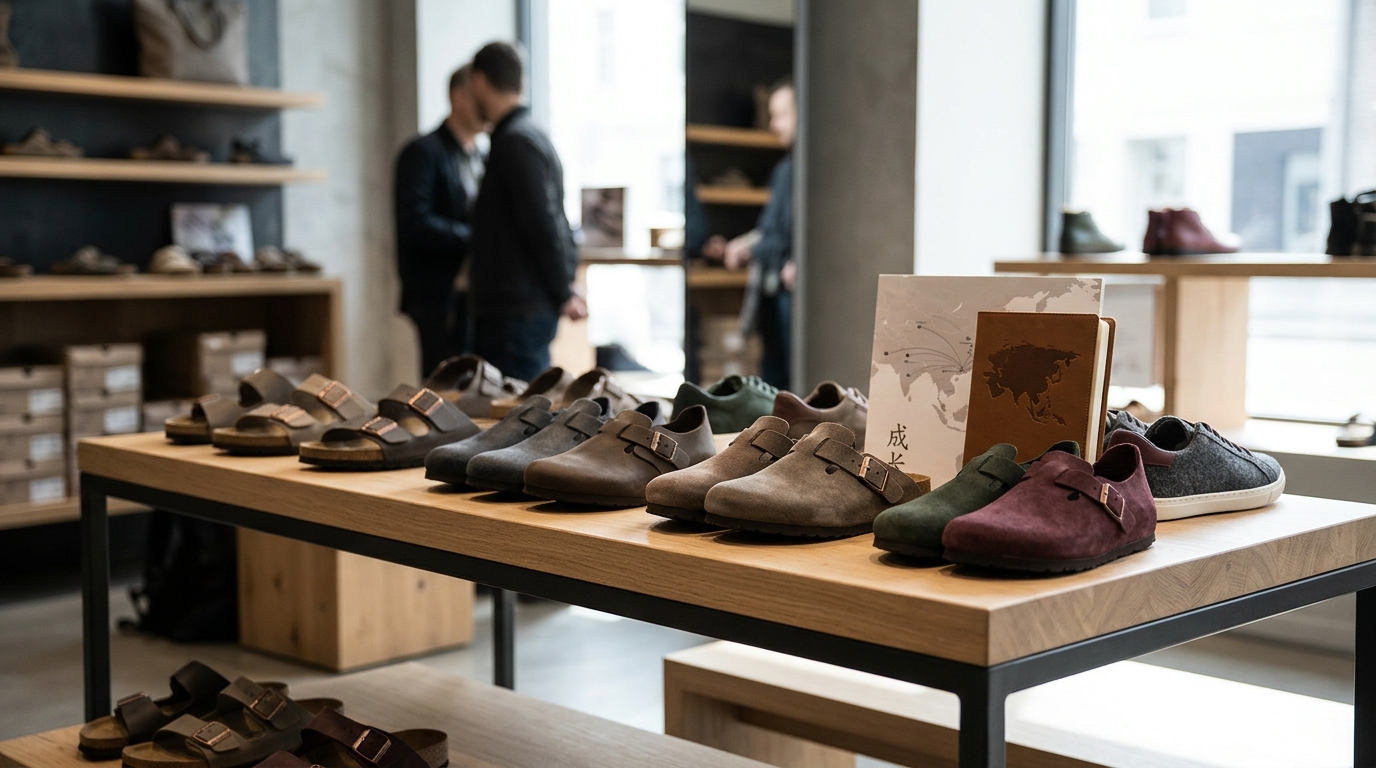
The pivot matters because sandals are seasonal. Closed-toe shoes are not. Closed-toe styles now account for 38% of revenue, up from 33% a year earlier, extending the brand’s reach into all-weather, year-round occasions. Through the first three quarters of fiscal 2026, non-Boston closed-toe silhouettes rose more than 50% in units. That is not a fashion bump. It is a category expansion that changes the ceiling on the revenue model.
The China angle is equally important and less discussed. On the Q3 call, management said China grew over 50% and described it as the company’s highest average selling price market. Management has also said APAC is expected to continue growing at roughly twice the pace of other segments over the medium term, supported by a retail-led strategy and localized brand activations. That is where Birkenstock commands its richest pricing, which matters for gross margin far more than raw unit growth.
Gross margin is the number traders should anchor to on December 10. In Q3, adjusted gross margin came in at 59.2%, pressured by currency translation and incremental U.S. tariffs. Future margin expansion is expected to come from bringing more production of complex closed-toe and boot executions in-house, work that management has said is currently done in part by contract manufacturers in Portugal. If the Q4 read shows that shift is taking hold, the margin trajectory looks different heading into fiscal 2027.
The other variable is direct-to-consumer penetration. DTC revenue outpaced B2B in Q3, rising 14% on a reported basis and 16% in constant currency, with penetration reaching 39%. On the Q3 call, management said it was on track for approximately 140 owned retail doors by the end of fiscal 2026, with high single-digit same-store sales growth. Every door added is a data point Birkenstock captures directly, without a wholesale intermediary setting the shelf price.
The valuation debate is real. Bears flag valuation risk after the recent swing and a large follow-on offering. The stock jumped roughly 15% the day Q3 results dropped and has carried that premium into December’s setup. At that multiple, the market is not pricing in a sandal company. It is pricing in a year-round premium footwear brand with a China growth engine and a margin expansion story tied to in-house production. December 10 is when that thesis gets its first full-year test.
What Traders Should Watch on December 10
- Closed-toe revenue share: Does it hold at 38% or push toward 40%? Movement here signals whether the category shift is durable.
- Adjusted gross margin vs. Q3’s 59.2%: Any improvement suggests tariff and FX drag is stabilizing and in-sourcing is adding lift.
- APAC growth rate: A deceleration from 23% constant-currency in Q3 would be the clearest sign the China story is maturing faster than expected.
- Fiscal 2027 guidance tone: The stock is priced for acceleration. Conservative guidance would pressure shares immediately at the open.