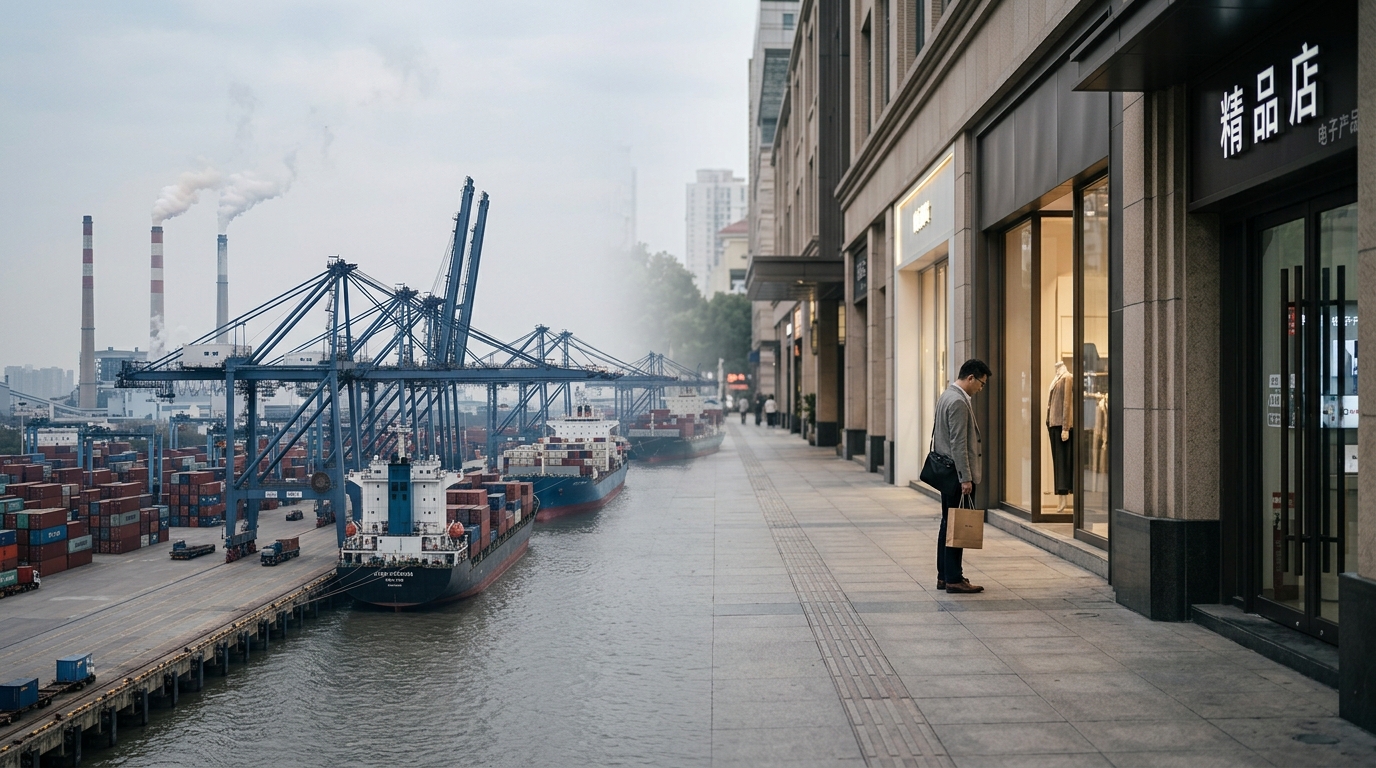
The numbers arrived at 0200 GMT this morning, and they told two completely different stories about the same economy.
According to China’s National Bureau of Statistics, industrial output expanded 5.2% in August, accelerating from 4.5% in July and beating expectations for a 4.8% rise. Retail sales grew just 0.4% from a year earlier, slowing from 0.6% in the prior month and missing the forecast of 0.8%. That is not a mixed report. That is a structurally broken economy in which the factory keeps running while the consumer goes quiet.
Why Wall Street Cares
The gap between those two figures is not just a China problem. It is a global goods price problem, and by extension, a Fed problem. As Chinese manufacturers cut prices to move excess inventory abroad, they compress margins for competitors across Southeast Asia and Europe. Persistent Chinese disinflation also complicates the Federal Reserve’s own inflation calculus, feeding into global rate-setting decisions well beyond Beijing’s borders.
The timing matters enormously. The Associated Press reported this month that President Trump is expected to host Xi Jinping in Washington on September 24, following their May meeting in Beijing. Whatever diplomatic choreography surrounds that meeting, this morning’s data will be sitting in the room.
The Bull Case for Global Disinflation
One camp reads today’s divergence as straightforwardly good news for developed-market central banks. The real action in global goods inflation or, more precisely, disinflation, is unfolding not in America but in China, where industrial overcapacity and collapsing prices tell a far more consequential story than tariffs at the border. Capital Economics has argued that factory gate prices for consumer durables in China are falling at their fastest pace since 2009, and that Chinese export prices have slumped more than 20% over the past two years. A Fed still watching core goods, take note.
The strength in China’s industrial output is also concentrated where deflation pressure is most intense. The National Bureau of Statistics said equipment manufacturing value-added grew 12.1% and high-tech manufacturing 16.7% in August, respectively 6.9 and 11.5 percentage points faster than overall industrial output. More supply from sectors already in price-war mode.
The Bear Case
The opposing argument is that this data pattern is not a gift. It is a structural trap. The mixed data underscores deepening imbalances in the world’s second-largest economy. The pattern of export-facing industry holding up while domestic demand and investment lag tends to support producer-heavy sectors and China-exposed exporters more than domestically focused consumer names.
For the first eight months of the year, fixed-asset investment fell 7.2% from a year earlier, steepening from a 6.7% decline through July, according to the National Bureau of Statistics. The urban unemployment rate ticked up to 5.3% in August from 5.2% in July. An economy investing less and employing fewer people is not one that will absorb its own output. That surplus production has to go somewhere, and it goes onto world markets at discounted prices, compressing margins for everyone who competes with China.
What Investors Are Missing
The conversation has focused on whether Chinese disinflation helps or hurts Western consumers. The overlooked implication is what it does to copper and other industrial metals. If Chinese output keeps accelerating without domestic demand recovering, the incremental production surge does not translate into commodity consumption. It translates into finished goods flooding export markets, which is disinflationary for goods but not necessarily bullish for raw material demand. Copper, widely used as a proxy for Chinese growth, may be pricing the factory beat without adequately discounting the investment collapse.
Reuters reported Tuesday that the investment miss, alongside retail sales undershooting forecasts, raises the likelihood of additional stimulus measures being unveiled before October’s Golden Week, which markets are likely to watch as the next catalyst. Whether Beijing acts before Xi boards the plane to Washington is the question traders should be tracking.
Stocks to Watch
- Alibaba (BABA): Domestic consumption is its core revenue engine. A retail sales reading at the weakest since May is not a foundation for accelerating Chinese e-commerce growth. Watch for any shift in guidance language around consumer confidence in the next earnings call.
- PDD Holdings (PDD): Its discount-first model makes it structurally better positioned than peers when Chinese consumers retrench. In a 0.4% retail sales environment, the cheapest option wins market share.
- FXI (iShares China Large-Cap ETF): The blunt instrument for positioning around the summit. Carries both the consumer weakness and the industrial beat. Expect volatility as September 24 approaches and any tariff language from Washington gets repriced.
- Copper futures: The disconnect between factory output accelerating and investment contracting is a direct challenge to the commodity’s China-growth-proxy status. Worth monitoring whether the industrial beat translates into actual raw material demand or simply more finished goods supply hitting world markets.