September 29, 2026
Bonus Content: Lindt Slashes Its 2026 Growth Outlook. Europe Is the Problem.
What If the Gold & Silver Run Isn’t Done?
Gold and silver have already made a lot of investors feel late.
The majors moved first. The obvious names got the headlines. And now, after one of the strongest precious metals runs in years, plenty of investors are asking the same question:
Did I already miss it?
Maybe not.
Because when a metals cycle gets this hot, Wall Street usually starts hunting for the next layer. Not the giants everyone already owns. The smaller, stranger, overlooked stories that still have something left to prove.
That is where this under $1 gold-silver story starts to get interesting.
It’s not waiting years on a drill result. It’s targeting 2026 production from material already sitting above ground, with potential cash flow.
So while gold and silver are already in motion, this one may still be sitting in the part of the curve investors tend to miss..
See why this under $1 gold-silver story is gaining attention…
Lindt Slashes Its 2026 Growth Outlook. Europe Is the Problem.
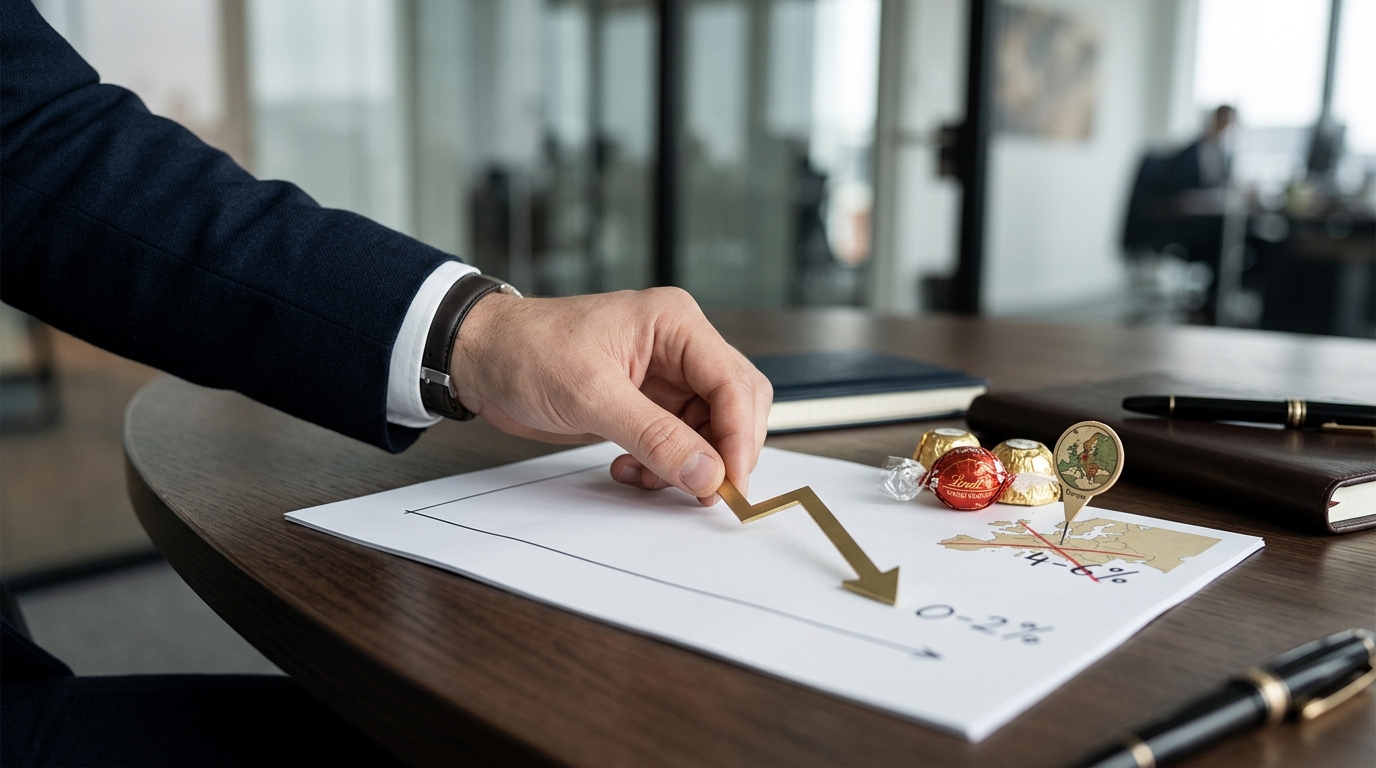
Lindt & Sprüngli fell more than 6% at Tuesday’s open after cutting its 2026 organic sales growth target to 0–2% from 4–6%, the second downward revision since March. The stock was trading around CHF 8,600 early Tuesday, closer to the lower end of its CHF 8,255–9,255 52-week range. What matters for traders watching the broader packaged-food space: cocoa is no longer the headline risk. The European consumer is.
What Happened
CEO Adalbert Lechner cited “necessary price increases due to historically high cocoa prices in recent years, and subdued consumer sentiment” as the drivers of weaker-than-expected order volumes across certain European markets, particularly in seasonal products. The unusually hot summer was also cited as a factor behind the weaker demand.
Decreased consumer sentiment and growing economic concern led to weaker-than-expected order volumes specifically in Germany, Switzerland, and Austria. Those are Lindt’s core European markets, not peripheral ones. When the core bleeds, it matters.
Lindt also pointed to selective price decreases in key markets, particularly in parts of its Christmas portfolio, as it tries to support demand into its most important season.
Why It Matters Beyond Lindt
A second guidance cut within six months risks denting management credibility, which has been an important support for Lindt’s premium valuation. That observation points to something broader: premium pricing power across food categories is under stress in continental Europe, and the damage is not just weather-related noise.
In Q2, Europe was a soft spot in the numbers for large global snack and packaged-food players, including Mondelez, which reported a decline in Europe in its Q2 disclosures. Lindt’s warning Tuesday suggests the demand pressure has carried into the second half. Nestlé, which is due to report Q3 sales in October, has significant European exposure and deserves close attention.
Barry Callebaut, which supplies bulk chocolate to industrial manufacturers and is therefore one step upstream from Lindt, has its own volume pressure to navigate. If branded confectioners are cutting prices into Christmas, ingredient orders follow with a lag.
The One Offset
Despite the weaker sales forecast, Lindt maintained its guidance for a 20 to 40 basis point improvement in its 2026 operating profit margin, and reiterated its medium- to long-term targets for 6% to 8% organic sales growth from 2028 onwards. Management is protecting margin by letting volume slide rather than defending volume by letting margin slide. That discipline is worth noting, but it does not change the demand signal the guidance cut sends to peers.
Levels to Watch
- Lindt (LISP SW): The stock opened around CHF 8,600. A close below the round-number CHF 8,500 area would keep momentum negative heading into the Christmas order period, where seasonal volumes are precisely the business under pressure.
- Mondelez (MDLZ): European weakness is already visible in the Q2 disclosures. Watch for any pre-announcement or guidance commentary ahead of its October earnings call.
- Hershey (HSY): Less European exposure, but price sensitivity on core confectionery at home has been a recurring theme in 2026 results.
The Cheat Sheet
Top Theme: European consumer fatigue from food price inflation is now forcing premium confectioners into selective price cuts, shifting risk from input costs to volume and mix.
Stock to Watch: Lindt (LISP SW). The gap between a maintained margin target and a near-zero growth outlook is the operating tension every packaged-food analyst will interrogate through year-end.
Biggest Risk: If Christmas seasonal orders in Germany and Switzerland disappoint further, a third guidance revision becomes possible, and any stock holding a premium multiple on European food exposure revalues with it.
One Thing to Remember: Even with some easing in cocoa, Lindt still cut. That tells you the demand problem is durable, not a cost story in disguise.