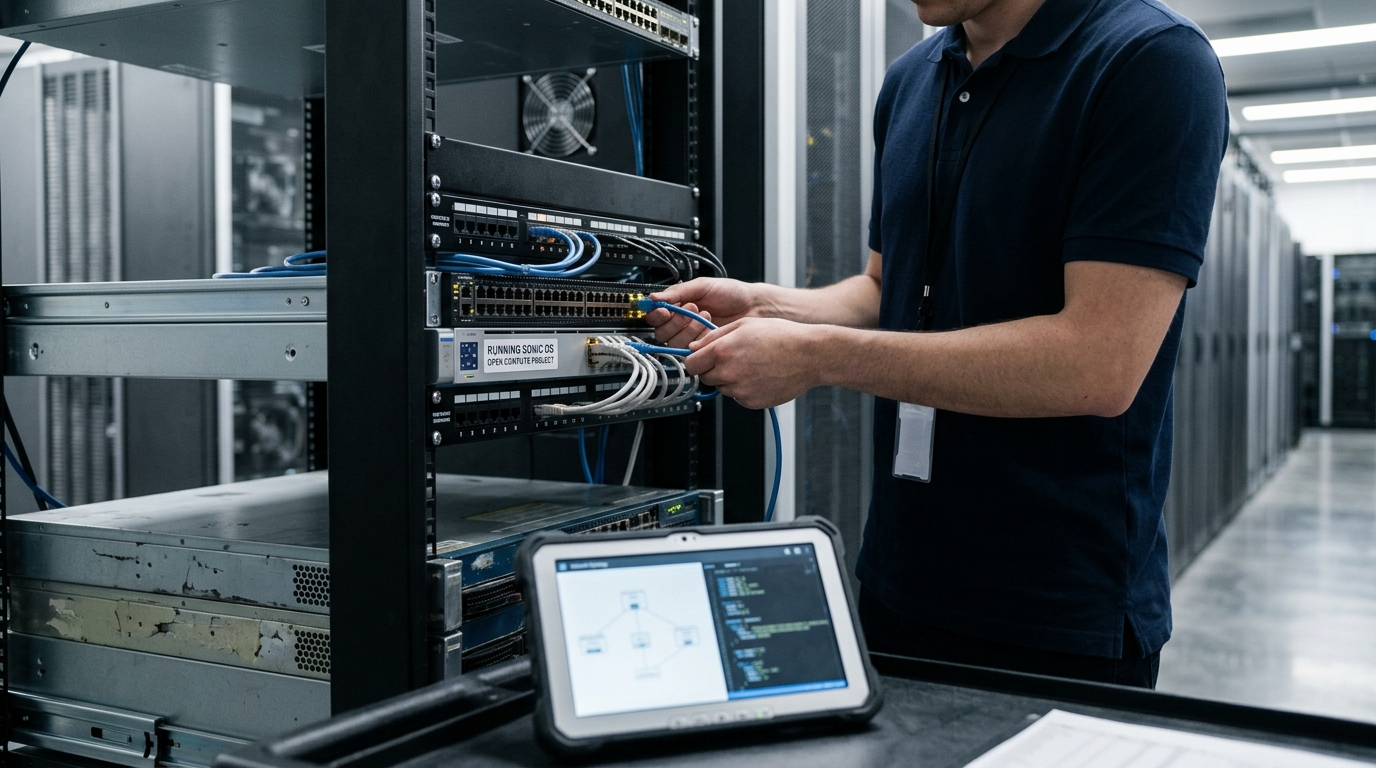
The threat to incumbent networking hardware vendors is not a rival product. It is a philosophy, and it has been compounding quietly for a decade.
Where the pressure is coming from
SONiC, the open-source network operating system Microsoft developed and open-sourced in 2016 by contributing it to the Open Compute Project, was originally a tool for running Azure at scale. Claims that “more than 80%” of Azure fabrics run SONiC, or that Meta has “standardized” on the platform, are widely repeated but not consistently backed by on-the-record, primary disclosures, so treat them as directional rather than definitive. What is clear is that SONiC moved from hyperscaler infrastructure into the broader vendor ecosystem, and it is now being positioned for enterprise use by both silicon and switch vendors.
The commercial logic is not subtle. For organizations that need a data center leaf-spine fabric at scale and want to reduce dependence on per-port licensing as they scale, SONiC is an increasingly credible option in 2026. Multiply that across a mid-size enterprise refreshing several hundred switches, and the savings can dwarf the integration cost.
The incumbents are on notice
Cisco’s risk disclosures have been flagging the same core issue: competition from networking products built on commoditized hardware, including “white box” hardware, and the possibility that architectural choices can narrow Cisco’s opportunities before a product is even selected.
That is a carefully worded acknowledgment that the battle is being lost upstream of the product decision. Juniper’s combination with Hewlett Packard Enterprise closed on July 2, 2025, and HPE has positioned the deal around AI-native networking software bundled into a broader infrastructure portfolio, in part to counter hardware commoditization. Meanwhile, as SONiC adds enterprise features, mid-market customers may also defect, compressing addressable revenue for premium products.
The tipping point may already be here
Projections about enterprise SONiC adoption vary by source and are often published in paywalled research, so the exact “over 25% year-over-year through 2027” figure should be treated as an estimate rather than a verifiable fact in this format. Directionally, the thesis is that SONiC adoption is still early in enterprise, but growing, helped by practical features like security hardening and automation-oriented provisioning.
The broader “white-box networking market” figures cited here appear to come from secondary aggregator-style market reports rather than a transparent primary dataset. If you use them, treat them as rough market-sizing estimates, not as a tradeable single point of truth.
The margin math is uncomfortable for legacy vendors. If port pricing keeps sliding while volumes rise, that is the signature of a commoditizing market, and white-box pressure is the accelerant. However, the specific claim about “the seventh consecutive quarter” of per-port price declines in 2025 could not be verified from a primary, attributable source in this review, so it should be read as a qualitative description rather than a precise statistic.
What traders should watch
Cisco’s gross margin sits near 64.8% today on a non-GAAP basis, but the structural question is how long software-led disaggregation can be offset by subscription growth and AI-adjacent wins. Cisco’s IOS XR licensing for the 8000 Series includes subscription-oriented consumption models. Arista markets EOS in multiple form factors, including virtual and containerized deployments, and it has historically promoted “open networking” positioning, but EOS is not generally a free-to-run NOS for arbitrary third-party switches under standard commercial terms. The companies willing to lower hardware dependence before someone else does it for them will survive this transition. The ones clinging to proprietary margin structures will not.