October 28, 2026
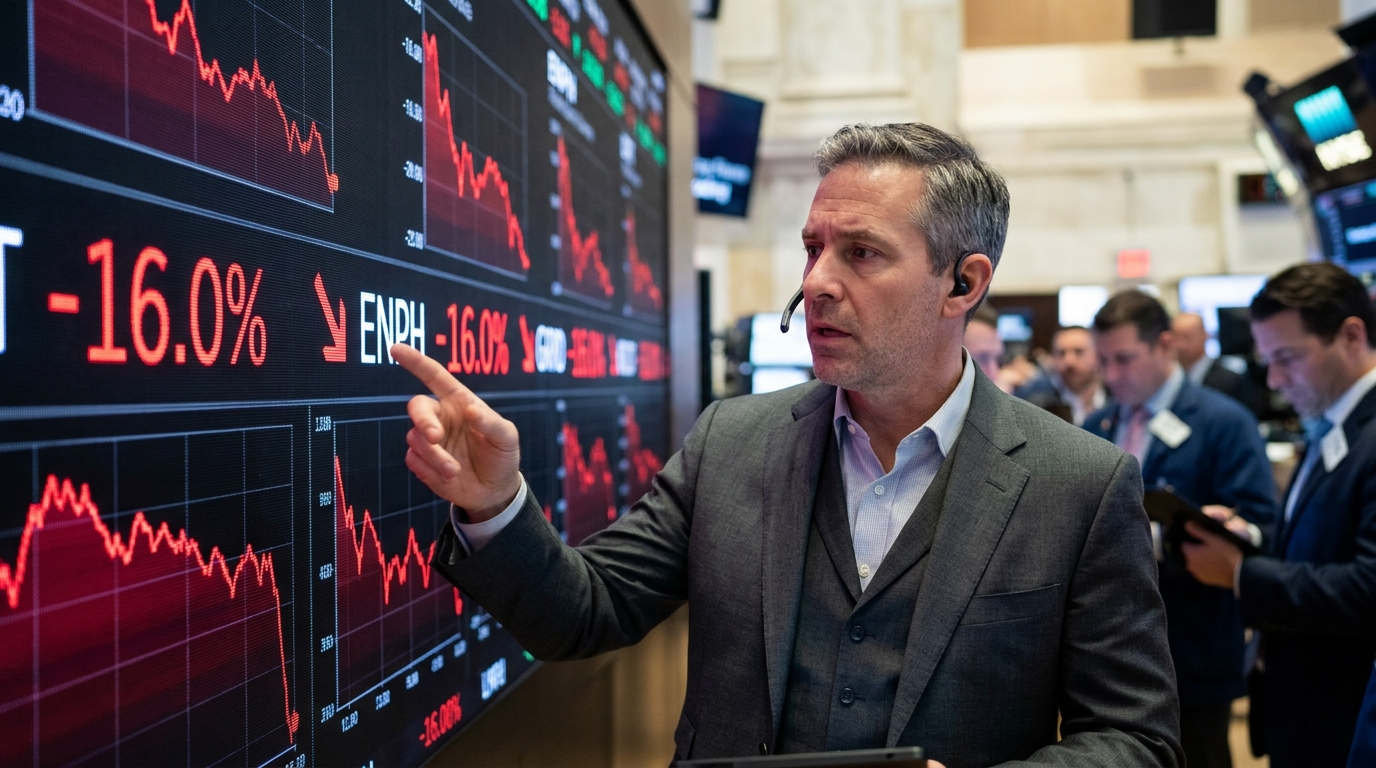
Bonus Content: Enphase Drops 16% After Missing on Revenue, Earnings, and Guidance
Ian Cooper here,
For the longest time…
I thought successful options trading required:
- ❌ Staring at charts all day
- ❌ Learning 100 different strategies
- ❌ Taking huge risks
- ❌ “Predicting” the market perfectly
And honestly?
That belief nearly cost me everything.
I was overwhelmed, confused, and constantly second-guessing every trade.
Then I discovered something that completely changed the game…
A surprisingly SIMPLE options setup that helped me stop overthinking and start trading with clarity.
No complicated indicators.
No endless market analysis.
No “Wall Street genius” required.
Just a straightforward approach almost anyone can learn.
That’s why I just released this FREE report:
“The $50 to $500 Options Strategy;
Inside, you’ll discover:
- ✔ The #1 mistake rookie options traders make
- ✔ A simple & repeatable trade setup
- ✔ Step-by-step trade blueprints you can copy tonight
- ✔ How to ignore the noise and focus on bigger opportunities
👉 Get your free copy here now.
In your corner,
Ian Cooper
Enphase Drops 16% After Missing on Revenue, Earnings, and Guidance
Market Snapshot
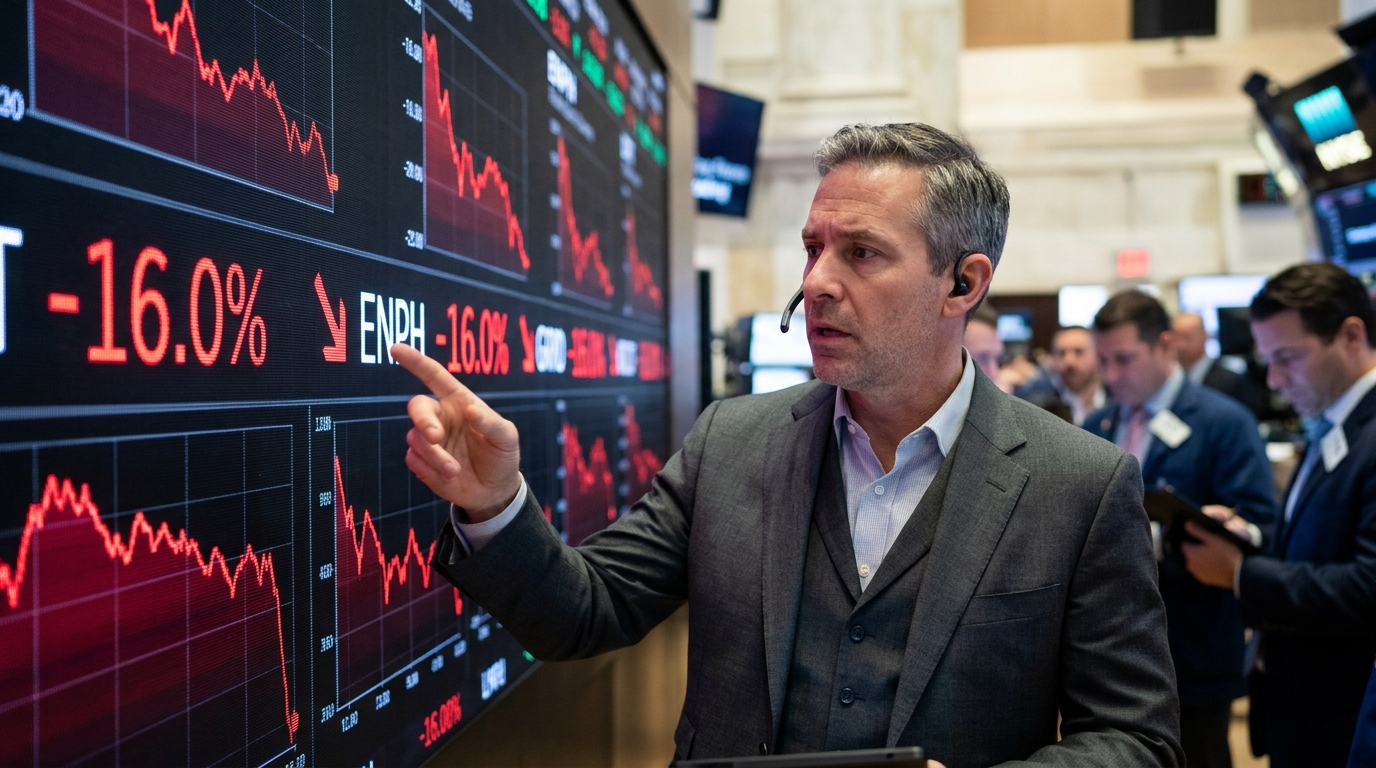
ENPH entered Wednesday’s session in freefall. Enphase Energy stock was down about 15% in after-hours trading after the company released its third-quarter 2026 financial results following Tuesday’s close, posting a double miss on earnings and revenue while issuing fourth-quarter guidance that fell dramatically short of analyst expectations. The after-hours slide pushed the stock toward its 52-week low. That after-hours price was just above the 52-week low of $25.78 and far below the 52-week high of $73.74.
Stocks in Focus
Enphase Energy (ENPH)
What happened: Quarterly revenue fell about 28.5% year-over-year to $293.3 million, below analyst estimates of roughly $304 million. Enphase posted non-GAAP Q3 2026 earnings of $0.41, which missed the consensus estimate of $0.51 by $0.10. The company shipped 1.42 million microinverters and 129.9 megawatt-hours of batteries.
Why it matters: The earnings miss was not a rounding error. The earnings miss was larger than the revenue miss, suggesting that margin pressure weighed more heavily than the sales shortfall. That matters because Enphase has been trying to show that it can preserve profitability even in a weak solar market. CEO Badri Kothandaraman noted that U.S. sell-through fell 35% year-over-year, attributing the pressure to elevated interest rates and the expiration of the tax credit that allowed homeowners to deduct 30% of the cost of installing qualifying renewable energy systems.
The guidance problem: Enphase’s Q4 2026 revenue guidance range of $225 million to $255 million, with a midpoint of $240 million, was substantially below the analyst consensus of approximately $300.5 million, implying a further sequential decline in sell-through. Q4 GAAP gross margin guidance is 38.0% to 41.0%, including approximately 2.0 percentage points of reciprocal tariff impact. Management also said it is not seeing any meaningful recovery in U.S. demand.
What to watch: Supply chain dependency remains a structural vulnerability, with critical LFP battery cells sourced exclusively from two Chinese vendors. On the longer-term pivot, the company plans to focus on five growth drivers for 2027: residential batteries, U.S. residential solar recovery, commercial solar and battery business, bidirectional EV charging, and AI data centers with IQ Solid-State Transformer technology. But the data center vertical is a long-term play, with commercial revenue not anticipated until 2028.
Supply chain failures and guidance resets are not unique to Enphase this cycle. Fluence cut its full-year revenue guidance twice in five weeks on the same manufacturing ramp problem, showing how quickly energy storage companies can lose credibility when execution slips.
Sector Read-Through: SEDG and RUN
SolarEdge Technologies (SEDG) is set to report third-quarter 2026 earnings on November 4, 2026. Enphase’s results set an uncomfortable backdrop. The same demand forces crushing ENPH, elevated rates and the post-Section 25D hangover, apply directly to SEDG’s residential inverter business. Federal legislation accelerated the end of the 30% homeowner tax credit, and the Section 25D credit is generally not available for expenditures made after December 31, 2025. Sunrun (RUN) faces the same structural headwind and has its own quarterly report ahead. Both names should be treated as at-risk until they report.
Risk Radar
- Margin compression ahead: Q4 GAAP gross margin guidance of 38.0% to 41.0% includes approximately 2.0 percentage points of reciprocal tariff impact, an increased headwind versus recent quarters.
- Inventory overhang: Enphase exited Q3 with channel inventory a little above normal for both batteries and microinverters, and management plans to ship below sell-through in Q4 to drain it.
- Sector contagion: A result this weak from the sector’s most-watched name will pressure SEDG and RUN at the open before either company has a chance to tell its own story.
The Cheat Sheet
- Top Theme: Residential solar demand remains broken well into late 2026, and no catalyst is visible before 2027.
- Stock to Watch: ENPH, for the size of the opening gap and whether buyers step in near the 52-week low around $25.78.
- Sector to Watch: Solar. SEDG and RUN will trade on ENPH’s read-through all session.
- Biggest Risk: Q4 guidance with a midpoint of $240 million against a roughly $300 million consensus is a reset, not a trim. Further estimate cuts are coming.
- Biggest Opportunity: A washout open in ENPH near multi-year lows could attract mean-reversion traders if broader market conditions hold.
- One Thing to Remember: Enphase said it plainly on the call: no meaningful U.S. demand recovery in sight. Until rates fall or a policy replacement for Section 25D emerges, this sector trades on hope, not fundamentals.