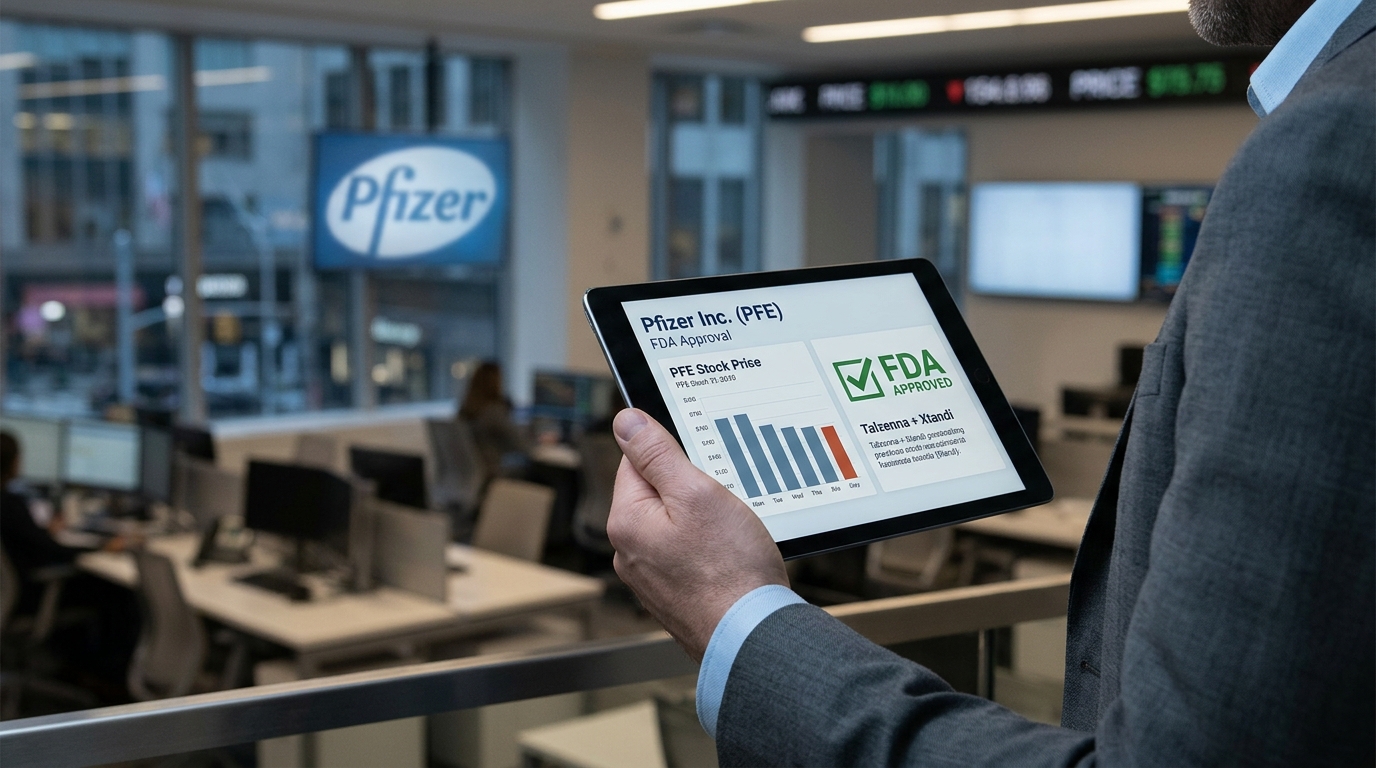
Pfizer had genuinely good clinical news on Monday. The FDA approved Talzenna (talazoparib) in combination with Xtandi (enzalutamide) on October 26, 2026, for adults with metastatic androgen pathway modulation-naive or -sensitive prostate cancer whose tumours carry mutations in homologous recombination repair genes, as detected by an FDA-authorized test. The approval moves the combination into an earlier line of treatment than before, when the disease is still responding to hormone therapy.
This makes Talzenna the first PARP inhibitor cleared by the FDA in this metastatic hormone-sensitive (androgen pathway modulation-naive or -sensitive) setting, giving patients a chemotherapy-free option earlier in the course of their disease. The phase 3 TALAPRO-3 trial showed that adding Talzenna to Xtandi reduced the risk of radiographic progression or death by 52% compared with Xtandi plus placebo. An estimated 77% of patients remained progression-free at three years. By any clinical measure, that is a meaningful result.
PFE fell 0.80% on announcement day and is barely flat overnight. The label answers the question of whether the drug works. The market is asking a different one: does this move the needle for Pfizer?
The safety data is the first complication. Anaemia was the most common grade 3 or higher adverse event, reported by 51% of patients in the combination group versus 3% in the control group. Grade 3 or higher adverse events hit 81% of talazoparib patients compared with 44% on placebo. Five percent of patients discontinued Talzenna due to anaemia alone. Physicians prescribing earlier in the treatment line, when patients are less sick, tend to weigh toxicity heavily. That bar is harder to clear.
The revenue math is the second issue. Talzenna brought in $107 million in the first half of 2026, up about 24% year over year, but it remains a small contributor to Pfizer’s oncology portfolio. Analysts at RBC Capital Markets had previously said the expansion into the hormone-sensitive setting would likely have a “negligible” impact on Pfizer’s bottom line. Eligibility is also gated: HRR mutation confirmation is a mandatory eligibility requirement, meaning patients must have an HRR gene mutation detected by an FDA-authorized test. That biomarker filter keeps the addressable population smaller than the broader prostate cancer market suggests.
The competitive context matters too. AstraZeneca retains the strongest integrated position in the PARP inhibitor class, with Lynparza co-marketed with Merck. J&J’s oncology sales rose 17.8% operationally in Q1 2026, driven by prostate cancer drug Erleada among others. Pfizer is pushing into a setting where clinical credibility exists but commercial dominance is far from assured.
What Traders Should Watch
- PFE earnings on November 3. Pfizer enters that report with stronger oncology and vaccine developments, but valuation and patent-expiration concerns remain. The Talzenna expansion will be framed as a pipeline win; listen for any early commercial guidance.
- Prescription uptake cadence. The mHSPC setting reaches patients earlier, which is a larger pool in theory. In practice, physician comfort with the anaemia rate determines how fast oncologists move.
- AZN and MRK as read-throughs. A Talzenna share gain in HRR-mutated mHSPC comes partly at the expense of Lynparza’s positioning. Watch for any AstraZeneca or Merck commentary on biomarker-selected prostate cancer volumes.
- JNJ’s Akeega. Niraparib plus abiraterone already holds ground in the castration-sensitive setting for BRCA2-mutated disease. Any label or label-adjacent competition between these two PARP combinations is the real commercial story to track.
The approval is real and patients benefit from it. For traders, the honest read is that Talzenna is a small, biomarker-restricted franchise inside a very large company, gaining ground in a crowded field with a safety profile that will slow adoption. A win for the pipeline. Not a catalyst for the stock.