The pitch for European equities this year was straightforward: lower AI concentration, steadier earnings, a hedge against the froth on Wall Street. For roughly 48 hours after Tuesday’s midterm results, it held. By Friday morning in London, it was gone.
The pan-European Stoxx 600 dropped 1.6% to 644.72 points, with benchmarks in most major regional markets down more than 1%. Friday’s losses wiped out its gains for the week, leaving it about 0.2% lower. That is not a rounding error. That is a week of positioning erased before lunch.
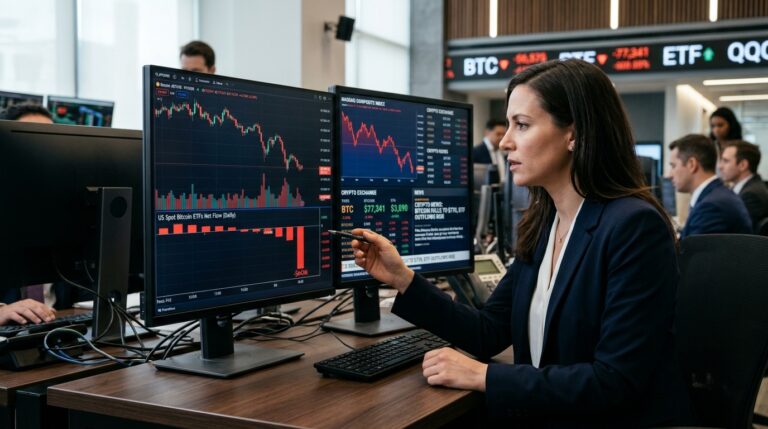
The proximate cause was what happened Thursday in New York. The Nasdaq Composite sank 5.5% into correction territory, while the S&P 500 fell about 4.4% and the Dow lost roughly 1,833 points, or 3.4%. All three posted their steepest one-day declines since the April 2025 “Liberation Day” tariff shock. Approximately $3 trillion was erased from the market value of S&P 500 companies during the selloff, according to Reuters.
The specific fear driving the selling: Democrats’ electoral victories in both the House and Senate, alongside crucial governorships in key states, fuelled traders’ concerns about a potential slowdown in data-centre construction, an industry closely linked to AI growth. Voters overwhelmingly backed restrictions on data-centre construction in local ballot measures tracked by Ballotpedia, adding to concerns about political resistance to the AI infrastructure buildout.
Overnight the rout crossed every border. Japan’s Nikkei 225 officially entered a bear market on Friday after a 6.2% decline that pushed the index more than 20% below its June peak. South Korea’s Kospi plunged as much as 8.8%, triggering a trading halt and briefly falling below the closely watched 5,000 level. The chip companies at the centre of Korea’s index were obliterated: SK Hynix plunged 10.44%, while Samsung Electronics shed 6.35%. Samsung and SK Hynix together account for roughly half of the Kospi’s market capitalisation, making the broader index particularly sensitive to changes in their share prices.
Now back to Europe and the diversification question. The standard argument for the Stoxx 600 as a partial hedge rests on its smaller AI weighting. The index was relatively less impacted this week than its Asian and Wall Street peers, given its smaller exposure to AI stocks. True enough in percentage terms. But smaller damage is not the same as protection. Media, healthcare and retail led the European declines, falling over 2% each. These are not AI companies. They sold off anyway.
“The scale of the falls in some of the market’s biggest names has been striking. But it also highlights the concentration risk that has built up in U.S. equity markets,” said Stuart Clark, portfolio manager at Quilter, emphasising how vulnerabilities in a limited number of technology and semiconductor stocks quickly translate to notable declines for both the Nasdaq and S&P 500. The same logic runs in reverse for everyone else: when sentiment on AI cracks, it does not stay neatly inside the AI aisle.
The lesson worth sitting with is this. Geographical diversification reduces correlation in calmer markets. It does not sever it when the catalyst is a policy shock affecting the world’s largest source of corporate capital expenditure. AI-related infrastructure investment was driving nearly all observed U.S. GDP growth by late 2025, according to a Columbia Business School analysis. A growth engine that large does not stop at a border when it stalls.
Genuine diversification today means looking beyond geography to assets with structurally different drivers: dividend payers with pricing power, commodity producers, real assets. The Stoxx 600 holding up slightly better than the Nasdaq is a data point, not a strategy.