Hancock Whitney was already one of the more quietly compelling regional banks in the Southeast. Then, on November 12, 2026, it announced the largest move in its modern history: a $3.2 billion all-stock acquisition of Trustmark that would nearly double its asset base.
Why This Stock Now
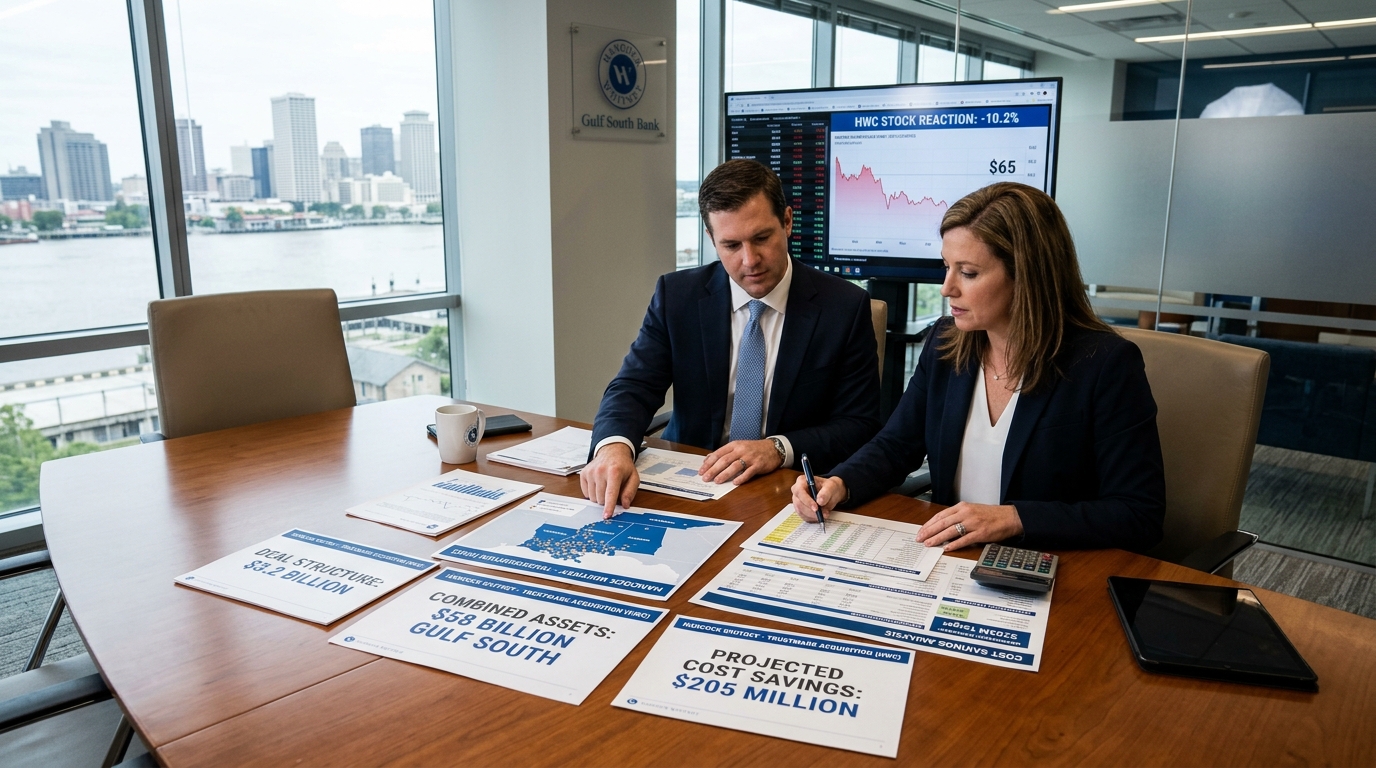
HWC shares fell 10.2% on Thursday to close at $65, following the announcement of the Trustmark deal. That reaction is worth interrogating. When a well-regarded acquirer drops that sharply on deal day, the market is usually saying one of two things: the price is too rich, or the integration risk is underappreciated. Here, both concerns are legitimate. But they may also be overstated, which is why HWC deserves a close look right now.
The Business
The combination of $39 billion-asset Hancock Whitney and $19 billion-asset Trustmark would create “the premier Gulf South bank” better positioned to compete with dominant nationwide and super-regional banks. The combined institution would have $58 billion in assets and roughly 370 branches across six Southeastern states. That footprint spans Alabama, Florida, Louisiana, Mississippi, Tennessee, and Texas, covering some of the country’s fastest-growing deposit markets.
Acquiring Trustmark enhances Hancock Whitney’s ability to fund growth in fast-growing markets like Houston and the Florida Panhandle, using deposits gathered in its slower-growth Mississippi and Alabama markets. That is a structurally attractive funding advantage, the kind that compounds quietly over years.
Why Wall Street Is Paying Attention
The deal ranks as the third-largest U.S. bank merger announced in 2026, based on seller assets, according to reporting by American Banker. Scale matters in banking right now: technology costs are rising, margin compression from funding costs is real, and smaller institutions are struggling to match the product suites of the nationals. A $58 billion bank has options a $39 billion bank simply does not.
Citi analyst Benjamin Gerlinger was constructive immediately. He wrote that the potential synergies are being overlooked and that the combination offers opportunities to deepen lower-cost deposit relationships, expand in concentrated metro growth markets, and generate cost savings beyond management’s own assumptions, given the meaningful branch overlap in Mississippi.
What’s Driving the Opportunity
The financial construction of this deal is straightforward. Management is projecting $205.5 million in annual pretax expense savings on a run-rate basis, against $250 million in pretax merger costs. That target represents cutting roughly 35% of Trustmark’s noninterest expense.
The transaction is expected to be approximately 7% accretive to Hancock Whitney’s 2028 estimated earnings per share, mildly dilutive to regulatory capital at close, and approximately 7% dilutive to tangible book value per share, with earn-back in approximately 2.8 years inclusive of merger expenses. A sub-three-year tangible book earn-back is a credible metric for a deal of this complexity.
The exchange ratio of 0.7463 Hancock Whitney shares per Trustmark share valued Trustmark at $54.02 per share, an 18.6% premium over its last close before the announcement. The deal is priced at 1.78 times tangible book value. Neither figure suggests Hancock Whitney overpaid egregiously.
What Could Go Wrong
Cost savings at this scale are never automatic. The two banks share significant branch overlap in Mississippi, which is the core synergy driver, but executing $205 million in cuts while retaining deposit relationships is an operational challenge that will take 18 to 24 months to fully materialize. The merger is expected to close late in the first quarter of 2027, subject to regulatory approvals and shareholder votes at both companies. Any regulatory friction could delay or reshape the cost savings timeline.
HWC has already crossed below its 200-day moving average, which sits at $71.04, with shares trading as low as $63.27 during Thursday’s session. Technically, the stock is in a weaker position than it was 48 hours ago, and momentum investors will stay away until the picture stabilizes. Dilution to tangible book also creates near-term pressure on valuation multiples that some institutional buyers track closely.
The Bottom Line
HWC at $65 is a different proposition than HWC at $72. The selloff creates a potential entry point for investors who believe the cost savings are real and the Gulf South deposit franchise is worth owning at a discount. The consensus analyst price target on HWC currently sits at $84.56, with the majority of covering analysts carrying buy-equivalent ratings. If the Trustmark integration proceeds on schedule and $205 million in expense reductions flows through to 2028 earnings as projected, the stock’s current valuation does not reflect that outcome. The risk is execution. The reward, if management delivers, is a Gulf South bank trading at a meaningful discount to where it should be.