September 17, 2026
A fresh dividend raise, a 20% stock slide, and a 40-year lease book put VICI at the center of income-seeking funds
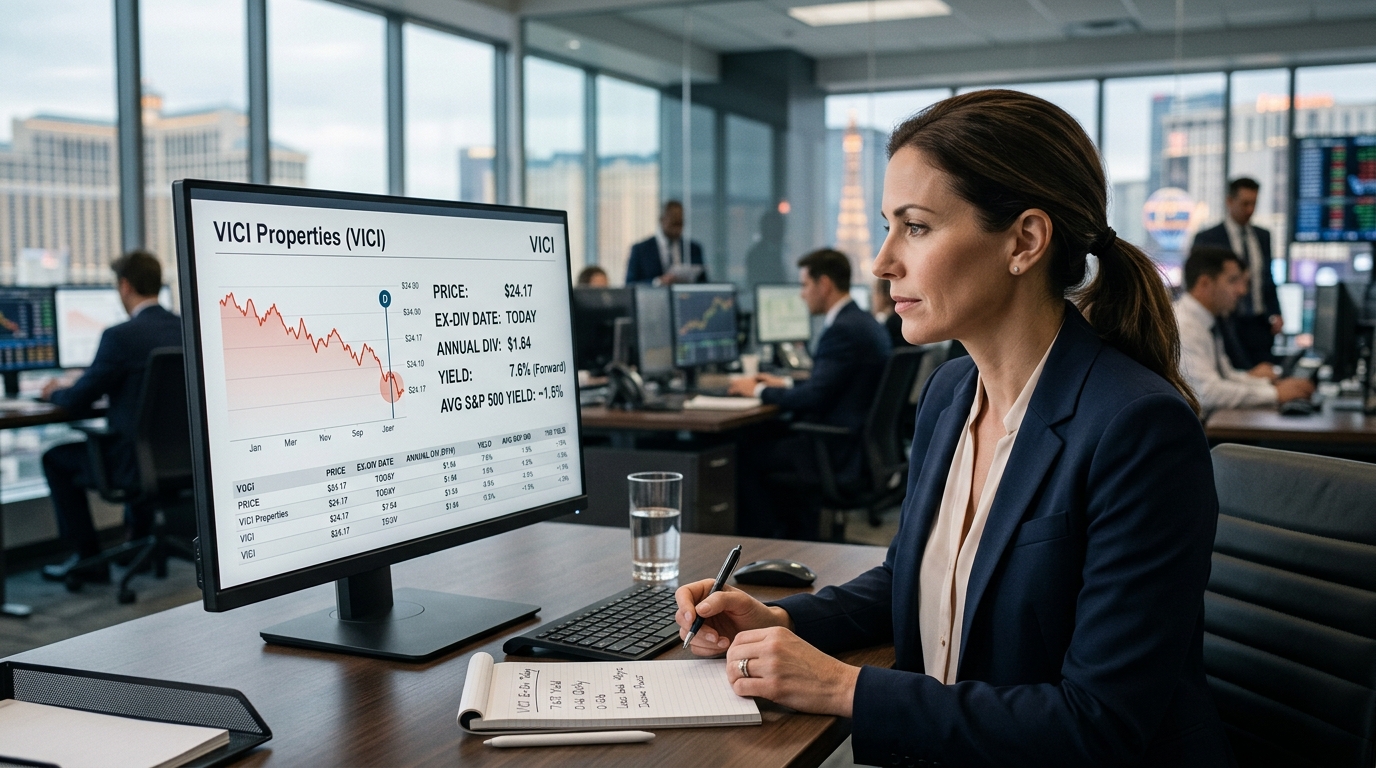
Today is VICI Properties’ ex-dividend date. Own shares before the close and you collect a quarterly payout of $0.46, the highest in the company’s history. At the current price near $24.17, that works out to a forward yield of roughly 7.6%. For context, the average S&P 500 constituent yields roughly 1% to 2%.
Elon’s $480 Trillion Currency Masterplan
He’s waited 27 years for this moment. Elon Musk just launched his biggest disruption ever, which could totally reset how millions of people access their money and even pay tax.
The yield is high partly because the stock is low. VICI has fallen approximately 20% over the past year, sitting just above its 52-week floor of $24.66, well off the $33-plus it traded at twelve months ago. That gap is where income-focused investors are doing their math.
What has not fallen is the cash flow. Second-quarter 2026 revenues came in at $1.06 billion, up 5.7% year over year, with AFFO per share rising 4.6% to $0.62. Management then raised full-year 2026 AFFO guidance to a range of $2.675 billion to $2.695 billion, or $2.45 to $2.47 per diluted share. The payout at the new $0.46 quarterly rate is expected to consume roughly 74% to 75% of midpoint AFFO, a coverage ratio that leaves room for further annual increases without straining the balance sheet.
Own Every Major AI Stock for $38. Get Paid Every Thursday.
The biggest AI stocks have been soaring and now cost hundreds of dollars a share. But there’s a single fund that owns all of them – Nvidia, CrowdStrike, Palantir, and dozens more – for just $38 a share. And it pays income every Thursday. Up to $1,051 a month.
The portfolio generating those numbers is not a conventional office or retail REIT. VICI owns 93 experiential assets across 26 states and one Canadian province, all leased under long-term triple-net agreements to operators including Caesars, MGM, and now Club Med. Tenants cover property-level expenses; VICI collects the rent. The weighted-average remaining lease term runs close to 40 years, meaning today’s income stream has a very long runway before a single lease rolls.
The company added three tenants in Q2, closing a $1.16 billion Golden Entertainment sale-leaseback, a Northfield Park lease with Clairvest, and a $75 million build-to-suit project in St. Croix with Club Med as its 16th tenant. That last deal also marks VICI’s first Caribbean asset and its first build-to-suit investment, extending the model beyond straight casino landlordship.
Inflation escalators cover about 45% of rent today and are projected to cover 87% by 2035, which is the structural detail income investors should weigh alongside the raw yield figure. A 7%-plus yield attached to leases that grow automatically with CPI is a different animal from a static-income bond.
The Fed Chair’s First Move Could Unleash the Biggest Wealth Transfer in a Generation
In sworn testimony before the U.S. Senate, the Federal Reserve’s new chair revealed a sweeping change he wants to make to the way the government operates. A change that 40-year Wall Street veteran Dr. David Eifrig warns would effectively “gaslight” regular Americans… And, if history is any precedent, could wipe out up to 40% of your wealth in the process. But Dr. Eifrig says there’s a silver lining to all this. What’s unfolding right now looks set to send one asset soaring… and his No. 1 stock up 1,000%.
The analyst community is split on timing. Morgan Stanley trimmed its target to $29 this week; Barclays rates VICI a Buy; the consensus across 25 analysts sits at roughly $32, implying roughly 34% upside from current levels. A leverage ratio of 4.9x sits below VICI’s own 5.0x to 5.5x target range, leaving room for further acquisitions without a capital raise.
The risk is real: tenant concentration and refinancing costs on $17.2 billion in total debt matter in a still-elevated rate environment. But the mechanics today are straightforward. A 7.6% yield, backed by rising AFFO, triple-net leases, and seven consecutive years of dividend growth, is what income-seeking capital is chasing into this ex-date.