September 23, 2026
Bonus Content: Nvidia’s Supply Constraint Is the Bear Case Nobody Priced
If you still haven’t downloaded Your First Trade Playbook…
…please take a few seconds and download it right now before your temporary download link expires.
Most beginners stay stuck on the sidelines for years because nobody shows them the simple steps between “interested in options” and actually placing a trade.
This playbook fixes that in one evening.
I eventually plan to charge for it, so do yourself a favor and download it now…
That way, no matter how much it costs in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Your First Trade Playbook << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of Your First Trade Playbook to your computer before I start charging for it.
Nvidia’s Supply Constraint Is the Bear Case Nobody Priced
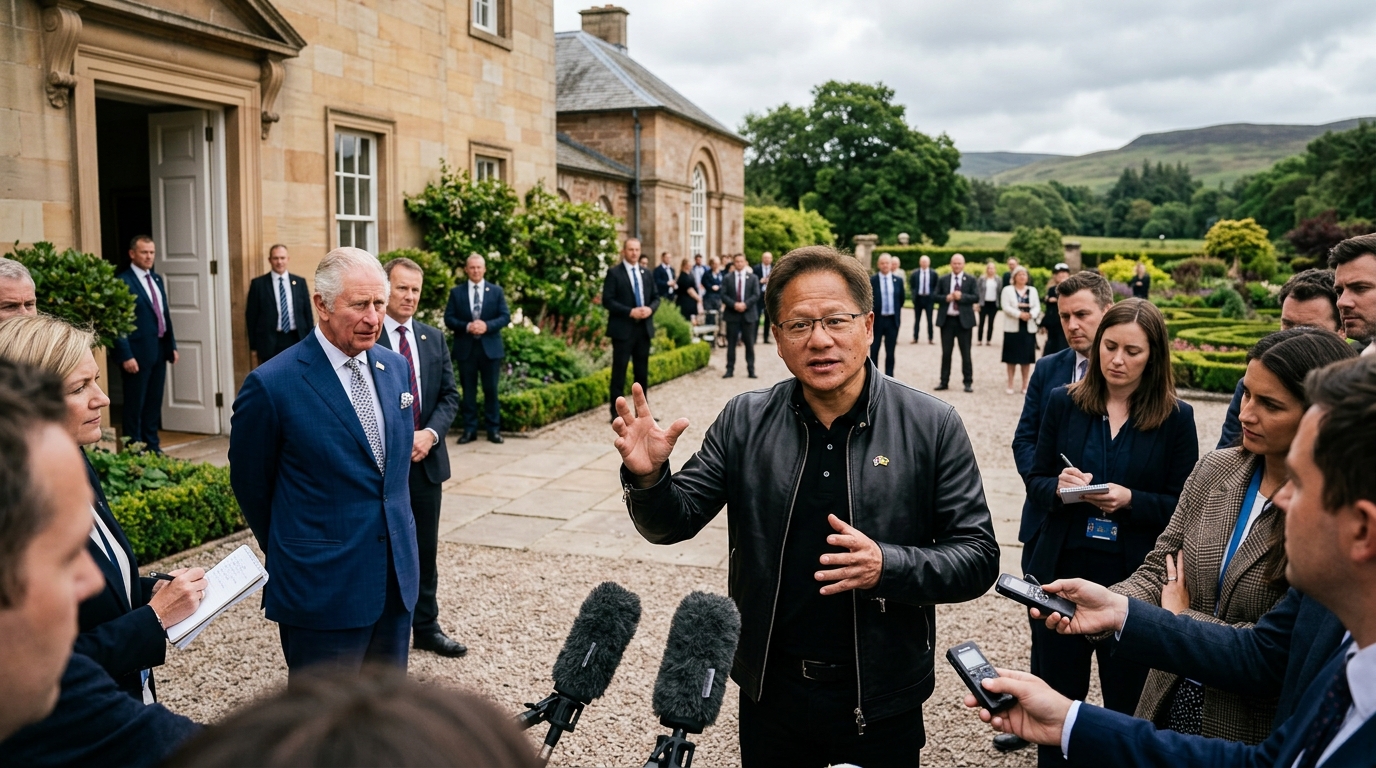
Jensen Huang stood beside King Charles III at Dumfries House in Scotland last week and told reporters something that should have moved markets hard. The Nvidia CEO forecast that the company will sell twice as many chips next year as it does this year, citing AI demand across industries and countries as the driver of continued growth. Meanwhile, the stock trades at a forward price-to-earnings ratio that implies the opposite.
Nvidia’s forward P/E sits at roughly 18. That represents a decrease of more than 30% compared with the 12-month average. For a company that, in fiscal 2026, reported $215.9 billion in total revenue, up 65% year-over-year, the disconnect between the operating results and the valuation assigned to future earnings is the central question of the week.
What the Market Is Actually Pricing In
Wall Street is not ignoring the revenue. It is questioning whether the earnings behind it will hold. Gross margin is expected to decline and bottom out in the fourth quarter of fiscal 2027 at 71% to 72%, partly because of memory prices. The margin trough lands before the volume doubling does, and the sequencing matters. A stock priced at 18 times forward earnings reflects exactly that: a business believed to be at or near peak profitability, not peak revenue.
The semiconductor index now carries a higher forward multiple than Nvidia does, inverting the relationship that held for most of the past three years. The largest AI chip company in the world is trading at a discount to the sector it built.
The Bull Case Rests on Vera Rubin
The volume commitment Huang made in Scotland goes beyond what Nvidia has formally guided. His prediction goes beyond Nvidia’s formal financial outlook and refers to the number of chips sold rather than a promise that revenue will double.
The formal guidance is already aggressive enough: on Nvidia’s August 26, 2026 earnings call, the company said its preliminary expectation is for fiscal 2028 revenue to grow approximately 70% year-over-year.
The platform carrying that growth is Vera Rubin. Nvidia says Vera Rubin began production shipments in the third quarter of fiscal 2027, with supply expected to grow over time. The platform, built around a 336-billion-transistor Rubin GPU and an 88-core Vera CPU, has been pitched as delivering 5x AI performance versus Blackwell at 10x lower cost per token. That performance curve, if it lands on schedule, makes the fiscal 2028 earnings-per-share revisions look conservative, not heroic.
The Bear Case Has a Name: Broadcom
The structural challenge is custom silicon. Hyperscalers are co-designing their own accelerators at scale, and Broadcom is the direct beneficiary. Broadcom now expects $58 billion of AI semiconductor revenue in fiscal 2026, and Hock Tan said on the company’s September 2026 earnings call that Broadcom has secured supply to double AI revenue to approximately $115 billion in 2027.
Broadcom has publicly identified key custom-AI customers that include Google, Meta, Anthropic, and OpenAI. But that trajectory does not necessarily come at Nvidia’s expense. Meta has committed to deploying millions of Blackwell and Rubin GPUs alongside its custom MTIA silicon. The ASIC displacement story assumes a cleaner substitution than the capex data supports.
Stocks to Watch
NVDA: Second-quarter revenue was $96.2 billion at a 75.0% gross margin, with third-quarter revenue guided to $108 billion, plus or minus 2%. At roughly 18 times forward earnings against roughly 70% fiscal 2028 revenue growth, the risk-reward is asymmetric if margins recover above their trough.
AVGO: The ASIC displacement trade. Broadcom has said it has line of sight for AI semiconductor revenue to approximately double to $230 billion in fiscal 2028. Tan said custom AI deployment is entering its next phase, with the company working with six key customers on their chips, including Google, Meta, Anthropic, and OpenAI.
TSM: TSMC manufactures Nvidia’s Vera Rubin chips and sits at the supply bottleneck in every scenario.
ARM: Arm participates in Nvidia’s Vera CPU, hyperscaler processor designs, and custom silicon simultaneously. It is structurally positioned to benefit regardless of which architecture takes share over the next cycle.
The Cheat Sheet
- Top Market Theme: Nvidia’s valuation discount to its own sector reflects a margin trough, not a demand trough, and the two should not be priced identically.
- Stock to Watch: NVDA. Huang’s doubling forecast is the most explicit volume commitment the company has made, and it trades at 18x forward on roughly 70% fiscal 2028 growth.
- Sector to Watch: Semiconductors. The SOX index carries a higher forward multiple than Nvidia, a rare inversion that resolves one of two ways.
- Biggest Risk: The margin trough arrives before the unit doubling does. If memory prices stay elevated longer than expected, the earnings recovery that justifies the bull case gets pushed out.
- One Thing to Remember: On Nvidia’s August 26, 2026 earnings call, Huang said Nvidia has “a lot greater visibility now” into its supply chain than it did a year ago. Supply-constrained guidance is not bearish. It means demand exceeds what can be shipped.