September 24, 2026
Bonus Content: SLB’s Deepwater AI Bet Is Starting to Pay. The Stock Hasn’t Caught Up.
Dear Reader,
I believe Elon Musk is about to launch a new device that could kill the iPhone.
It’s rumored to be thinner… have longer battery life… and sell for much cheaper…
It could also be usable worldwide without cell towers… and run on one of the most powerful AI-based platforms in existence.
I call it “Starphone” (see why here)…
And I’m convinced this new device could quickly unlock some of the biggest Elon gains you’ve ever seen.
This marks the third major mobile phone prediction of my career…
In 2004, I told Congress the smartphone was about to transform the world – years before the iPhone was first announced.
Had you bought $1,500 worth of Apple shares back then, they’d now be worth million.
A few years later, as a hedge fund trader, I told Steve Cohen at SAC Capital that Apple wouldn’t sell 1.2 million phones like every other analyst was predicting… but 1 billion phones.
Both predictions came true.
Now, I’m sharing all the evidence proving why I believe Elon is working on a new device…
One that could not only change your life and our society… but potentially make you 50 times your money as it hits shelves.
Just know that this story is already starting to hit the mainstream.
Just last week, the FCC gave Elon a major green light to move ahead with his mobile plans.
That means your window to move your money is NOW – before the official debut.
Get the full story and see all the government filings and deals here.
Regards,
Josh Baylin
Frmr. Bloomberg Reporter
Frmr. SAC Capital
Senior Tech Expert, Stansberry Research
P.S. I’m also sharing the name and ticker of a stock at the very heart of this huge story. It’s 100% free, on this page here.
SLB’s Deepwater AI Bet Is Starting to Pay. The Stock Hasn’t Caught Up.
SLB trades near $51 on the NYSE right now. Roughly 29 to 30 analysts cover the stock, and the average price target is about $62.34, implying roughly 20% upside from current levels. That gap has a specific cause: the market still prices SLB primarily as an oilfield services company. The company’s own results are quietly telling a different story.
Market Snapshot
Second-quarter revenue came in at $8.97 billion, up 3% sequentially and 5% year over year. That top-line number looks steady, but it understates the composition shift underneath. Excluding ChampionX, Digital revenue grew 12% year over year in Q2 2026. Annualized recurring revenue for the Digital division hit $1.04 billion as of June 30, 2026, up 15% year over year, giving the segment a subscription-like durability that traditional drilling services cannot match.
Stocks in Focus: SLB
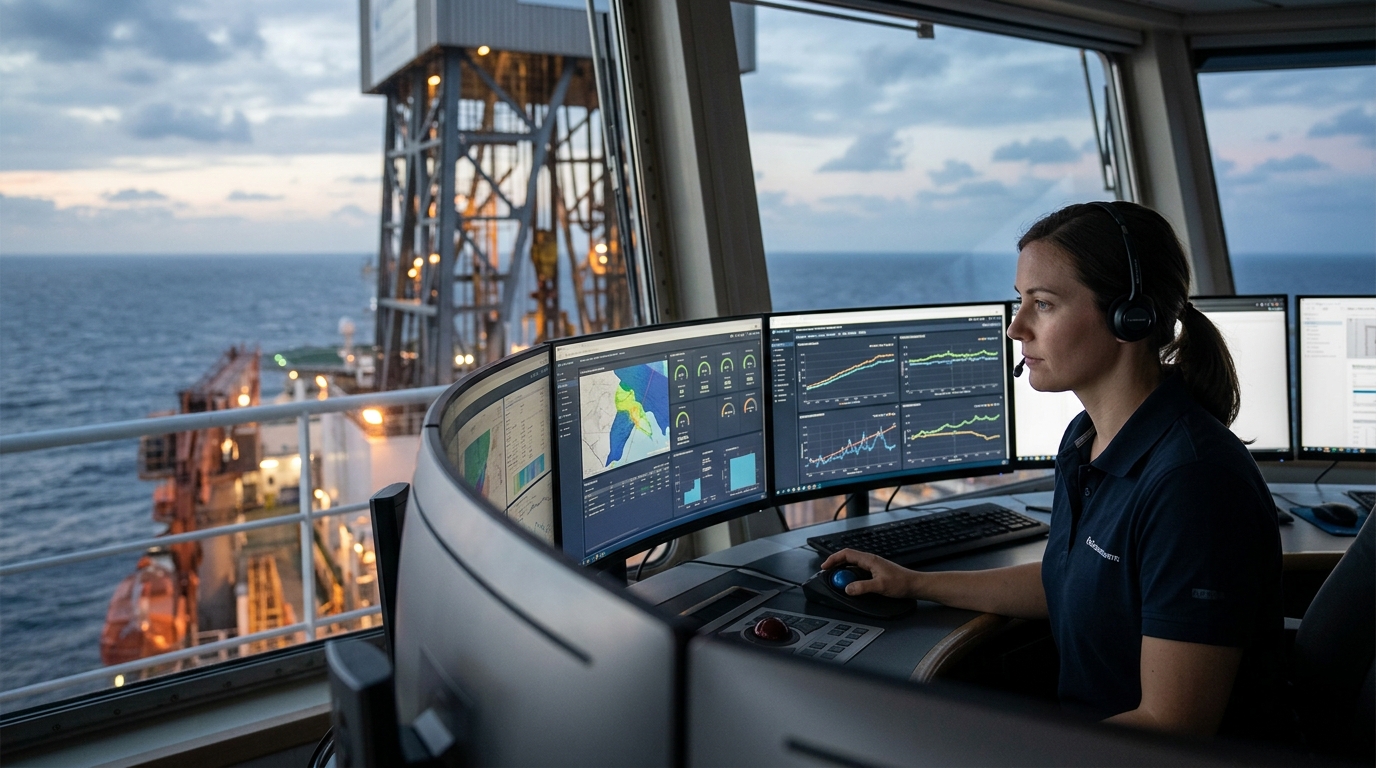
The angle most traders are missing is where that digital revenue actually gets deployed. SLB and NVIDIA are building an “AI Factory for Energy,” a reference environment powered by domain-specific generative AI models and industrial-scale agentic AI running within SLB’s digital platforms. The two companies plan to optimize the processing of large datasets and AI models across SLB digital platforms using NVIDIA AI infrastructure, targeting higher performance benchmarks for energy applications. This is not a marketing arrangement. SLB operates a 3.1 million square-foot manufacturing facility in Louisiana dedicated to modular data center production.
The deepwater contracts are stacking alongside the digital build. China National Offshore Oil Corporation awarded SLB OneSubsea a multiwell integrated EPC contract covering 20 wells for the deepwater Kaiping 18-1 field in the South China Sea. Separately, SLB holds a major drilling contract to oversee 18 ultra-deepwater wells at Woodside’s Trion development off the coast of Mexico, using AI-enabled drilling capabilities to improve operational efficiency and well quality. Both projects run through SLB’s Performance Live digital service delivery centers, meaning software revenue follows the rig work.
Sector Watch: Offshore Services
SLB says third-party reports point to final investment decisions for long-cycle projects rising about 30% year over year in 2026, led by deepwater activity and higher exploration spending. Management also expects higher exploration spending and upstream capex growth across deepwater markets during the second half of 2026, led by Africa. A more meaningful impact is expected in 2027, with growth extending to Latin America, the Mediterranean and Asia. Halliburton is the nearest comparable, but SLB’s software recurring revenue base gives it a structurally different margin profile heading into that spending wave.
Technical Radar
SLB closed at $51.12 on September 18, 2026, after a sharp one-week pullback. That drop came during a broad energy selloff and puts the stock near support that held through the Q1 Middle East disruption. Watch $48 as the level that would force reconsideration of the near-term thesis. The Q3 earnings call is the next hard catalyst and is typically scheduled in mid-October, with many market calendars currently pointing to around October 16, 2026 (not yet confirmed by the company): if management confirms deepwater contract ramp and Digital annualized recurring revenue continues its 15% growth trajectory, the gap to the $62 consensus target narrows fast.
Risk Radar
The bear case rests on sluggish enterprise uptake, since energy buyers have long procurement cycles and little patience for unproven ROI. The Middle East remains the primary drag. Q1 saw SLB begin demobilizing operations in a few countries in the region, and that pressure has not fully resolved. Rising R&D and digital transformation costs could compress margins if revenue growth does not keep pace.
The Cheat Sheet
- Top Theme: SLB’s digital and deepwater combination is producing durable recurring revenue that oilfield services multiples do not yet reflect.
- Stock to Watch: SLB. The ~$51 price with a ~$62 consensus target and accelerating Digital ARR is the tension traders need to resolve before Q3 results.
- Sector to Watch: Deepwater offshore services, where final investment decision volume is rising about 30% in 2026 and multi-year contracts are beginning to flow.
- Biggest Risk: A renewed Middle East disruption or oil price collapse below $70 that triggers upstream capex cuts and delays those final investment decisions.
- Biggest Opportunity: The bull case is not simply that SLB sells more software. It is that SLB becomes the standardized AI operating architecture for energy, capturing economics across subscriptions, deployment, AI services and infrastructure manufacturing.
- One Thing to Remember: SLB’s deepwater AI contracts are structured to generate software revenue every time a well is drilled. That recurring layer is what separates this from a pure commodity services trade.