Dear Reader,
Every major tech company on Earth is racing to build AI.
They’re all dependent on the same chips… the same power grid… the same infrastructure…
But when Elon is done with his just-revealed master plan – buried inside the SpaceX S-1…
The AI economy you think you understand won’t exist anymore.
You could wake up tomorrow and discover your money is suddenly in all the wrong places.
I’ve spent 15 years doing this kind of forensic research and my institutional reasearch is followed by the world’s biggest money managers, including Goldman Sachs, JPMorgan Chase, BlackRock, and Fidelity…
When I saw what was buried inside the SpaceX S-1, I flew to Starbase to see it for myself.
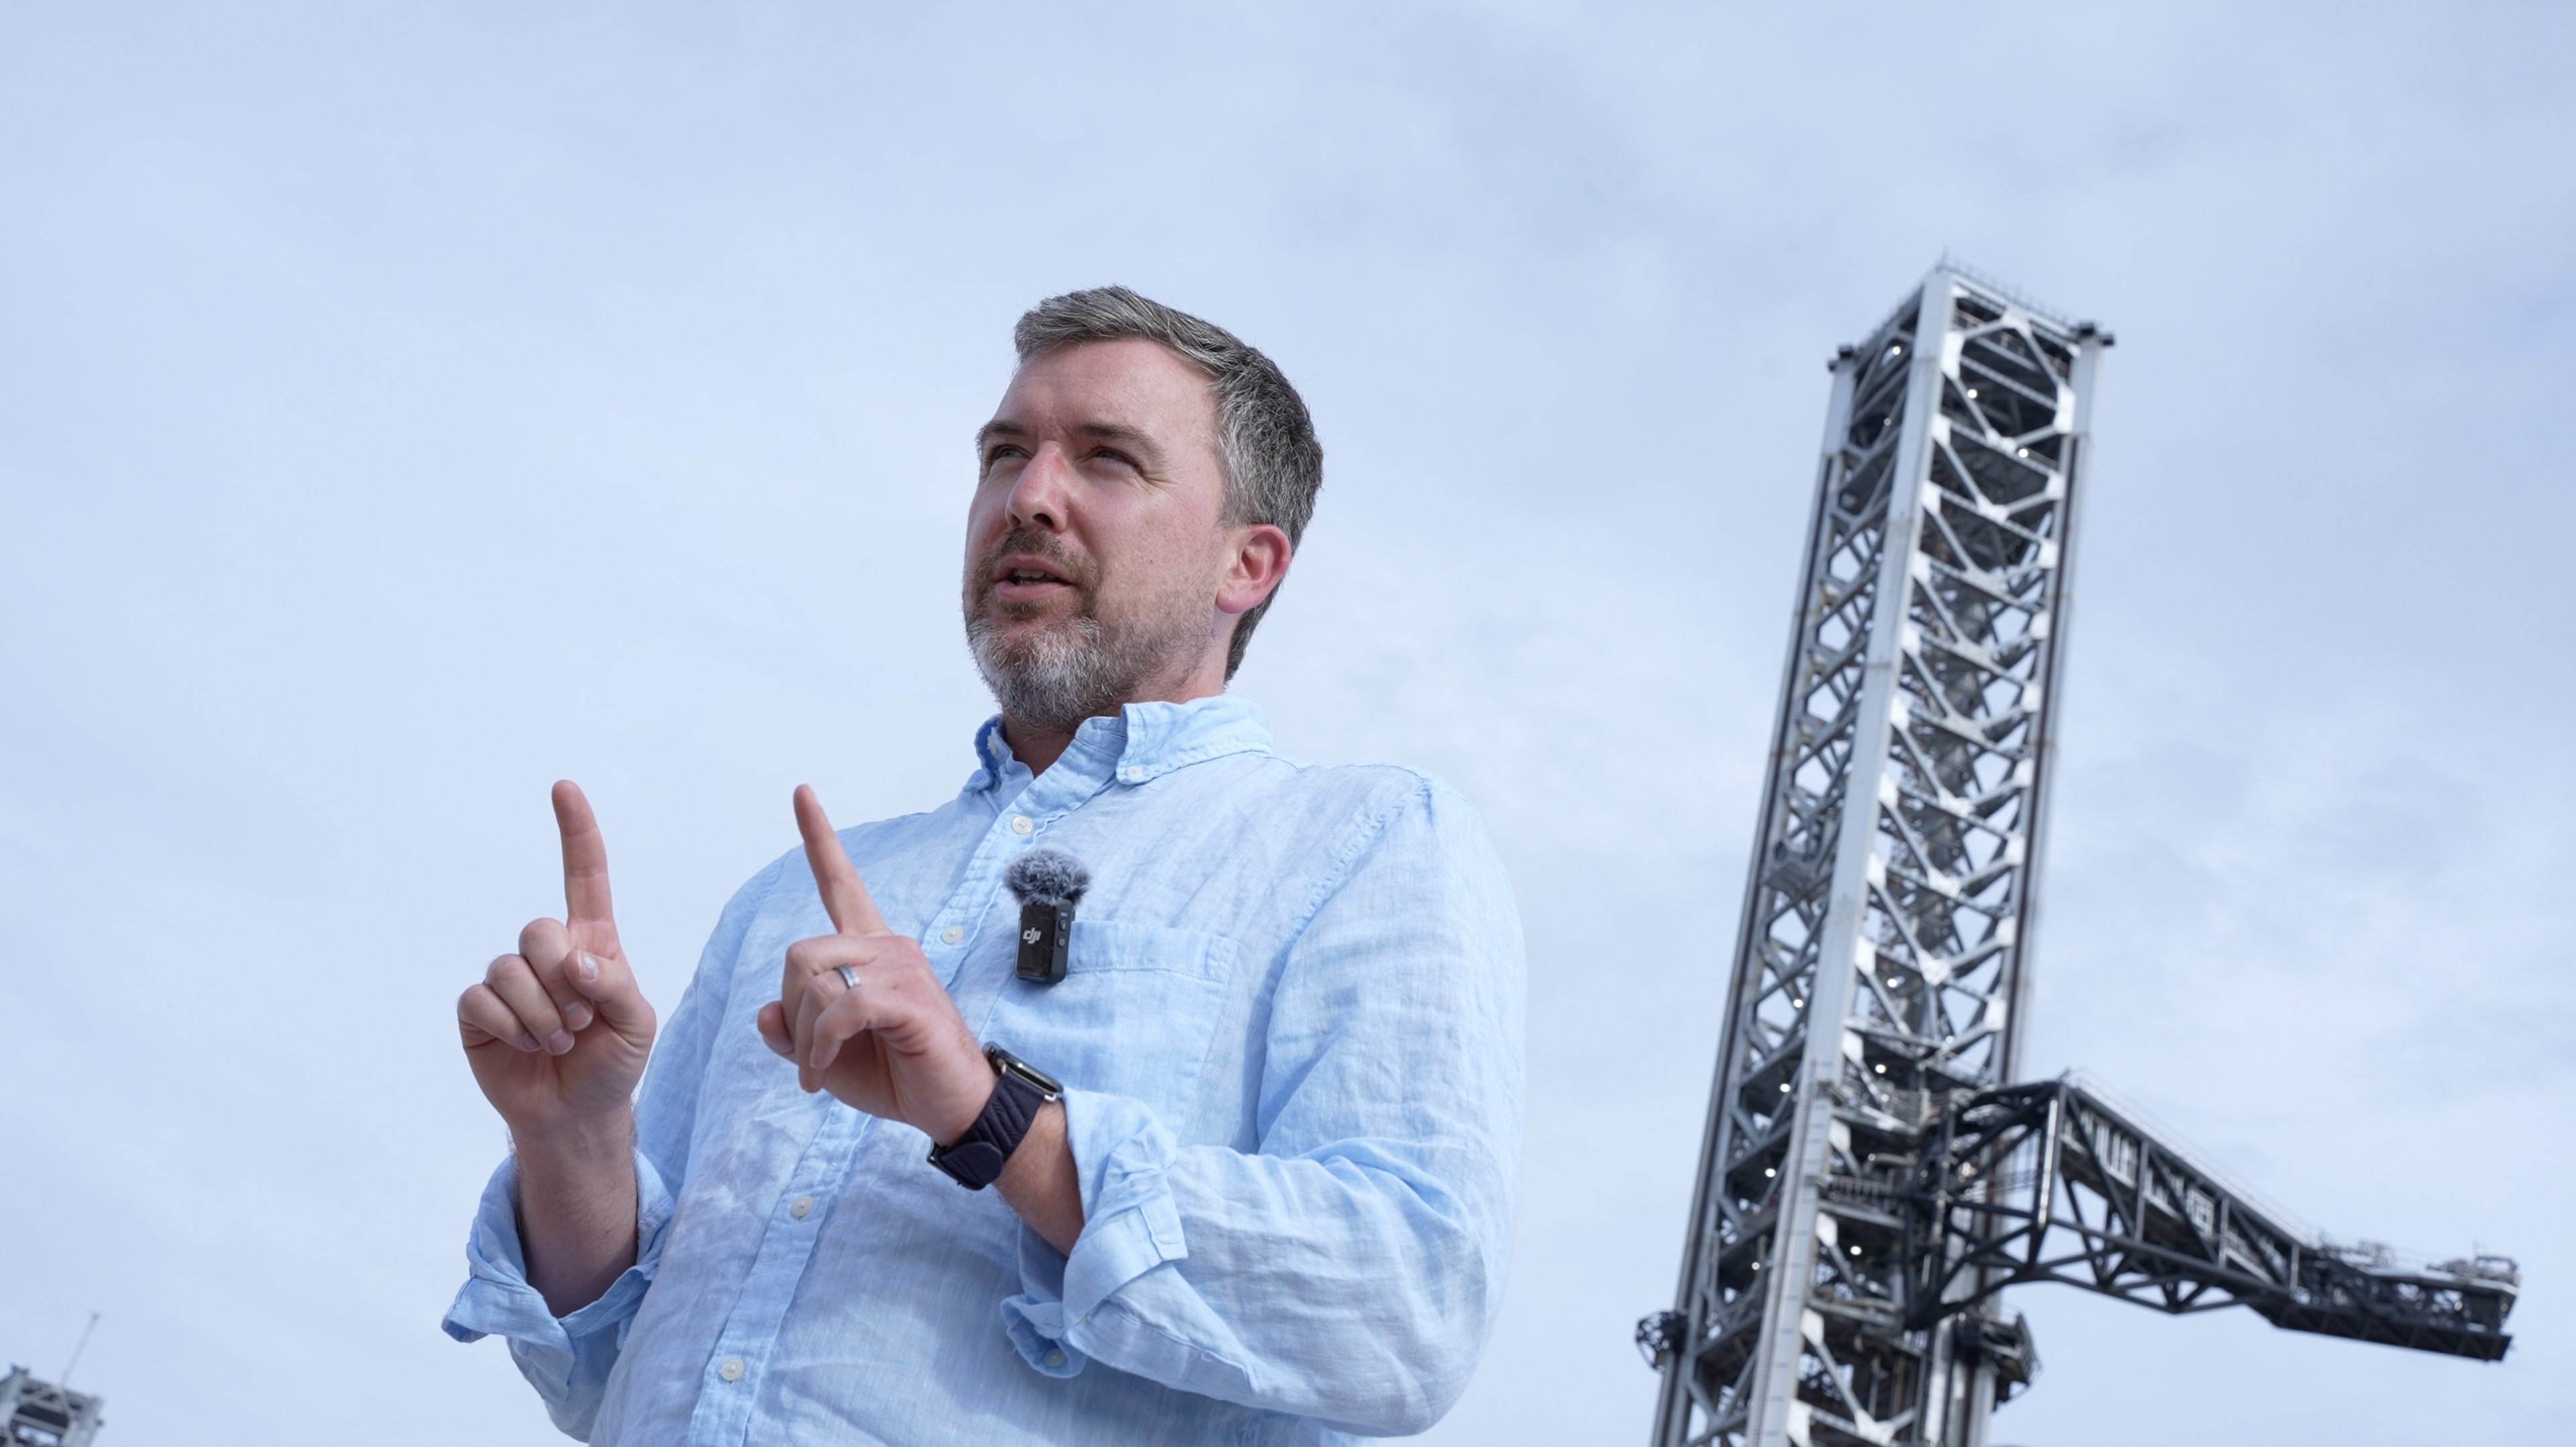
In my new briefing, I’ll show you exactly what I believe Elon is building – and the single best stock to own because of it (not Tesla or SpaceX)…
Better yet, I’m giving away the name and ticker completely free, no credit card required.
Click here to get the full story and my No. 1 recommendation, free.
Regards,
Rob Spivey
Managing Director, Altimetry
P&C Insurance Is Quietly Running a Standout Profit Cycle
Market Snapshot
Financials broadly held their ground Friday, but the action inside the sector tells a sharper story. Property/casualty insurers are posting numbers that few corners of the equity market can match right now, yet the stocks rarely make headlines. That gap between performance and attention is exactly where traders should be looking.
The U.S. P&C industry posted a net underwriting gain of $31.7 billion in the first half of 2026, up from $11.6 billion a year earlier, according to a Verisk and American Property Casualty Insurance Association (APCIA) report. Net income after taxes jumped 53% to $77.8 billion, compared with $50.9 billion in the first half of 2025. The industry’s combined ratio improved to 92.7, compared with 96.5 a year earlier, marking one of the strongest half-year underwriting performances in recent history.
Stocks in Focus
Chubb is the clearest beneficiary of this environment. The company delivered a P&C combined ratio of 83.8% in Q2 2026, and Reuters reported it improved from 85.6% a year earlier, even as it deliberately shed large account and E&S property business in a softening market. Adjusted net investment income reached a record $1.88 billion, up 11.4%, with pre-tax net investment income at $1.76 billion, up 12.3%.
Travelers is running a similarly tight book. Net investment income rose 14% to $1.07 billion pre-tax, driven by the long-term fixed income portfolio benefiting from a higher yield and growth in average invested assets. Its consolidated combined ratio came in at 83.6%. Both carriers have highlighted reinvestment rates running above their existing portfolio book yields, a mechanical tailwind to investment income that persists for years, not quarters.
Sector Watch
The macro engine powering these results is the float. P&C insurers collect premiums, invest them in high-quality fixed income, and pay claims later. With treasury yields elevated, every dollar of that float generates more than it did two years ago. That compounding is not a quarterly event. It builds.
At the same time, the underwriting cycle is turning. The Guy Carpenter U.S. Property Catastrophe Rate-on-Line Index fell 12% at the January 2026 reinsurance renewals, as broad market softening resulted in lower-priced protection for ceding companies. After April and mid-year renewals, the Guy Carpenter Global Property Catastrophe Rate-on-Line Index is down 16% for 2026 year to date. For carriers willing to walk away from underpriced risk, the discipline exercised now is precisely what protects margins two and three years out.
Catalyst Calendar
- Q3 earnings season (mid-October): Combined ratios and investment income will confirm whether the first-half momentum held through hurricane season.
- Fed speakers this week: Any shift in tone around rate cuts directly affects float income projections for 2027.
- Casualty reserve disclosures: Watch for any adverse development in commercial auto and umbrella lines at Q3 reporting.
Technical Radar
Chubb and Travelers have both held above their 50-day moving averages through recent market turbulence, a sign of relative strength worth tracking. The financial sector rotation into defensives over the past two weeks has lifted P&C names disproportionately. A sustained close below recent support in either name would signal the defensive bid is fading.
Risk Radar
The headline numbers are clean. The fault line is casualty. Casualty lines such as excess liability, umbrella, and commercial auto have remained under pressure from increased claim severity, nuclear verdicts, and medical costs. In 2024, Marathon Strategies data cited in a Gallagher report showed 135 nuclear verdicts in the U.S., with a median verdict around $51 million. That median has roughly doubled from around $21 million in 2020. Carriers with meaningful casualty exposure may carry reserve risk that headline combined ratios do not fully reflect.
Policyholders’ surplus increased to about $1.3 trillion in the first half of 2026, from $1.13 trillion at midyear 2025, according to reporting on the Verisk/APCIA update. That capital buffer limits panic selling around a bad hurricane quarter, but it does not neutralize a surprise casualty reserve charge.
The Cheat Sheet
- Top Market Theme: P&C insurers are running a two-source income model, underwriting gains plus record float income, at the same moment much of the broader market is pricing in uncertainty.
- Stock to Watch: Chubb (CB). A combined ratio well below the industry, record investment income, and management actively pulling back from softening lines before margins compress.
- Sector to Watch: Property/casualty insurance broadly. The defensive rotation is real, and the fundamentals justify it.
- Biggest Risk: Casualty reserve deterioration. Commercial auto and umbrella remain exposed to social inflation and nuclear verdict severity that combined ratios can obscure until it is too late.
- Biggest Opportunity: Carriers running sub-90 combined ratios with investment income still growing into higher reinvestment rates. They are, in effect, getting paid from two directions while the rest of the market waits for clarity.
- One Thing to Remember: The soft property market is not a problem yet for disciplined underwriters. It becomes one only if they chase volume to replace the premium they walked away from.