October 10, 2026
Bonus Content: China’s Golden Week Drew Record Crowds. Wallets Barely Opened.
Dear Reader,
Recently, we sat down with tech visionary, Matt McCall, to talk about the Anthropic IPO.
And what he said took us by surprise.
Matt told us, “Most people are going to wait for Anthropic to go public and then buy as many shares as possible. But I think that’s a huge mistake.”
Because there’s ANOTHER stock, linked to Anthropic you can buy right now… that could double or triple in the years ahead.
And he’s so confident… he gave away its name and ticker.
Watch here to find out what he’s talking about – free >>>
Yours in smart speculation,
Stephen Prior, Publisher
Monument Traders Alliance
China’s Golden Week Drew Record Crowds. Wallets Barely Opened.
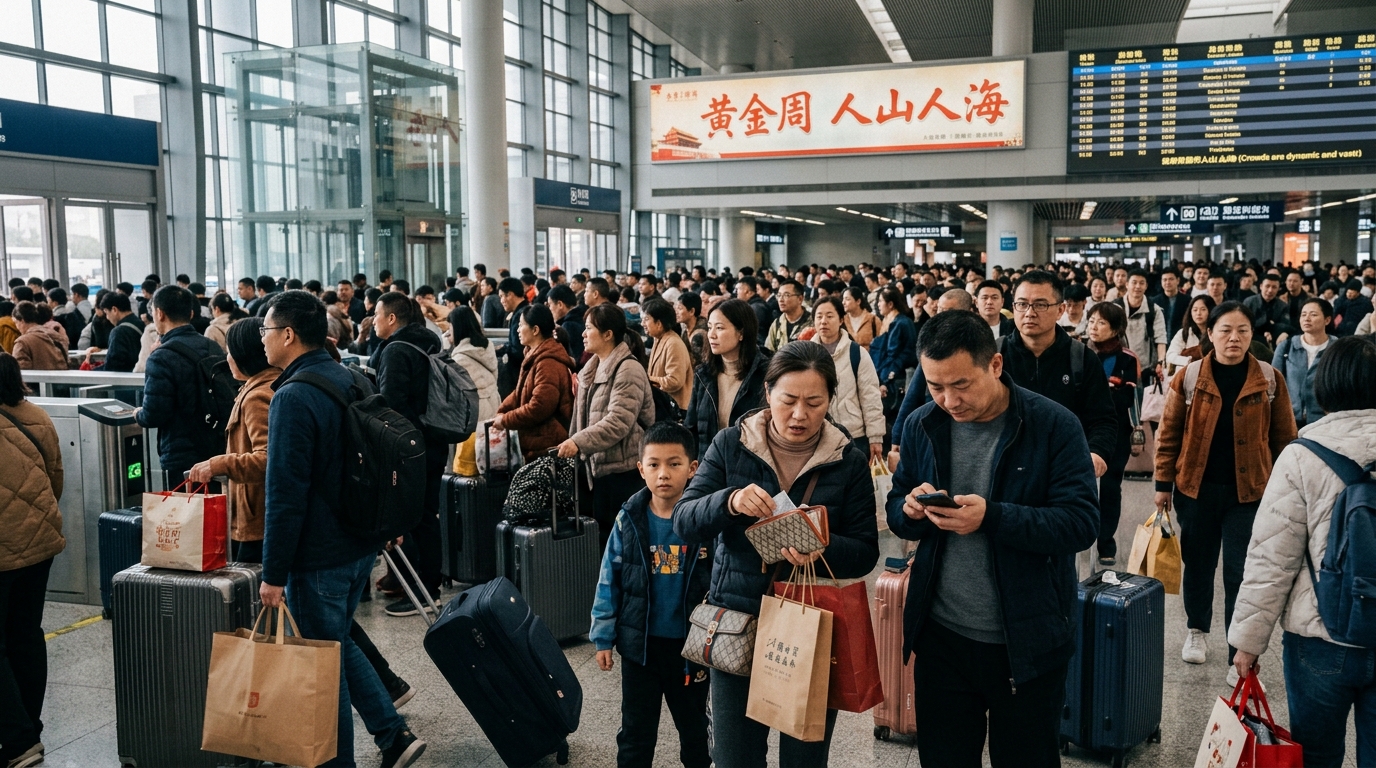
China came back from Golden Week with headline numbers that looked impressive until you divided them out. Chinese travellers’ average spending per trip fell to a four-year low during this year’s seven-day holiday, dashing hopes that strong travel demand would spur a broader recovery in consumer spending. Average spending per domestic trip fell 1.9% to 893.92 yuan from 911.04 yuan a year earlier. That was the lowest since 2022, when spending collapsed to 680.60 yuan during the most severe period of China’s COVID-19 restrictions.
Volume was not the problem. The Ministry of Culture and Tourism counted 826 million domestic trips, and the State Administration of Taxation reported that daily service-sector sales rose 19.5% year on year, with tourism and entertainment up 23.6% and dining up 9%. People moved. They just spent less when they arrived.
“This Gold Firm’s Stated Policy: Return Free Cash Flow to Owners”
Very few publicly traded securities are run with the owners in mind. Over the past 50+ years, yields have cratered. But today, one unique gold firm is doing something differently. Backed by the world’s best gold mine, this firm has one policy: to return all free cash flow to owners. It’s one of the highest yielding securities in the market. Some early investors are already seeing 10% annual yields.
The breakdown across categories tells traders where the pain lands. The National Day holiday box office brought in about 1.17 billion yuan, down 36% from a year earlier, with viewership off 18 million tickets despite a five-year-low average ticket price of 36.4 yuan. Box-office revenue is now well below its pre-pandemic peak, which is a structural shift, not a one-week anomaly.
Hainan duty-free avoided an outright collapse but offered no comfort for China Tourism Group Duty Free bulls. Haikou customs supervised offshore duty-free purchases worth 855 million yuan during the seven-day holiday, involving 123,000 shopping visits and 696,800 items. Footfall at CDFG’s Hainan stores rose 21%, yet the revenue per visit implied by those figures is thin.
The outbound story is the inverse. More than half of outbound overseas flight bookings made through Trip.com Group were for departures before October 1, with average trip lengths exceeding nine days; bookings for foreign hotel stays of at least seven nights rose 123% from a year earlier, while multi-destination itineraries climbed 84%. Consumers willing to travel farther on a tighter per-night budget are good for TCOM’s transaction volume but a headwind for the domestic spending names luxury investors track.
The outbound surge in bookings does not automatically translate into revenue for carriers serving those routes. Airlines chasing China outbound demand have faced persistent structural barriers between booking volume and realised yield.
A senior analyst at Forthright Securities described Chinese consumers as having a “strong willingness to spend, but weak confidence,” arguing that “the key constraint is not a lack of desire to consume, but uncertainty over income and employment prospects.” A prolonged property downturn, sluggish wage growth, and a soft job market have weighed on household sentiment for years.
That backdrop is exactly why Wednesday matters. China’s September CPI report is due Wednesday, October 14, at 09:30 Beijing time, when the National Bureau of Statistics publishes it alongside PPI. The previous reading, for August, was 0.8% year on year. Analysts at Lundgreen’s Investor Insights expect the September figure to come in close to 1%, while they expect PPI to lift to 4.5% year on year in September from 3.8% in August. A CPI print above 1% would ease near-term pressure for additional stimulus; anything flat or softer increases it.
The CPI print will also shape PBOC liquidity decisions in the weeks that follow. China’s central bank has historically calibrated policy-loan injections around the balance between growth support and pre-existing liquidity conditions.
For traders, the positioning question is which side of the consumer divide to sit on. LVMH reported sales in Asia excluding Japan were down 6% in Q2 2026; Kering said Asia-Pacific was down 1% in Q2. Golden Week data does nothing to accelerate the China recovery thesis either group has been waiting for. LVMH stock has retreated about 30% year to date through late August, with first-half revenue and operating profit under pressure from cooling luxury demand, especially in China.
On the ETF side, KWEB is down roughly 28% year to date as a pure-play Chinese tech and internet vehicle, while FXI, which offers broader large-cap exposure, is down around 11% year to date. Both have seen heavy AUM outflows over the past six months. With mainland markets back open and September CPI due in four days, the market for both names will hinge on whether Wednesday’s number offers any evidence that the consumer is stabilising. The Golden Week data argues it has not.
What to Watch
- Wednesday, Oct 14: China September CPI and PPI. Consensus not yet set; August CPI was 0.8% year on year. A move toward or above 1% lifts Chinese equities; a miss weighs on FXI and KWEB at the open.
- LVMH and Kering: Q2 was still soft in Asia, and the weakest holiday spending per head since 2022 keeps pressure on both names heading into Q3 earnings season.
- TCOM: Outbound volume surge and longer average trip lengths support booking revenue even as domestic spending softens. Watch whether management commentary on Q3 monetisation rates changes.
- China Tourism Group Duty Free: Hainan traffic was up but average basket size is the key number to track. Any analyst note revising revenue-per-visitor estimates lower is the tell.