October 20, 2026
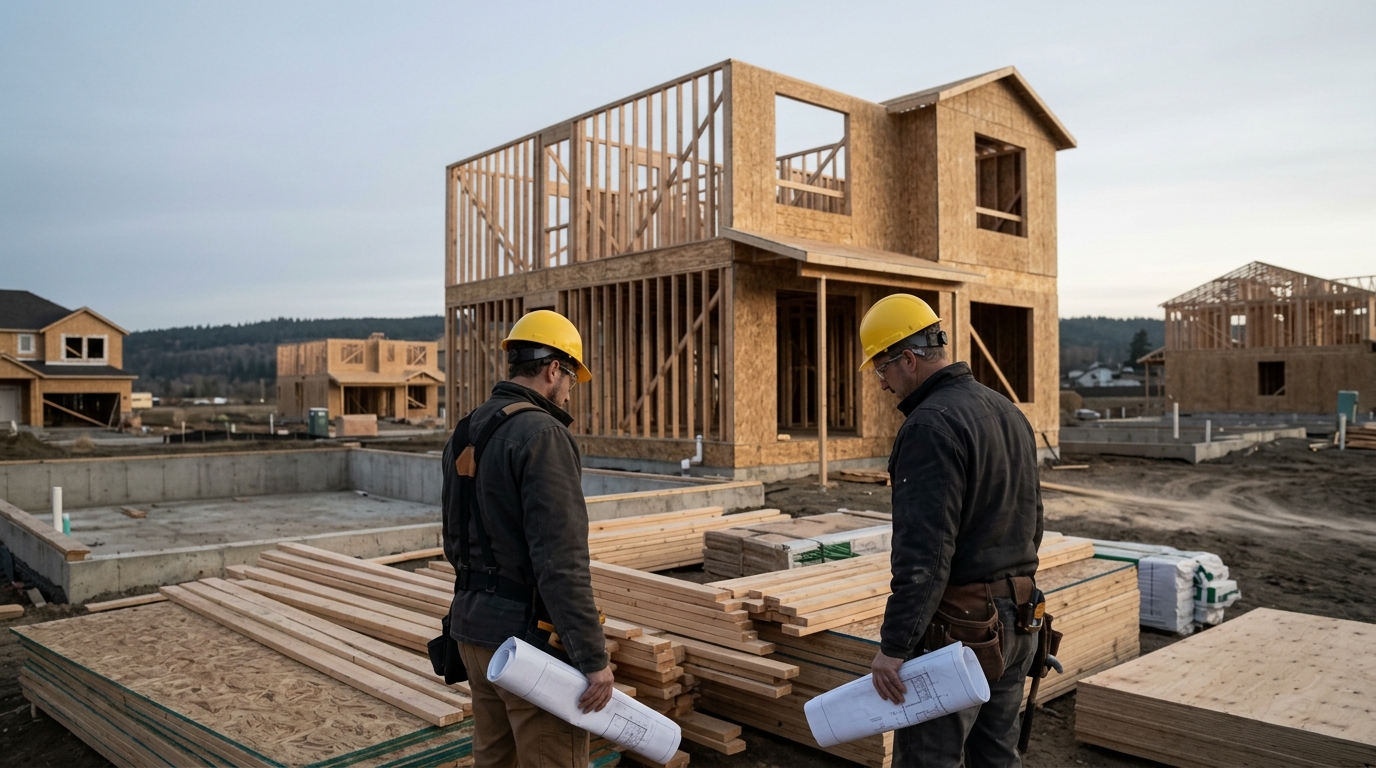
Bonus Content: Builder Confidence Hit a 14-Year Low. September Starts Are the Verdict.
Jeff Brown is the former tech executive who called the rise of Bitcoin, Tesla, and Nvidia years in advance. He’s now predicting Elon Musk is about to open a new wealth window by October 30. Click here to see the details or read more below because the last three times this window opened, those who acted had a chance to walk away with generational wealth.
Dear Reader,
This Cybercab you see in this footage is taking me to Elon Musk’s new project…
Which he called “the most epic AI project in history.”
This is so big that I believe it will open a brand-new “generational wealth window…”
And whenever Elon opens one of those windows, people get rich.
He opened his first wealth window in the late 1990s…
With PayPal and its innovative digital payment technology.
An early investor was able to turn a tiny stake of $1,600 into $3.8 million…
Elon opened his second window with Tesla and its self-driving electric cars…
Anyone who invested just $5,000 at the IPO…
Would be sitting on more than $1.1 million today.
He opened his third window with SpaceX and its revolutionary reusable rockets…
Which gave early investors a chance to turn a single $100 bill into more than $6 million.
And now, I believe he’s about to open his fourth and perhaps last wealth window by the end of this month.
Click here to see the details…
Because it all begins with this project that I’m about to show you.
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
Builder Confidence Hit a 14-Year Low. September Starts Are the Verdict.
The housing market has rarely looked this fragile heading into a construction data release. Monday’s NAHB/Wells Fargo Housing Market Index landed at 29, three points below September and the weakest reading since June 2012, missing the Bloomberg median estimate of 31. This morning at 8:30 ET, the Census Bureau publishes September housing starts and permits, the first hard construction count since the rate environment deteriorated sharply.
Market Snapshot
Homebuilder stocks are under compounding pressure. Lennar (LEN) remains down roughly 25% year-to-date despite a brief bounce on October 15 when Treasury yields pulled back sharply. D.R. Horton (DHI) is trading near $135, inside a 52-week range of $130.40 to $170.79, with analysts at Barclays, Citi, and Truist having lowered price targets in recent weeks. The iShares U.S. Home Construction ETF (ITB) is down approximately 13% in 2026. That context matters because DHI reports fiscal fourth-quarter earnings on October 29, making today’s starts number the last major macro input before that release.
Stocks in Focus
- D.R. Horton (DHI): Most exposed to the sentiment deterioration given its entry-level focus. Multiple analysts have cut targets. October 29 earnings are the near-term catalyst, and a weak starts number today tightens the screws heading in.
- Lennar (LEN): Down roughly 25% YTD. A starts number well below 1.275 million would put fresh pressure on a stock already testing investor patience.
- PulteGroup (PHM): Fell 2.33% on October 19 alongside the NAHB release. Watch for whether the Midwest’s relative strength, the only region where single-family permits rose year to date, offers any cushion for PHM’s geographic mix.
- Builders FirstSource (BLDR) and Home Depot (HD): Material suppliers face a second-order hit. Building material and supplies dealer prices were up 13.6% year over year in September, squeezing demand from both builders and renovators.
What the NAHB Data Is Actually Saying
The sub-components are worse: the prospective buyer traffic gauge fell five points to 18, the lowest reading since April 2020, after holding at 23 in September, August and July.
Price cuts are accelerating. The share of builders reducing prices rose to 43% in October, up from 38% in September and 35% in August. The average cut held at 6%. Meanwhile, 65% of builders reported using sales incentives. When price cuts and incentive usage are both at cycle extremes simultaneously, margin compression is not a future risk, it is already embedded.
The Starts Number and What to Watch
August starts came in at 1,275,000 seasonally adjusted annual rate. The September consensus sits near 1.31 million. A print below August’s 1.275 million would mark a fresh deterioration and likely send homebuilder stocks lower at the open. A number above 1.31 million would offer temporary relief, but given that Fannie Mae just raised its 2027 mortgage rate forecast to 7.5% from 6.7%, any bounce should be read carefully. Fannie Mae now sees rates at 7.4% for the fourth quarter of 2026 and 7.5% through all four quarters of 2027, a forecast that, if accurate, leaves the demand side of the equation structurally impaired.
Sector Watch
Homebuilding is the weakest sector story in the market right now. The West posted the softest regional HMI at 26, the South fell to 30, and the Midwest at 40 is the only region showing relative resilience, supported by a 2.9% year-to-date gain in single-family permits. Capital is not flowing into this group, it is sitting on the sideline waiting for a credible rate signal.
The Midwest’s relative resilience is the exception, not the rule, and it depends entirely on whether rates stabilize. The 10-year Treasury yield near 5% and its direct transmission into 30-year mortgage rates is the macro mechanism that determines whether any regional cushion holds.
Risk Radar
The key risk today is a starts figure that confirms the NAHB’s distress rather than contradicting it. Starts below 1.2 million would be a six-year-low territory signal. Watch permitting data alongside starts, permits are the forward indicator, and August permits were at a 1.394 million seasonally adjusted annual rate. A significant drop there would signal that builders are pulling back before they even break ground.
The Cheat Sheet
- Top Market Theme: Builder sentiment at a 14-year low collides with the September construction data at 8:30, the number that frames the housing trade for the rest of October.
- Stock to Watch: DHI. Earnings arrive October 29, and today’s starts print is the final macro read before the quarter is scored.
- Sector to Watch: Homebuilding. Every data point released this week lands directly on LEN, DHI, PHM, and their supply-chain partners.
- Biggest Risk: A starts miss below 1.275 million that confirms builder sentiment is now translating into fewer physical groundbreakings, not just weaker surveys.
- Biggest Opportunity: A starts beat paired with stable permits could trigger a short-covering rally in oversold homebuilder names, particularly LEN and PHM, which are both well off their 52-week highs.
- One Thing to Remember: The NAHB does not move to 29 and then bounce quickly. When surveys and actual construction data align to the downside, homebuilder stocks tend to reset over weeks, not hours. Watch the 8:30 number, but do not trade as if one release changes the rate math.