September 26, 2026
Bonus Content: Three Numbers That Separate Bounce-Back Stocks
Dear Reader,
The Trump administration has been pumping massive cash into small resource companies lately…
Companies vital to national security.
As you can imagine, these “government targeted” stocks have soared in value.
Just look at the results:
Trilogy Metals – up 388% in 8 days.
MP Materials – up 216% in 4 months.
Lithium Americas – tripled in 3 weeks.
And America’s Economist, Dr. Mark Skousen, says it’s about to happen again.
Keep in mind… Skousen knows the President personally after Trump spoke at his FreedomFest conference.
And he’s also developed close relationships with Senators Rand Paul, Mike Lee, and others.
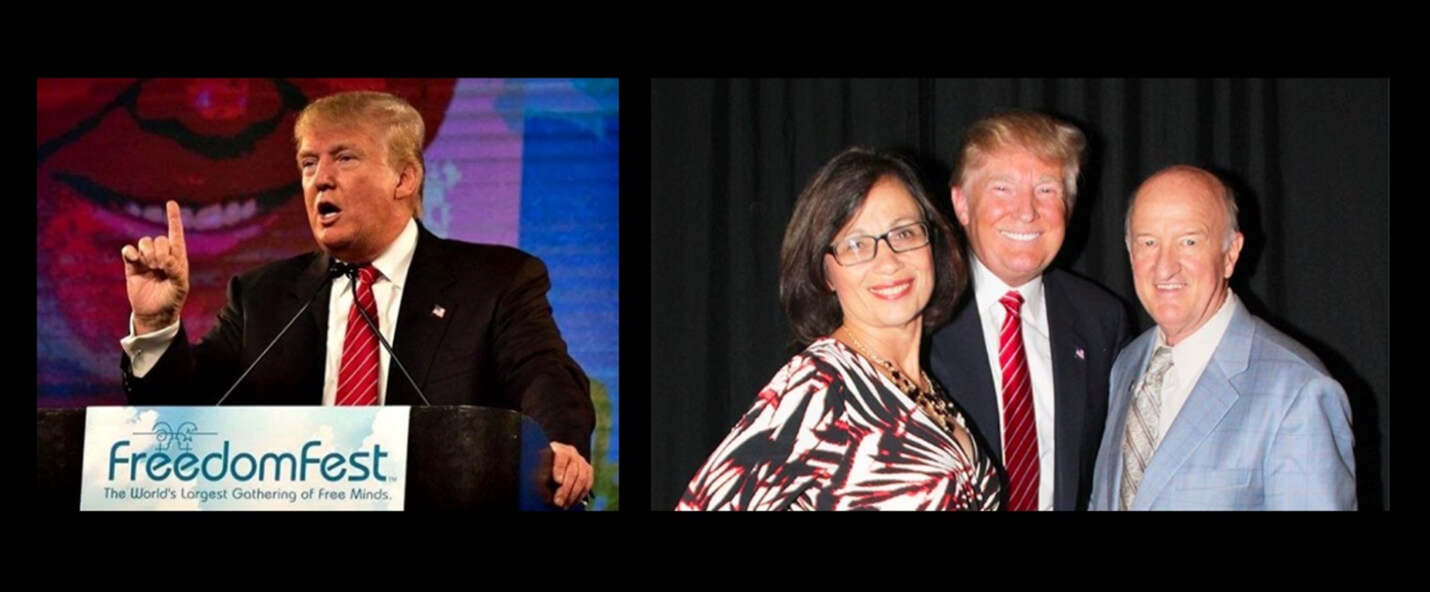
He’s learned what’s important to them.
And one thing they’ve made clear.
The current administration will take stakes in companies they deem important to national security.
Now, Dr. Skousen says he believes it will happen again.
This time with a much smaller company.
And in anticipation, he’s purchased 10,000 shares of his own.
Here’s why…
This company is the only domestic producer capable of delivering one strategic mineral America can’t do without.
That’s why Tesla just signed a binding agreement to purchase 75,000 metric tons from this company.
And it’s why the government has already handed the company grants totaling $130 million.
Dr. Skousen believes the U.S. government could take a stake at any moment in the days ahead..
He breaks down the full situation right here – read it before this stock makes headlines.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
P.S. The last time Mark felt this way about a resource stock, he turned $50,000 into a rare $1.3 million over just three years. Don’t sit on this one.
Three Numbers That Separate Bounce-Back Stocks
The question sounds simple: which beaten-down stocks recover, and which ones just sit there bleeding? After the June 2026 correction, it became urgent. After months of uninterrupted gains, June delivered the first real pullback, forcing a shift from growth-at-any-price toward companies generating real profits and cash flow. That rotation exposed a gap that price action alone cannot close.
Three metrics do most of the sorting work.
Free Cash Flow Margin Above 20%
Free cash flow is the cash a company generates after funding operations and capital expenditures, leaving money available for dividends, buybacks, debt reduction, or reinvestment. High-FCF companies carry more flexibility and resilience than those dependent on external financing. That resilience is exactly what a post-correction environment tests.
In a 40-year study comparing several common valuation metrics, Alpha Architect has written that EBITDA/EV historically ranked best among the measures they tested, with free cash flow over enterprise value also among the stronger performers over the period studied. The gap between the two is small enough that either metric flags the same class of survivor. As of September 21, 2026, one data screen of S&P 500 free cash flow margin leaders listed AppLovin near the top at roughly 71% free cash flow margin. Stocks that cleared the 20% FCF margin threshold entering the June pullback have, as a group, recovered materially faster than those that did not.
AppLovin’s position at the top of that screen is not accidental — it reflects a business model that converts a high share of revenue directly into cash without heavy capital expenditure requirements. For readers who want to understand what is driving that margin profile and how analysts are currently sizing the risk, a full breakdown of AppLovin’s Q1 2026 results, AXON launch, and analyst ratings covers the underlying mechanics in detail.
Revenue Growth Still Positive Year Over Year
Price cuts can juice a stock temporarily. Revenue contraction cannot be papered over for long. As of September 21, 2026, a scan of S&P 500 names near their 52-week lows showed the list was sizable, raising a core question: are these businesses fundamentally impaired, or are their stocks simply marked down?
The answer sits in the revenue line. PepsiCo and McDonald’s both hit 52-week lows on September 21, 2026. Neither is structurally broken. A company still growing revenue during a correction is borrowing time; one that enters a correction with shrinking revenue is already in structural decline, and the bounce is a mirage.
Trump Just Changed 401(k) Rules Forever
Your 401(k) may be about to change in a way most Americans haven’t heard about.
President Trump’s Executive Order #14330 is pushing a major shift in how retirement plans can invest – and it has now reached the Department of Labor for approval.
Get the full story and see how your retirement could be impacted.
Debt Load vs. Earnings Power
The third filter is leverage. Stocks that fail a coverage screen in a rising-rate environment tend to share a pattern: debt-funded dividends, declining margins, or coverage ratios that were already thin before the rate cycle shifted. That same pattern applies to recovery candidates broadly, not just dividend payers.
Markets are not pricing “zero rate cuts” as an established fact for the rest of 2026. What is clear is that rate expectations have been volatile and the market has at times leaned toward fewer cuts, or even tighter policy, depending on inflation and growth data. On September 21, 2026, the 10-year Treasury yield was about 4.31% on the U.S. Treasury’s published yield curve, and the long bond yield was higher than the article’s prior figure. In that environment, a company carrying heavy debt faces a rising interest burden exactly when its stock price has already compressed. The math closes off the bounce before it starts.
Super Micro Computer offers a live case study in exactly this dynamic: gross margins improved sharply, and the order backlog is substantial, but the balance sheet funding that growth is already under strain — precisely the configuration that looks attractive on a surface screen and dangerous on a coverage ratio. Why SMCI’s margin improvement may be obscuring a cash and leverage trap illustrates how the debt filter catches names that the revenue and FCF screens alone would pass.
Broadly, Q2 2026 earnings were strong, but the specific figures in this draft were not right. S&P Global Market Intelligence described Q2 2026 as a standout quarter, citing 78% of companies beating EPS estimates and year-over-year earnings growth of about 53%. Separately, FactSet has highlighted that the S&P 500’s Q2 net profit margin was on track to be about 15.7%, the highest in its series going back to 2009. That aggregate strength makes individual underperformers easier to identify: if a company missed badly while the broader market delivered unusually strong results, the problem is company-specific, and the correction may not be the reason it is down.
That same aggregate strength, however, creates a secondary problem that the 52-week-low screen does not capture: the bar for the second half of 2026 is now unusually high, and even solid results may read as disappointments against a record comparison period. How a record Q2 beat rate is setting a trap for H2 earnings expectations is worth reading alongside any recovery screen built on Q2 data.
The 52-week-low list is not a buy list. It is a starting screen. A 52-week-low list tells you where the pain is. It does not tell you which of those declines are worth buying. Run free cash flow margin, year-over-year revenue growth, and debt coverage against each name. The companies that pass all three are bouncing back. The ones that fail any one of them are going somewhere else entirely.