October 4, 2026
Bonus Content: Copper Is Down 3% on the Week. Levels That Matter Monday.
Most traders have never noticed the weird market anomaly that happens at 9:35 AM every morning.
They’re too busy with lagging indicators trying to predict the next move… when the market makers have already set the tone for the trading day.
It’s this weird anomaly that points us to the market maker’s key levels above and below.
And by playing the move within that range…
Regular folks like you have been able to reach for $100 or more (on a $1K stake) over 600 times in the last 2 years.
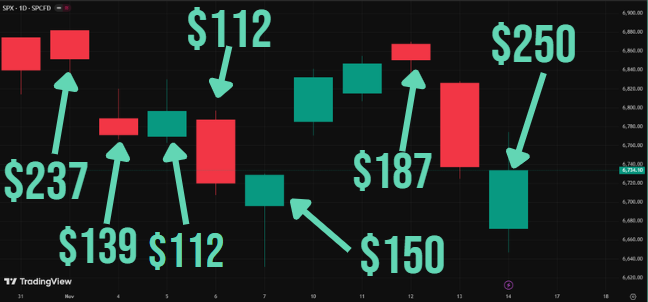
We’ve seen this straightforward approach play out whether the market broke out… broke down… or stayed choppy.
Granted, I can’t make trading guarantees here.
But I’ve opened up the data behind those trades, as well as how you can get in on the very next morning opportunity.
You’ll find the full details right here.
See you in the market.
Chris Pulver
Copper Is Down 3% on the Week. Levels That Matter Monday.
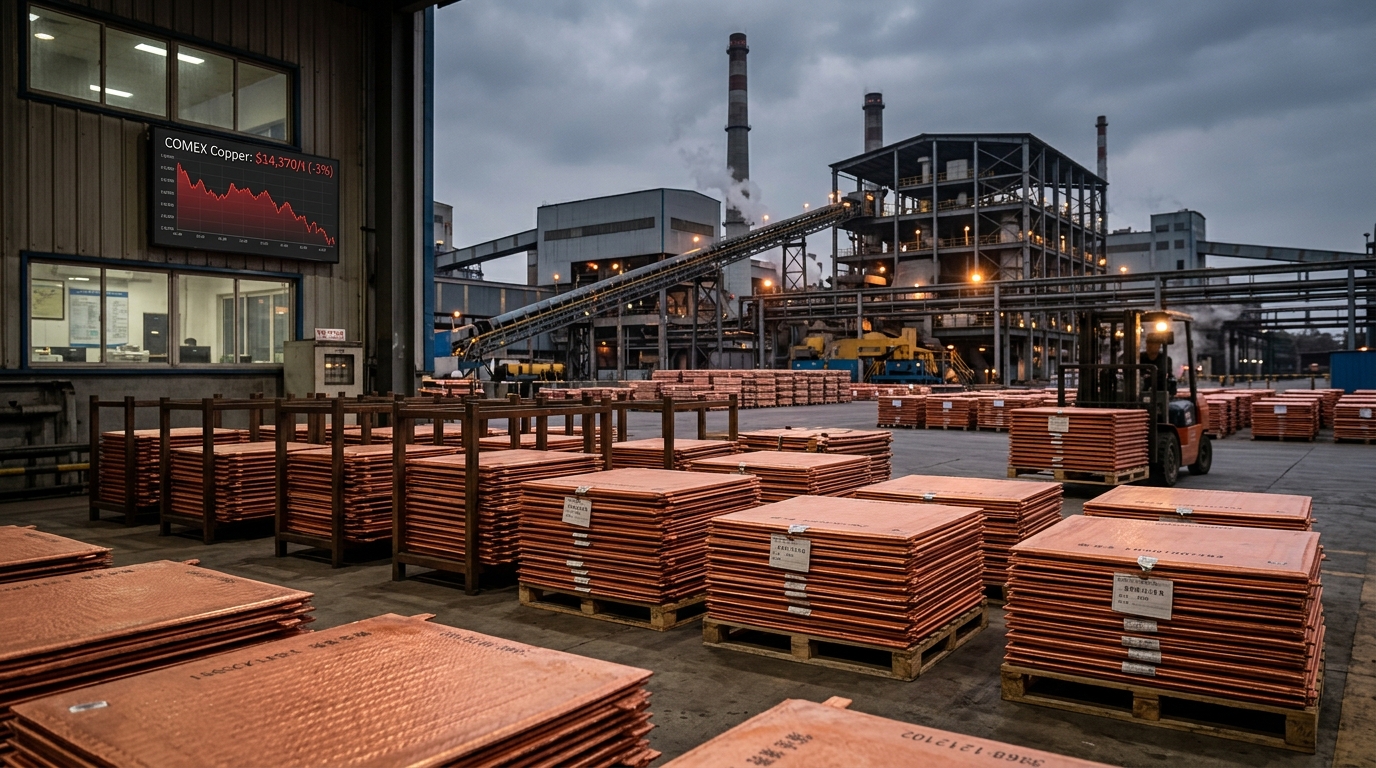
Copper traders head into Monday carrying two contradictory signals. The futures price on COMEX closed the week near $14,370 a tonne, down about 3%, while the LME settled at $14,253.50/t on October 1, roughly 4% below its September record. Yet underneath that softness, the physical market is sending the opposite message.
Market Snapshot
The LME prompt spread widened to a monthly high last week as Chinese smelters scheduled Q4 maintenance, pushing copper to a two-week low. A wider premium on nearby metal means buyers are paying up to get copper now, a sign of tight supply. The price weakness is not a demand story. It is a positioning story against a physically tight backdrop.
A fading U.S. tariff premium and a hawkish Fed outweighed fresh supply risk in Chile, where Escondida’s supervisors have voted to authorise strike action. The metal is still up about 30% year on year after a third-quarter gain of more than 4%.
Stocks in Focus
FCX (Freeport-McMoRan) is the cleanest direct exposure. On October 2, Freeport-McMoRan reported Q3 2026 consolidated copper production of approximately 830 million pounds, matching prior projections. Shares closed at $72.04, up 3.98% on the session, though the stock has shed about 9% over the past month according to TradingView data. FCX’s earnings date is October 27. That gives traders a near-term catalyst to size around.
BHP carries headline risk that FCX does not. Reuters reported that Escondida supervisors voted in favour of strike action, and that under Chilean law the parties must now enter a mandatory five-day government-led mediation process before a work stoppage can legally begin. A resolved dispute removes a price floor. A failed mediation is a different situation entirely.
Antofagasta separately lowered its full-year 2026 group copper production guidance to 625,000 to 655,000 tonnes from 650,000 to 700,000 tonnes, following a precautionary shutdown at Los Pelambres due to severe weather in Chile. The guidance cut is already in the price for Antofagasta shares, but it reinforces why Chilean supply is the market’s most-watched variable.
The Smelter Trade
This is where the copper story gets more specific. With Chinese smelters entering Q4 maintenance, refined supply tightens, which supports Chinese import premiums. China’s refined copper output growth is forecast to slow to 3% to 3.4% in 2026 from 10.4% in 2025. That is the slowest pace since at least 2000, according to Wood Mackenzie data cited by Reuters.
The constraint is no longer about ore in the ground. It is about who can process it and how quickly. Smelter throughput is the binding constraint for Q4, not mine output.
Key Levels and Risk
- COMEX support: $14,200/t. A close below there opens a test of the August range.
- COMEX resistance: $14,600/t, the post-Labour Day high before the recent pullback.
- Watch: The Shanghai Futures Exchange reopens on October 8, providing the first Asian pricing read on the Escondida dispute after a week of enforced silence during Golden Week.
- Watch: Bank forecasts around $14,500/t for Q4 2026 frame the upside if smelter tightness compounds the Chilean risk.
The Cheat Sheet
Top Theme: Physical tightness from smelter maintenance is running in parallel with a futures pullback. The two will converge.
Stock to Watch: FCX. Q3 output met guidance, earnings are October 27, and the stock has pulled back roughly 9% from its recent range high.
Sector to Watch: Copper miners broadly. BHP, Antofagasta, Glencore, and Teck all have direct price sensitivity and Chilean operational exposure.
Biggest Risk: Escondida mediation fails and a legal strike begins. Escondida produces roughly 1.0 to 1.3 million tonnes a year, and even a short stoppage shifts the annual supply balance materially.
One Thing to Remember: The prompt spread is telling a tighter story than the futures price. When physical and paper diverge this clearly, the physical market tends to win.