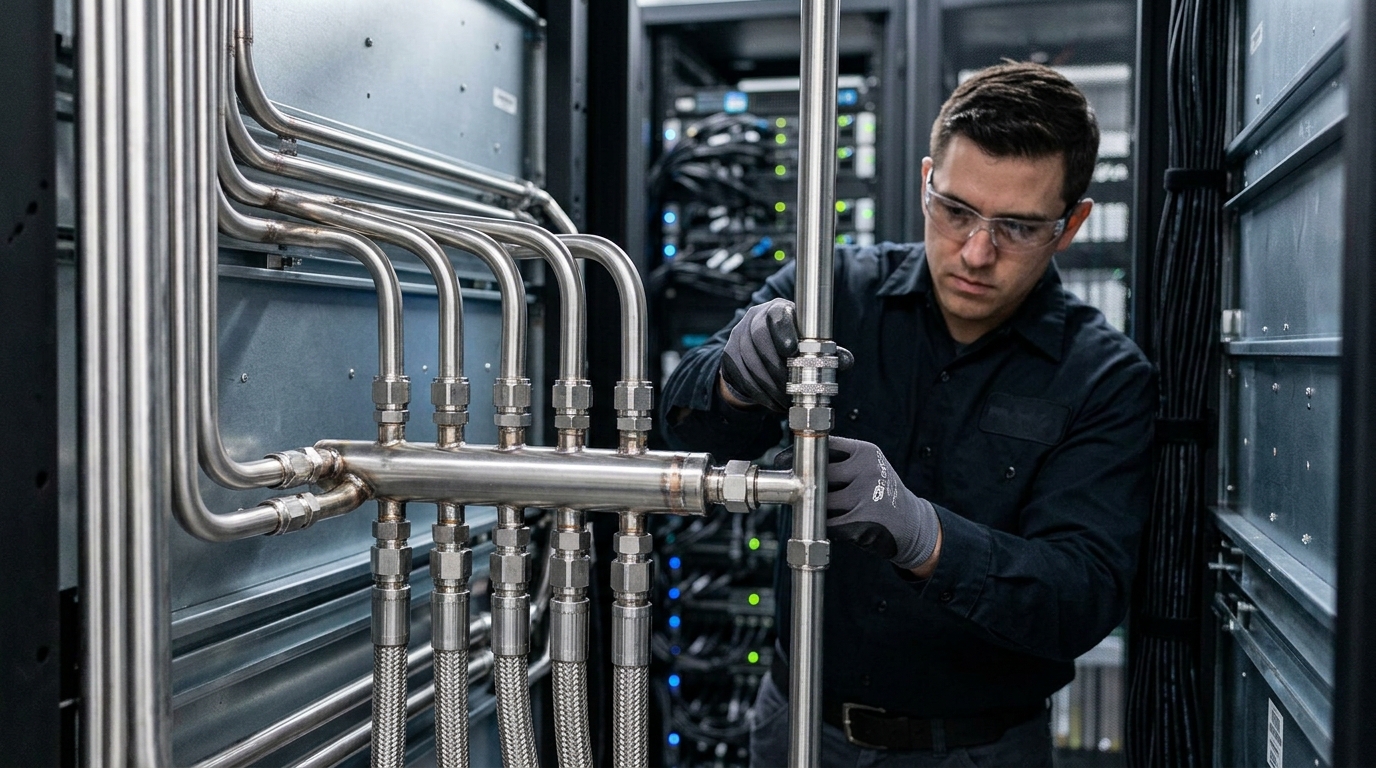
Everyone in the AI buildout is watching Nvidia’s GB200 shipment schedule. Fewer are watching the stainless steel manifold backlog.
The bottleneck for the multi-trillion-dollar AI buildout is no longer centered on chips. By 2026, access to sufficient power and water for cooling has emerged as a primary limiting factor for new data center construction. That shift is redirecting attention toward a corner of the industrial supply chain that has never been designed for hyperscale volume: fluid handling components.
A Market Waking Up Late
The global data center liquid cooling manifolds market is projected to grow from $0.94 billion in 2026 to $6.33 billion by 2033, at a CAGR of 31.2%. The plumbing itself, not the CDU, not the cold plate, is the item that frequently stalls a project. Stainless steel manifolds and pressure vessels carry the facility-side coolant loop. These are pressure-rated, often ASME-certified, and manufactured to specific dimensional tolerances that vary by customer. Lead times on custom stainless manifolds can run eight to twelve weeks even in a normal market. They are not catalog items you order and receive in days.
And normal is no longer the operating condition. The supply chain was built for a market of 5 to 8 gigawatts per year. The market is now demanding 17-plus gigawatts. That gap does not close with faster shipping. It requires additional manufacturing capacity that can take 18 to 36 months to bring online.
Who Actually Holds the Keys
Three layers of the fluid stack matter most, and each is controlled by a short list of specialists.
At the manifold and piping layer, Parker Hannifin, GF Industry and Infrastructure Flow Solutions, Valex, Hanley Controls, and Steel and O’Brien Manufacturing compete through fittings, tubing, valves, stainless steel assemblies, polymer flow systems, and custom engineered manifolds. Parker is the largest name, with data center revenue commonly described as a small portion of total sales but growing through liquid cooling systems and subsystem components. The company is increasingly positioning itself as a supplier to AI-focused data centers through its liquid cooling components, including couplings and fluid-control hardware.
GF Piping Systems is cutting into compressed project schedules from a different angle. Its ecoFIT PE-100 system, chosen for a hyperscale data center in Ireland, combined with off-site fabrication reduced on-site installation time for process water from six months to six weeks. That is the kind of schedule compression a hyperscaler will pay for.
At the quick-disconnect layer, concentration is tighter and the supply risk is higher. Quick disconnect couplings remain concentrated among a handful of Western suppliers, including Staubli, CPC, and Parker Hannifin. Staubli launched its LQD coupling in 2026, designed to meet the evolving demands of high-density, AI-driven data center cooling systems. CPC, a Dover unit, has its Everis series, built for liquid cooling in high-performance computing and data center environments where rack densities can exceed 80 kW and traditional air cooling becomes harder to scale. These companies, alongside Parker, touch a large share of Western hyperscale liquid-cooled rack deployments.
The M&A Signal Is Already Flashing
Three large acquisitions in the first half of 2026 confirm that industrial conglomerates read the same constraint. Eaton acquired Boyd Thermal on March 12, 2026 for $9.55 billion net of cash, adding a provider of thermal components and systems for data centers and other end markets. Ecolab agreed to acquire CoolIT Systems on March 20, 2026, and Schneider Electric had already signed an agreement to acquire a controlling interest in Motivair in October 2024.
The acquisition pace reflects a structural reality: the market still relies on a relatively small pool of certified suppliers, creating a constrained ecosystem struggling to meet rising demand.
What to Watch
- Parker Hannifin (PH): Fiscal 2026 full-year sales rose 8.3% to a record $21.5 billion, with organic growth of 6.6%. Data center is a small but accelerating slice. Management has pointed to data centers as an upside driver for FY27.
- Eaton (ETN): The Boyd Thermal integration gives Eaton a chip-to-grid story.
- GF Piping Systems (Georg Fischer): Privately positioned but worth tracking as a read on prefab pipeline velocity across European and Asian hyperscale projects.
GPU hardware ships on a 12-to-24-week cycle, but the facility meant to house, power, and cool that hardware can take years. Manifolds and valves sit inside that gap. Every hyperscaler racing to commission its next cluster is, whether it knows it or not, dependent on order books at a handful of fluid-handling factories most investors have never heard of.