October 13, 2026
Bonus Content: UnitedHealth Is the Wildcard Inside Tuesday’s Bank Earnings Surge
You’ve heard of a bail-out – taxpayers rescue a failing bank. A bail-in flips where the rescue money comes from.
Instead of reaching into the public treasury, a troubled bank can be propped up using the funds already sitting inside it – depositor funds. That pathway was written into U.S. law through the 2010 financial-reform legislation passed after the 2008 collapse.
Translation: a bank on the edge may have a legal route to use a portion of customer deposits to stabilize itself.
With recession risk back in the conversation and inflation eating purchasing power, this is no longer purely hypothetical. Reagan Gold Group’s free guide shows how to reposition part of your retirement into metals without triggering taxes or penalties.
UnitedHealth Is the Wildcard Inside Tuesday’s Bank Earnings Surge
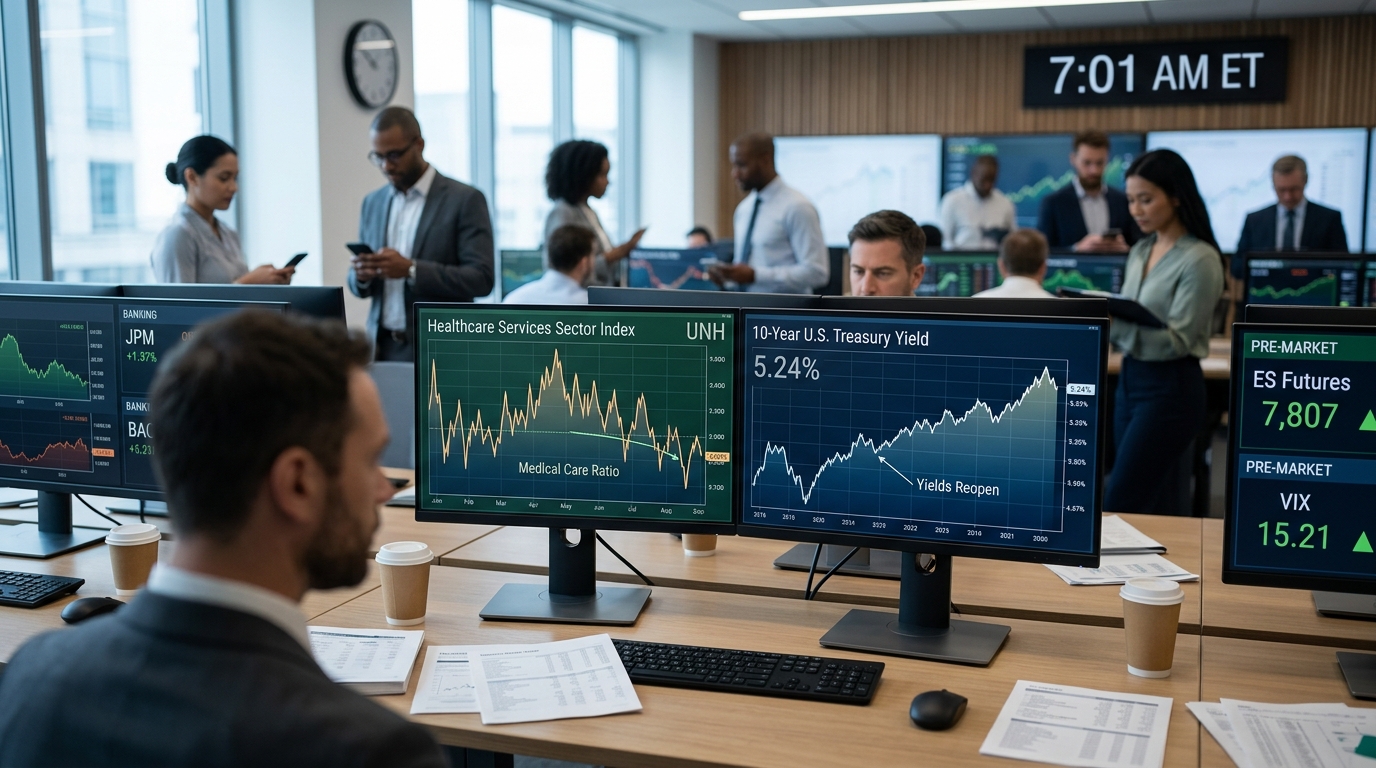
Tuesday’s calendar is dense enough to move the market in either direction before 10 a.m. Six companies report before the open, the cash Treasury market reopens after Monday’s Columbus Day closure, and the NFIB small business index lands at 6 a.m. ET. The S&P 500 finished Monday at 7,807, down a fraction, with technology dragging while Energy and Consumer Staples gained. The VIX edged up to 15.21. None of that tells you much; the real read comes from what hits Tuesday morning.
Market Snapshot
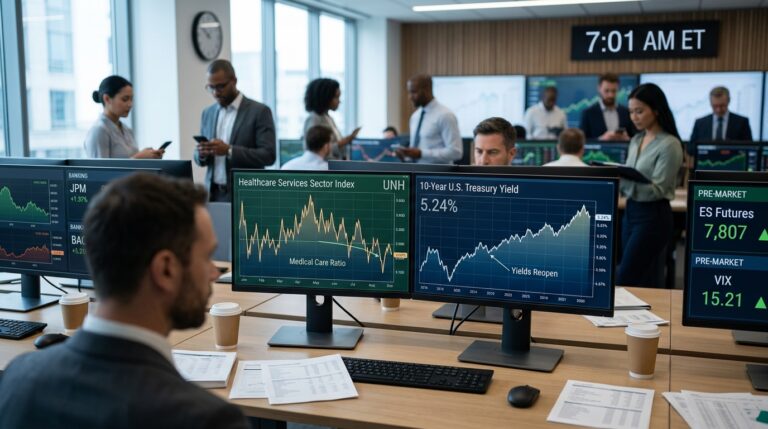
The 10-year yield held near 5.24% Monday because the cash bond market was closed. That changes Tuesday. Yields have steered equity direction for weeks, and any move on reopening will ripple immediately into bank stocks, rate-sensitive sectors, and gold, which slipped Monday. Pimco flagged last week that 10-year yields risk touching 6% for the first time since 2000. If that commentary gets traction when the bond market opens, financials could face a headwind even on strong earnings beats.
Stocks in Focus
UnitedHealth (UNH)
This is the most consequential report of the day, and it has almost nothing to do with banks. Wall Street expects $4.12 per share on $111.3 billion in revenue, a 41% earnings jump year over year. The stock has fallen roughly 17% since its last report while the S&P 500 edged higher, leaving UNH about 20 percentage points behind the broader market. The question is not whether UNH clears a modest bar. It is whether management can demonstrate that the Q2 improvement in its medical care ratio, which dropped to 86.7% from 89.4% a year earlier, was structural rather than a one-time benefit from $860 million in favorable reserve development. Analysts expect the Q3 medical care ratio to reach 90.1%. A reading above that figure, or any cut to the full-year adjusted earnings outlook of $19.50 to $20.00 per share, will punish the stock. Medicare Advantage membership is already down 965,000 from year-end 2025, with the company expecting total 2026 contraction of roughly 1.3 million to 1.4 million members.
JPMorgan Chase (JPM)
Consensus sits at $5.93 per share on $51.2 billion in revenue. JPMorgan is expected to lead the large-bank group with 9.6% revenue growth and 12.5% net income growth year over year. Total net interest income for the quarter is forecast at $26.9 billion, up 12% from a year ago. JPMorgan’s card net charge-off rate guidance improved to roughly 3.2% from an earlier 3.4% target, a small but meaningful credit quality signal. The tone Jamie Dimon sets on the consumer and the macro outlook will define the sentiment backdrop for the rest of the earnings week.
Capital requirements are a quieter variable behind JPMorgan’s guidance. The Fed’s new stress-test averaging rule is designed to cut year-over-year capital buffer volatility by roughly half, which changes how much room Dimon has to deploy earnings.
Goldman Sachs (GS)
Goldman enters Tuesday with 17 downward EPS revisions and no upgrades in the past 30 days. The stock sat at $895 as of October 9, down about 22% from its 52-week high. Revenue is expected at roughly $16.8 billion, up about 11% year over year. CEO David Solomon flagged in September that equities trading remained strong but FICC was softer in the quarter, and that non-compensation expenses would come in more than $500 million above Q2 levels. Goldman’s equities business is forecast to generate $4.96 billion in Q3 revenue, up 33% year over year, but that needs to offset both the FICC slowdown and the expense drag. The wide analyst range, from $13.35 to $16.42 per share, signals genuine uncertainty.
Wells Fargo (WFC)
Consensus is $1.85 per share on $22.3 billion in revenue. Net interest margin compressed to 2.43% in Q2 and management guided for modest further pressure in Q3, with stabilization expected in Q4. The Fed’s September rate hike of 25 basis points to a 3.75%-4.00% range came too late in the quarter to meaningfully lift Q3 NII. Credit quality is the secondary watch: Q2 net charge-offs ran at 0.34%, down 10 basis points year over year, but Middle East uncertainty and persistent inflation have elevated credit risk monitoring.
Catalyst Calendar
- 6:00 a.m. ET, NFIB Small Business Optimism (September): Consensus at 98.0, down from 98.7 in August. Three consecutive months of declining readings would signal small-business confidence eroding under higher rates and inflation. The labor-related sub-components are the most watched.
- 8:15 a.m. ET, ADP Weekly Employment Change: Prior reading was 23.8K. Thin but directional ahead of Wednesday’s CPI.
- 10:00 a.m. ET, Existing Home Sales (September): Consensus at 3.96 million, from 3.98 million. With the 30-year mortgage rate last at 7.49%, any further deterioration in housing volume confirms the rate-stress thesis across the economy.
- Fed Governor Waller speaks at 7:45 a.m. ET. Any comment that frames the September hike as the last, or as a potential precursor to more, will move rates and dollar positioning immediately.
Technical Radar
SPY holds above the $777.71 pivot that defined last week’s bounce. A gap higher on bank beats could push it toward the $780 resistance. On the downside, $776 is the level to watch if yields spike on bond market reopening. The Nasdaq’s semiconductor complex, which dragged the index 0.44% lower Monday, needs SMH to stabilize above its recent lows or technology’s drag worsens into Wednesday’s CPI.
The Cheat Sheet
- Top Market Theme: Six earnings reports and a reopening bond market collide on the same morning. Which one speaks louder sets the direction for the rest of the week.
- Stock to Watch: UnitedHealth. The medical care ratio is the single figure that determines whether Tuesday is a healthcare-sector rally or another leg lower in a stock already 20 points behind the index.
- Sector to Watch: Financials. Bank shares enter Tuesday under yield pressure, and even strong beats may be sold if bond market reopening pushes the 10-year above 5.30%.
- Biggest Risk: The cash Treasury market. Monday’s holiday muted the rate signal. Tuesday morning, yields move freely again, and direction above or below 5.24% will make or break the bank earnings reaction.
- Biggest Opportunity: A UNH beat with maintained full-year guidance reopens the managed-care trade after weeks of forced selling. Humana and Elevance Health would follow.
- One Thing to Remember: Goldman’s earnings range is unusually wide, from $13 to $16 per share. Do not assume the street consensus tells you where the stock goes; the reaction will depend on which business line surprises, and the signal from FICC versus equities has implications for every trading desk on the street.