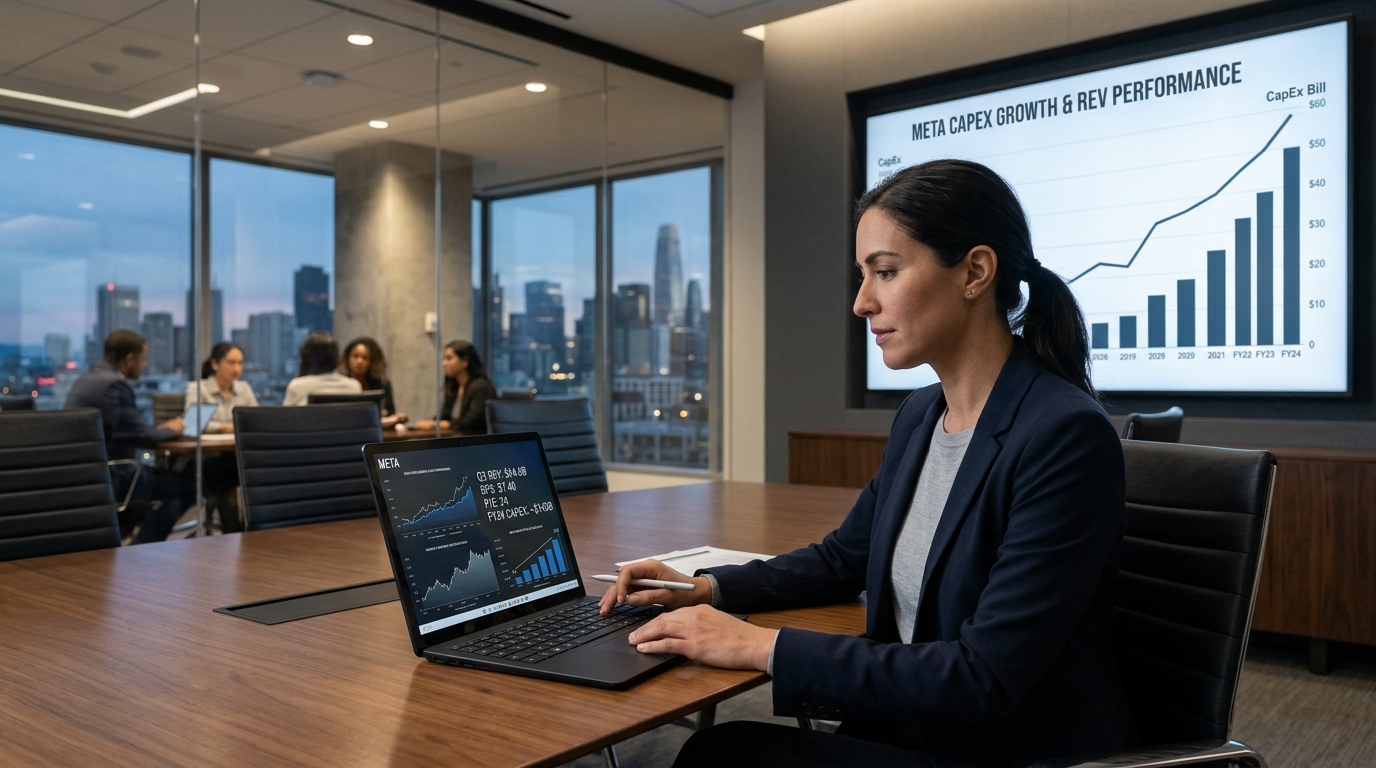
Meta just reported Q3 numbers that, on the surface, look unambiguously good. The company posted adjusted EPS of $7.40, beating the $6.54 consensus by $0.86, while quarterly revenue rose 26% year-over-year to $64.60 billion, topping the $63.34 billion estimate. Fourth-quarter revenue guidance came in at $73 to $76 billion. The stock ticked up roughly 2.5% after hours. So: is Meta expensive? The answer depends almost entirely on which line of the income statement you look at.
The Bull Case Lives in the Revenue Line
Users grew only 3%, yet revenue grew 26%. Meta is earning far more from each person, not just reaching more people, and the company credits AI for better recommendations and stronger ad results. Headcount fell 15% from a year ago to 66,775, while revenue grew 26%, pushing quarterly revenue per employee from roughly $650,000 to $970,000, an increase of nearly 50%. That kind of operating leverage, at a $200 billion annual revenue base, is genuinely rare.
Although the stock is approaching $800, the valuation is not enormous in earnings terms. It trades at about 28 times trailing earnings, but on a forward price-to-earnings basis the multiple is about 22 times.
The Bear Case Lives in the Capex Line
Here is where the valuation question gets genuinely complicated. Meta now expects 2026 capital expenditures, including principal payments on finance leases, to be in the range of $135 to $145 billion, narrowed upward from the prior outlook of $130 to $145 billion. That figure was $72.22 billion in 2025. It has effectively doubled in a single year.
In Q2, capex was $31.1 billion, while operating cash flow was $31.86 billion. Free cash flow, the metric that actually funds buybacks and dividends, is being redirected almost entirely into data centers and AI infrastructure.
The capex squeeze is not unique to Meta. Hyperscalers collectively face a 15% unit-cost increase on Nvidia rack systems shipping in 2027, compressing free cash flow further across the entire AI buildout.
What the Numbers Actually Say
Operating margins contracted sharply from 40% in Q3 2025 to about 20% in the latest quarter, though much of that compression came from a one-time charge. Costs jumped 68% to $51.61 billion, largely because of a $9.89 billion legal charge related to the multistate attorneys general agreement tied to teen mental health and social media.
Strip out that charge and the underlying operating picture is cleaner. On the earnings call, Zuckerberg said Muse, the company’s AI agent, has drawn account sign-ups from over 10 million people across the U.S. and Canada. Early traction, but nothing close to a revenue contribution yet.
The honest answer to whether Meta is expensive: it is not expensive on earnings, but it is expensive on free cash flow. Traders who price it on forward P/E find a reasonable multiple. Traders who price it on what actually lands in the bank account find a company that is spending most of it. Which version matters more will be decided by whether Muse and the AI ad stack justify the $140 billion tab.