Prologis spent the better part of 2026 chasing SEGRO. Four offers, months of fraught negotiations, and a final £14 billion bid that SEGRO shareholders approved 98.14% in favor on September 28, 2026. The deal is expected to close in the first half of 2027, but the UK’s Competition and Markets Authority is currently seeking views on the acquisition, with the comment period closing November 10, 2026. That is regulatory uncertainty Prologis cannot control. What it can control is what comes next.
The SEGRO deal was never really a warehouse play. Prologis has framed the combination as expanding long-term growth opportunities across logistics, energy and digital infrastructure, with SEGRO’s portfolio and power rights a key part of the equation. The underlying logic: Prologis already has the land, the logistics density, and the customer relationships. What it lacks is the operating credibility of a pure-play data center operator at hyperscale. That gap points squarely at Digital Realty Trust.
Digital Realty now operates roughly 310 data centers with approximately 3.1 gigawatts of IT capacity and over 7 gigawatts of additional future development capacity. Compare that to Prologis, which expanded its own data center power pipeline to 5.8 gigawatts as of Q2 2026. The two together would control a combined pipeline exceeding 12.8 gigawatts, a figure that dwarfs any single competitor in the sector.
The operating momentum at DLR is real. Its development pipeline expanded to about 1.4 gigawatts under construction in Q2, with leverage at 4.7 times debt to adjusted EBITDA and roughly $6 billion in available liquidity. Core FFO (excluding net promote) grew about 14% year-over-year to $2.13 per share, and the company entered an energy service agreement to provide 600 megawatts of utility power in the Kansas City metro by early 2028, rising to two gigawatts at full delivery. This is not a distressed asset. It is a company in the middle of its own buildout cycle.
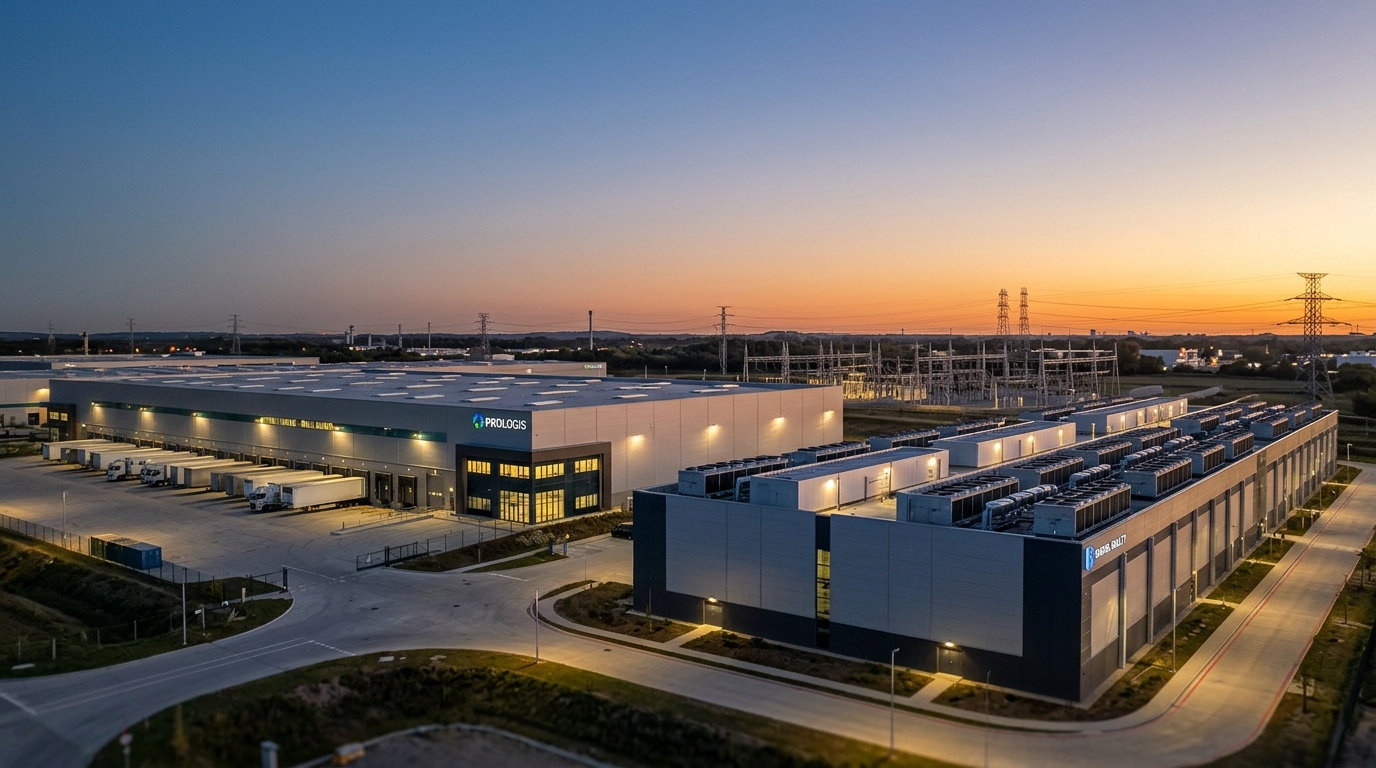
That is precisely the point. Prologis is building data centers from scratch, spending roughly $4 billion to start hyperscale, build-to-suit projects. CEO Dan Letter, who took over on January 1, 2026, told CNBC’s Mad Money that data centers are one of the largest value creation opportunities in Prologis’ history. The pivot is deliberate. The question is whether organic development is fast enough.
The hidden angle here is power. Prologis partnered with Nvidia, InfraPartners, and EPRI to study smaller-scale data centers designed for distributed inference, including deployment of micro data centers at or near utility substations with available grid capacity that can be quickly deployed. Digital Realty is running the same playbook at far greater scale. An acquisition collapses years of site-by-site power procurement into a single transaction.
The risk is sequencing. Prologis cannot close SEGRO and digest a DLR acquisition simultaneously without serious balance sheet pressure. But if CMA clears SEGRO cleanly and the combined entity demonstrates integration discipline through mid-2027, Digital Realty becomes the logical capstone. Watch the CMA comment deadline on November 10, 2026. That clock tells you how much runway Prologis actually has before the next move becomes possible.