October 29, 2026
Bonus Content: ECB Holds Today. December Is the Decision That Matters.
When news broke overnight about China’s Moonshot AI unveiling its new model…
The market gapped down 1% before most traders even poured their morning coffee…
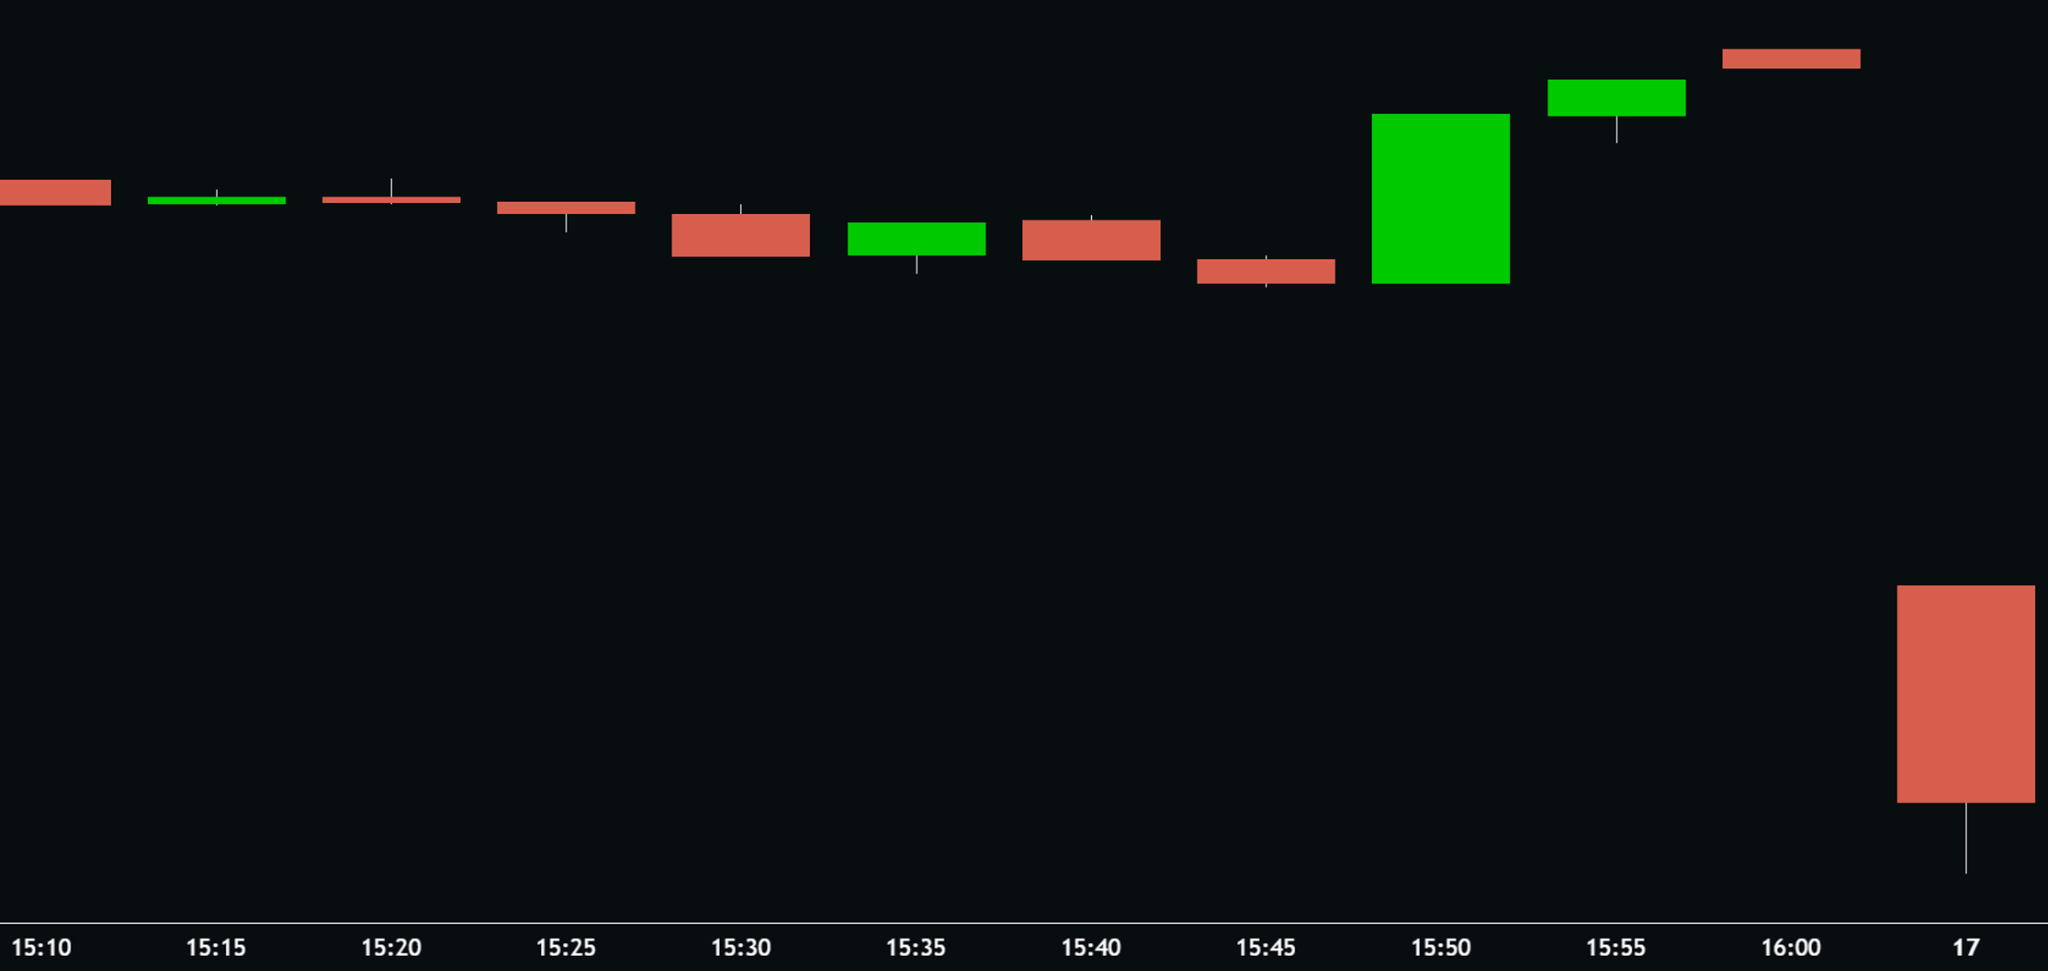
For standard portfolios, it looked like the start of another stressful day…
And over the next two hours, the market barely crawled higher… moving a tiny 0.2%…
To traditional buy-and-hold investors, a 0.2% move is practically useless…
Yet, according to our research, anyone who ignored the overnight headlines and waited until exactly 9:50 AM Eastern could have locked in a $529 payout before lunchtime… on a simple $1,000 starting stake…
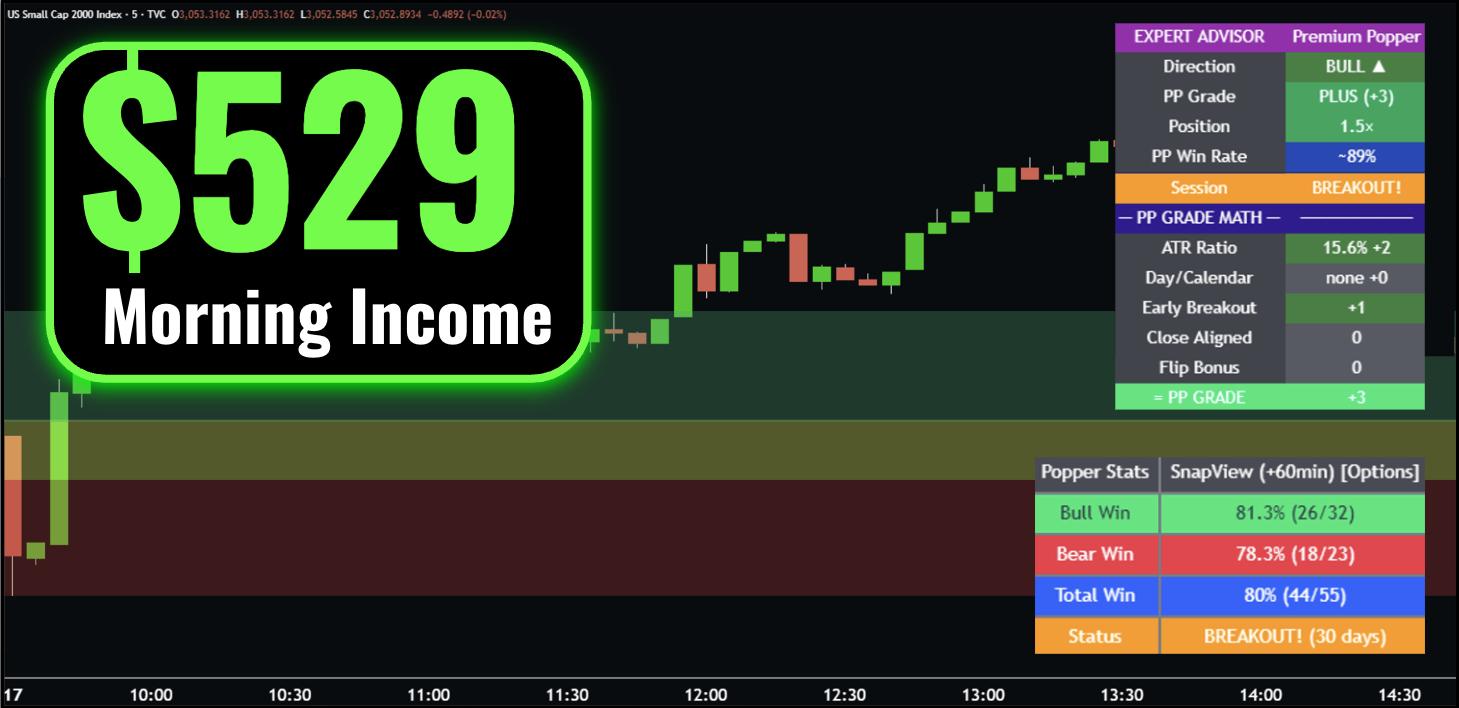
That would not have been an isolated fluke either…
Back on June 25th, when inflation surged past 4%…
And panicked investors expected a massive market beatdown… the market moved just 0.3% after the open… yet that exact same morning setup yielded another $526 payday before lunch…
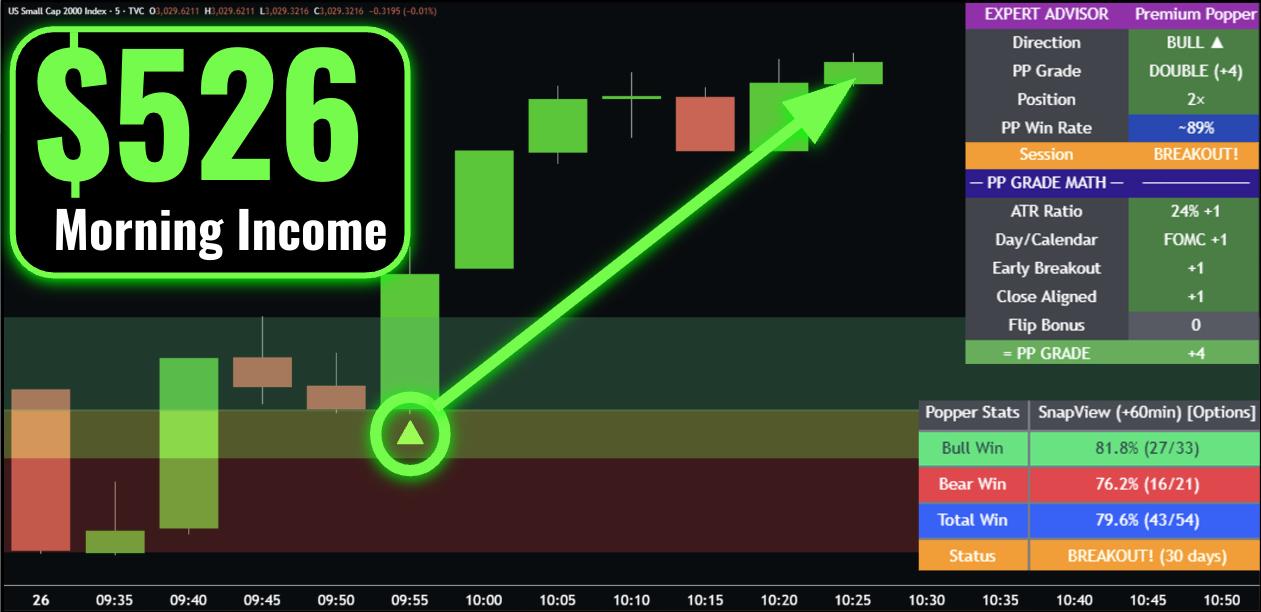
Of course, there would have been smaller gains and some that did not work out, but…
How would it have been possible to pull $500+ out of the market on a tiny fraction-of-a-percent crawl… while traditional traders are getting chopped to pieces?
It all comes down to an institutional phenomenon that happens during the first 20 minutes of every trading day…
Between 9:30 AM and 9:50 AM, Wall Street heavyweights enter a massive brawl to settle block orders… pushing nearly 25% of the entire day’s volume into a brief 20-minute window…
Right around 9:50 AM, the brawl ends… the dust settles… and the market literally hands us its direction for the rest of the morning…
By placing just one simple trade on one ticker right as that direction becomes clear…
You give yourself a shot to walk away with $500 in hand before lunch, leaving you completely free for the rest of your day…
While I cannot make any guarantees in the market…
Recently, I sat down live on camera with a former money manager to lay out the floor data behind this 9:50 AM morning phenomenon…
And how anyone with a normal brokerage account can take advantage of this step-by-step…
Tap here to watch the complete video breakdown before access is taken down.
See you there,
Silas Peters
ECB Holds Today. December Is the Decision That Matters.
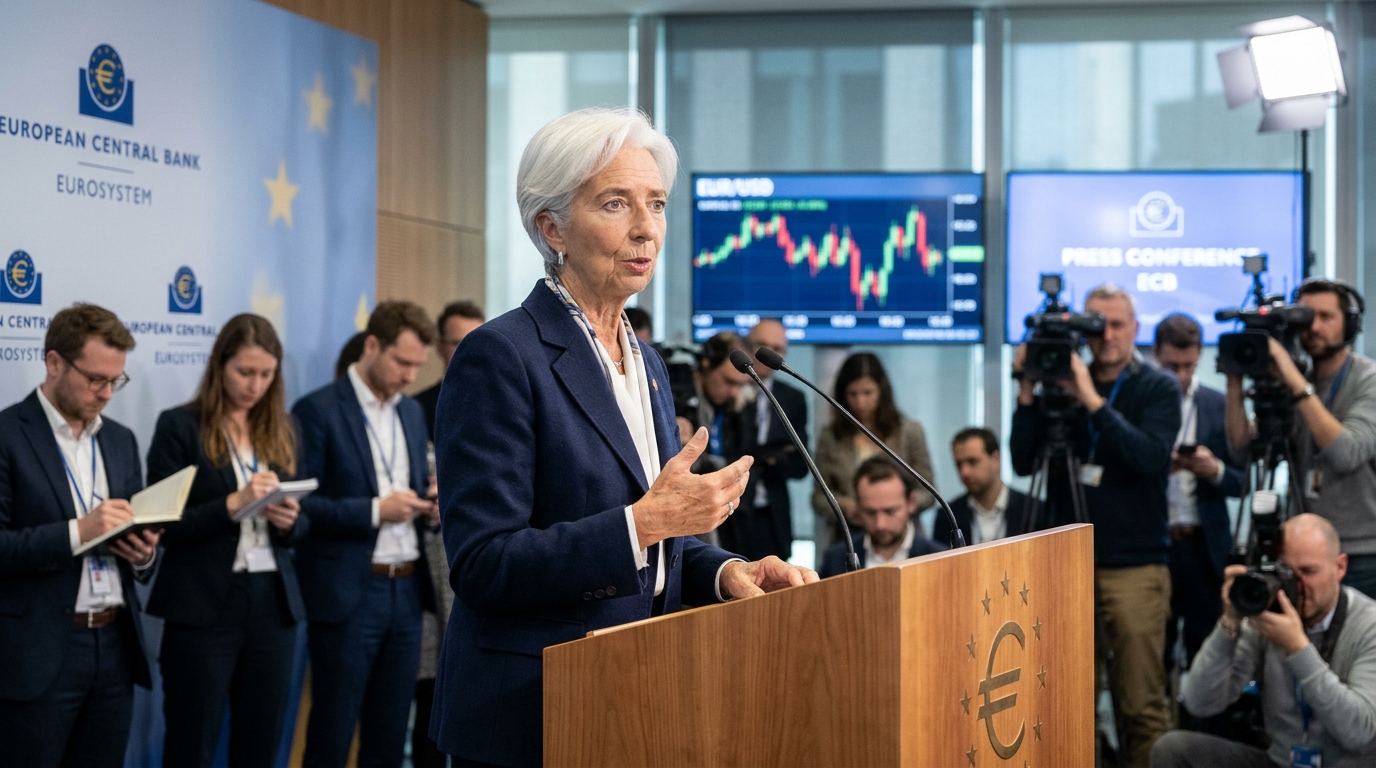
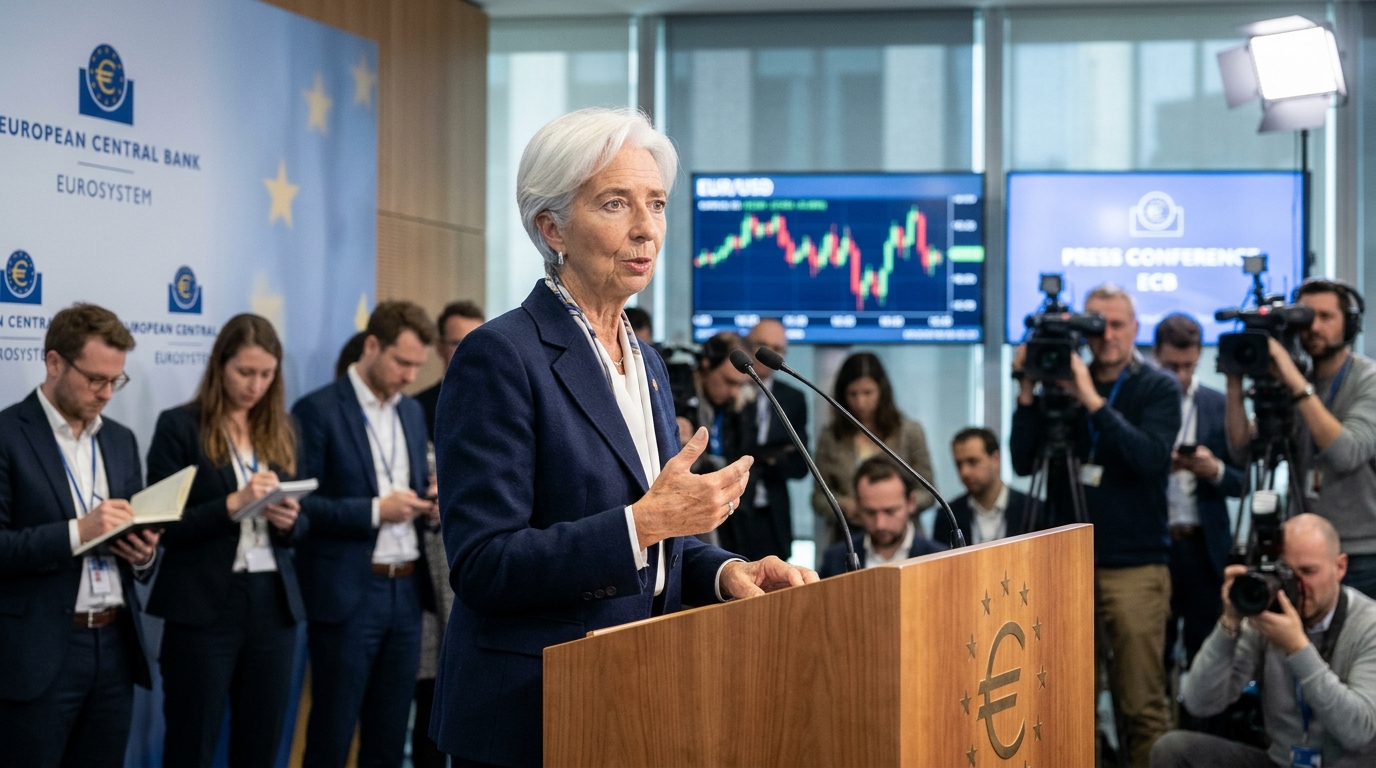
The ECB announces its rate decision at 13:15 UTC today, and the headline is already written: no change. The deposit rate stays at 2.50%, the main refinancing rate at 2.65%. What is not settled is how aggressively Christine Lagarde uses the 13:45 UTC press conference to flag December as a live meeting, and that distinction could violently shift a currency market sitting on heavy short exposure.
Market Snapshot
EUR/USD has traded to 17-month lows through October, weighed down by energy-driven stagflation fears, widening French sovereign spreads, and capital rotating toward higher-yielding U.S. assets. Gross short exposure among large speculators in euro futures has surged to roughly the mid-300,000s contracts in October, a cycle high, while EUR/USD has refused to break its May low. That divergence matters: when a currency cannot fall under the weight of extreme bearish bets, even a modest positive surprise can accelerate a short-covering move.
What the Data Says
Euro area inflation hit 3.8% in September, a three-year high, driven by an 18.9% annual surge in energy prices tied to the ongoing U.S.-Iran conflict. Brent crude has traded above $105 per barrel in the second half of October. Core inflation edged to 2.5%.
Despite those numbers, Lagarde struck a notably softer tone in late September, arguing that rising long-term bond yields were already tightening financial conditions. French sovereign stress added another reason to wait. That combination is why 64 of 73 economists in a Reuters poll point to December for the next 25bp increase, taking the deposit rate to 2.75%.
The Reuters economist poll itself reflects a broader credibility problem. ECB policymakers have repeatedly failed to convince markets their rate path will go as high as their own guidance implies.
Stocks in Focus
European bank equities and energy names are the most direct movers. A hawkish Lagarde lifts rate-sensitive bank margins and reinforces the bid in energy stocks already supported by elevated oil prices. A softer tone risks unwinding those trades quickly. Goldman Sachs and PIMCO both see December as the likely move, which means the bar for today’s statement to genuinely surprise is high but not zero.
Risk Radar
- Short squeeze in EUR/USD. Heavy gross shorts mean even modest hawkish language could trigger a covering rally that runs further and faster than the fundamental case warrants. A sharp euro move tends to pressure U.S. equity futures mid-session.
- French fiscal contagion. The French sovereign spread to German Bunds has reached its widest levels since the 2011-2012 eurozone crisis period. A dovish signal that reads as ECB capitulation to fiscal pressure could reignite peripheral bond selling.
- Energy re-acceleration. If Lagarde acknowledges that energy prices have overshot the ECB’s assumptions, that alone sharpens December expectations without requiring an overtly hawkish statement.
The Cheat Sheet
Top Market Theme: ECB holds, but the statement and press conference determine whether December is near-certain or merely possible.
Stock to Watch: European financials. Directionally tied to any shift in ECB rate expectations from today’s language.
Sector to Watch: Energy. Brent above $100 underpins the inflation argument for further tightening.
Biggest Risk: A EUR/USD short squeeze hitting U.S. futures mid-session if Lagarde sounds more hawkish than her late-September tone implied.
Biggest Opportunity: EUR/USD positioning is stretched enough that even a neutral hold, with measured language, could produce a tradeable bounce off 17-month lows.
One Thing to Remember: The rate decision at 13:15 UTC is a formality. The press conference at 13:45 UTC is the trade.