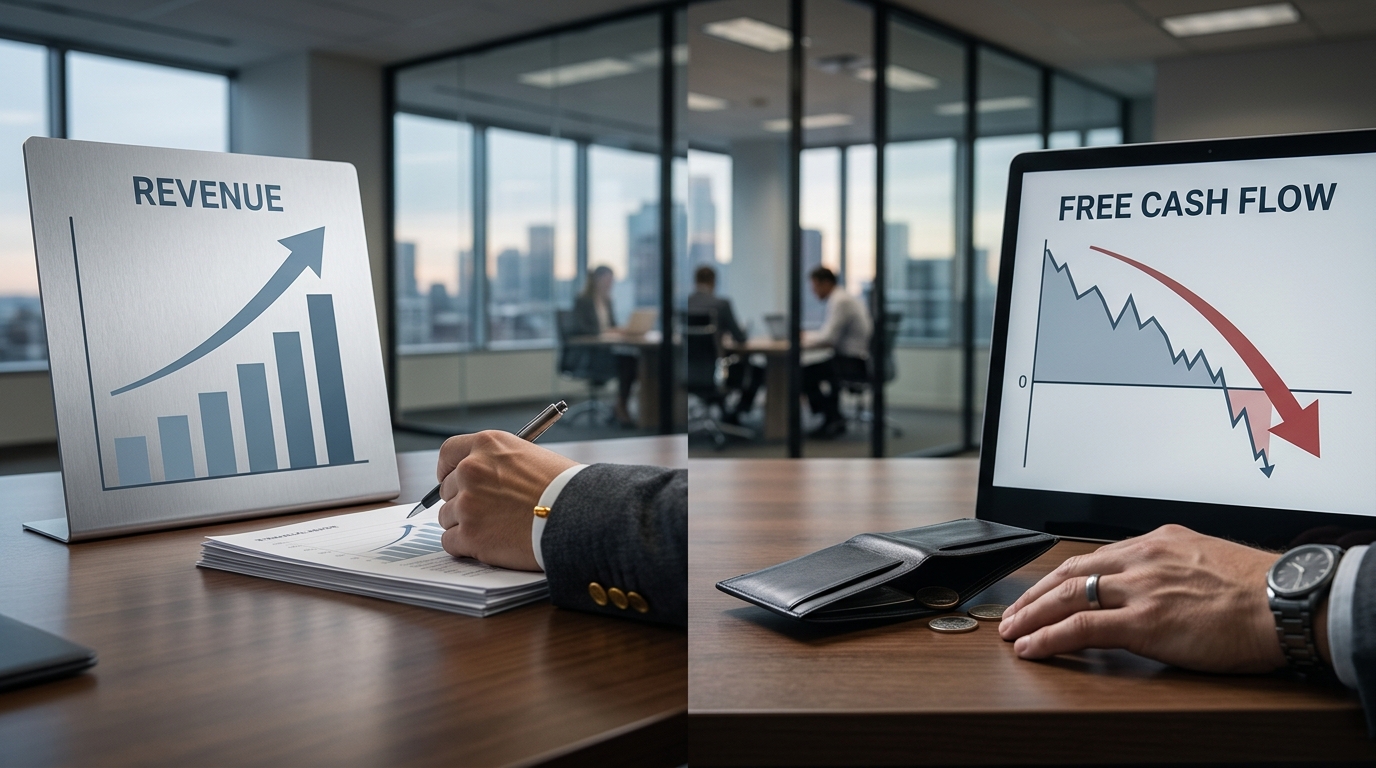
The ads are working. The cash machine is broken.
Meta’s Q3 2026 revenue rose 26% to $64.6 billion. But the headline profitability picture is distorted by a $9.89 billion legal charge tied to an August 2026 agreement with U.S. state attorneys general. The cash flow is not.
Free cash flow fell to negative $2.12 billion from positive $10.63 billion a year ago. Operating cash flow was $32.79 billion, but capital expenditures, including principal payments on finance leases, rose to $34.91 billion, driven by investments in servers, data centers, and network infrastructure. For the quarter, the business spent more than it generated in cash.
The user side is where analysts have started flagging the deceleration that matters for traders heading into the weekend. Worldwide daily active people increased 3% to 3.64 billion on average during September 2026 from 3.54 billion during September 2025.
The ad pricing engine is compensating for now. In Q3, the company said ad impressions were up 10% and average price per ad was up 14%, consistent with the roughly 26% revenue growth rate. That is the formula Meta has leaned on: if you cannot grow the audience meaningfully, raise the yield. The question for traders is how long price growth absorbs the volume slowdown before advertisers push back or shift budgets.
The capex math is where the forward risk lives. Management narrowed 2026 capital expenditures, including principal payments on finance leases, to $135 billion to $145 billion. Hitting that range implies a step-up in Q4 spending versus Q3.
The capex commitment is only half the equation. At least $260 billion in U.S. data center investments were canceled in 2026, raising questions about whether hyperscaler spending translates into usable capacity.
AI investments are critical, but spending discipline is lacking. Free cash flow turned negative in Q3, and near-term cash generation will likely stay pressured as capex remains elevated.
Management said it is still developing next year’s budget and capacity plans. That is the tell. When a company refuses to scope the year ahead, the market fills that gap with the worst plausible number. For META at current levels around $630, the consensus mean target sits near $836. That spread is real. So is the trajectory of a business where capex is outrunning cash, user growth is slowing, and the company is not ready to quantify what comes next.
The contrast with Meta’s unresolved budget picture is sharpest when set against its closest ad rival. Alphabet has already converted AI infrastructure spending into measurable enterprise cloud revenue, a path Meta has not yet demonstrated.
Watch the $620 level. A break there opens a re-test of the September range. On the upside, $660 is the line that needs to recover before the bear case starts to fade.