October 31, 2026
Bonus Content: China’s Factory PMI Missed 50.0. Miners Face Monday.
Something strange is happening to your money.
It wasn’t voted on. It wasn’t debated in the Senate. And most Americans have no idea it’s even taking place but…
President Trump is replacing the U.S. dollar.
Not with crypto. Not with a digital currency. Something far bigger than that – and it’s already been signed and sealed in the back rooms of D.C., ready to be issued by the U.S. Treasury.
Bypassing every legal and political channel under the guise of “national security,” Trump has enacted this total money reset using a landmark executive order (1421).
Whether you’re a Democrat or Republican, whether you support this new money or not, it doesn’t matter.
Soon, every U.S. citizen will be forced to use Trump’s New Dollar to fill their gas tank, buy groceries, and pay medical bills.
Which is why I’ve produced a critical new documentary laying out exactly what Trump’s New Dollar means for your savings, your investments, and your family’s financial future.
Detailing three important steps you can take today to prepare – including the name of a core band of assets connected to Trump’s initiative that could surge as a result.
As you’ll see in my briefing, the last time America reset its money like this – under Richard Nixon’s presidency in the 1970s – it created one of the greatest wealth divides in the history of our nation.
On one side, it minted an average of 1,300 new millionaires a day for over half a century. And on the other… the folks left behind, drowning in debt, with no idea how to use America’s new money to create wealth.
As Trump rolls out his new dollar, the question is:
Good investing,
Porter Stansberry
PS. If you’re wondering what Trump’s new money will look like, when it will be issued, what it means for your investments and why it could be front page news on December 14 – all of those questions are answered in my briefing.
China’s Factory PMI Missed 50.0. Miners Face Monday.
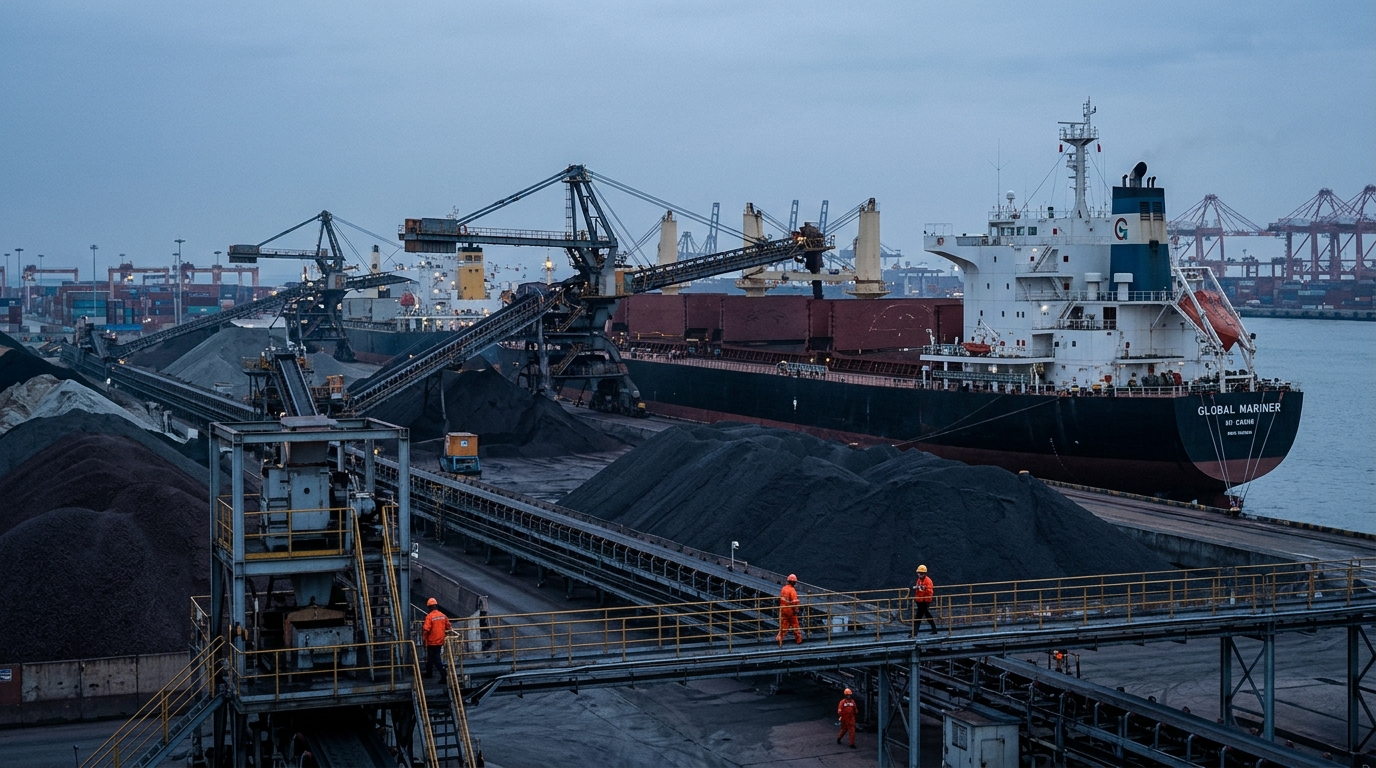
The first hard data out of China since the US-China tariff-cut lists took effect landed Saturday morning, and it went the wrong way. China’s National Bureau of Statistics reported the manufacturing PMI fell to 49.3 from 50.1, below a Reuters poll of 50.0. That is the sharpest monthly drop in three months and the third contraction in four months, not the stabilization the tariff relief optimists needed to see.
The composite PMI output index fell a full point to 49.7, with the manufacturing PMI, non-manufacturing business activity index, and composite PMI output index all retreating from the prior month. When both manufacturing and services cross back below 50 simultaneously, the market tends to treat it as a demand signal rather than a one-sector blip.
The PMI’s sub-50 composite reading feeds directly into commodity futures pricing before equity markets open. Iron ore futures have historically repriced sharply on Chinese demand signals, with speculation and port inventory levels amplifying the move.
What Drove the Miss
Overseas Christmas-related orders that had been pulled forward into September cooled during October, while consumer spending that had risen during the National Day holiday in the first week of October faded afterward. In other words, September’s 50.1 reading borrowed activity from October rather than reflecting a genuine recovery in underlying demand.
The new orders index declined 1.1 points to 49.4, with new orders falling back below the expansion threshold and new export orders staying in contraction territory. Zhang Liqun said insufficient demand was increasing downward pressure on the economy, while Zhang Zhiwei called for more significant policy support to boost domestic demand if external demand weakens into 2027.
What Traders Watch Monday
This is the first PMI since the tariff-cut deal between Washington and Beijing took effect, with the effective tariff rate on China estimated to have dropped from around 22% to roughly 20.5%, still significantly higher than the roughly 11% before Trump’s return to office. The relief was always modest; Saturday’s PMI confirms it has not yet moved demand needles in the factory sector.
Iron ore was already struggling going into this release. Iron ore prices had tumbled to their lowest levels in over two years, driven by weakening steel demand in China and expanding global supply. Horizon Insights chief ferrous analyst Mengtian Jiang said iron ore is likely to stay soft through November, with prices potentially extending declines toward $85 to $86 a tonne, as the final two months of the year are historically the weakest period for steel consumption.
That backdrop frames Monday’s open for BHP and RIO directly. Jiang noted that mills are restocking only hand-to-mouth against elevated port stocks, and shipments from the four major miners, including Rio Tinto and BHP, are expected to rise in the fourth quarter. More supply into softer demand is a difficult combination for share prices.
CAT is the industrial name most directly exposed to this demand signal. Caterpillar’s China-linked construction and mining revenue faces a harder test than its autonomous fleet narrative can offset.
Levels and Names to Track
- BHP and RIO: BHP had already slipped to $84.65 and Rio Tinto to $92.87 in early October as investors looked past near-term earnings strength and focused on the demand side. A sub-50 PMI reading arriving over the weekend removes any near-term reprieve argument.
- FXI and CNY: PMIs are designed as early-warning indicators, and a sub-50 reading often shifts growth and earnings expectations before slower official data like industrial output and trade arrives. Watch FXI at the open and the yuan against the dollar for any sign of renewed depreciation pressure.
- CAT: Caterpillar derives a material share of its construction and mining equipment revenue from China-linked infrastructure cycles. A composite index at 49.7 argues against any near-term restocking of heavy machinery.
The Cheat Sheet
- Top Theme: China’s demand is contracting again, and the tariff deal has not changed that yet.
- Stock to Watch: BHP, where the combination of a weak PMI, two-year iron ore lows, and a supply-heavy Q4 creates the clearest pressure point.
- Sector to Watch: Materials and industrials, the two groups most directly geared to Chinese factory demand.
- Biggest Risk: A Monday gap-down in miners that spreads to broader commodity equities if Beijing offers no stimulus response before markets open.
- One Thing to Remember: When both manufacturing and non-manufacturing dip below 50, investors tend to treat it as a broader warning on near-term demand, not just a factory-sector problem. Position size accordingly.