Hey there, bargain hunter. Everyone keeps pitching AutoZone as the recession-proof, fix-it-yourself play for a consumer under pressure. That story is mostly right. But it is already stale. The more interesting thing happening at AZO right now is a structural pivot that quietly outran the DIY angle this year.
Scoreboard
AutoZone closed fiscal 2026 with $20.3 billion in annual sales, up 7.4% year over year. Full-year EPS came in at $152.55, a 5.3% gain. Q4 EPS of $56.05 beat the consensus estimate of $54.54 by 2.8%, though net sales of $6.6 billion missed the Street by 1.4%. Gross margin in Q4 expanded 182 basis points to 53.3%, helped materially by a $96 million tariff refund. Operating profit rose 10.1% to $1.3 billion. The stock trades around $3,253, at a trailing P/E of roughly 21x and a forward P/E near 18.8x.
The Real Reason This Stock Deserves a Second Look
The standard pitch is that when consumers tighten up, they fix the old car instead of buying a new one. That holds. Circana data shows U.S. automotive hand tool sales grew 3.2% in the 12 months through March 2026, a leading indicator of DIY engagement. But DIY traffic at AutoZone actually ran negative through parts of fiscal 2026. Transaction counts slowed as the year progressed.
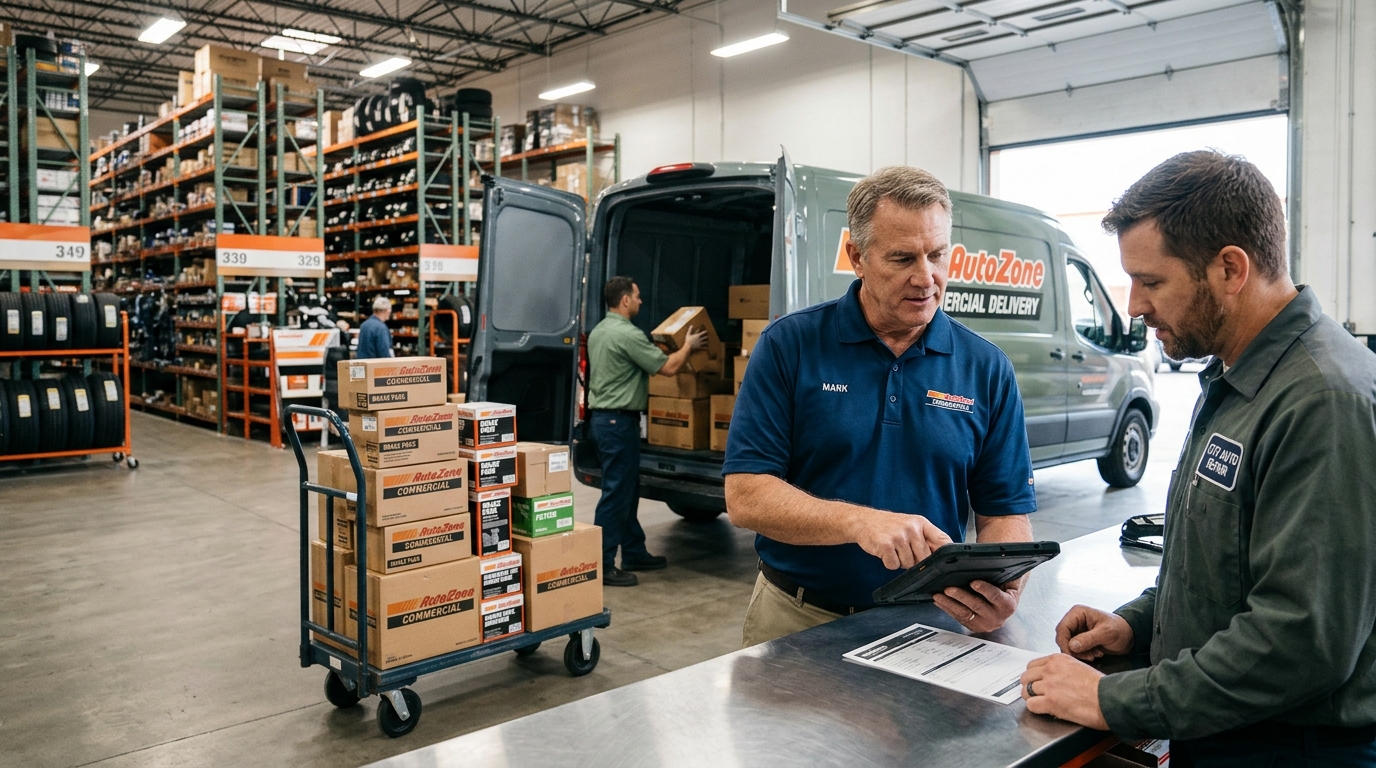
What carried the number was commercial. Domestic commercial sales grew 10.6% for the full fiscal year and 8.6% in Q4 alone. Commercial now sits at about 34% of domestic revenue. AutoZone has said it is still roughly 5% of the commercial share opportunity. That gap is the real investment case.
What the Business Actually Is Now
AutoZone still serves weekend DIY customers, but professional repair shops, fleet operators, and national service accounts are the volume driver. The company opened 374 new stores in fiscal 2026, crossing 8,000 locations globally, and plans approximately 400 more in fiscal 2027. Hub and Mega Hub expansion supports faster parts delivery to commercial accounts. In an October 2026 initiation note reported by Benzinga, BofA Securities analyst Christopher Nardone highlighted AutoZone and O’Reilly as well-positioned for the commercial opportunity and projected 10-12% annual commercial sales growth over the next three years.
Data That Matters
- FY2026 revenue: $20.3B (+7.4%)
- Full-year EPS: $152.55 (+5.3%)
- Operating cash flow: $3.25B
- Domestic commercial sales growth FY2026: +10.6%
- Store count: 8,031 globally
- Q4 gross margin: 53.3% (+182 bps)
- FY2027 guidance: flat to low single-digit same-store sales, ~400 new stores
- CFO departure: Jamere Jackson exits November 25, 2026, to join FedEx
Is It Cheap?
At 21x trailing and 18.8x forward earnings, AZO trades modestly above its 10-year median P/E of roughly 18.9x. That is not distressed. But the forward multiple reflects guidance that management itself called conservative: flat to low single-digit domestic comps against a backdrop where commercial is the growth engine. If commercial holds double-digit growth and new store productivity stays on track, 18.8x forward looks undemanding. The CFO exit adds short-term uncertainty the business does not necessarily deserve.
Bull / Base / Bear
Bull: Commercial comps hold above 10%, new store openings hit 400, and DIY traffic stabilizes as consumer wallets recover modestly. Forward earnings push toward $175, making today’s price look cheap in two years.
Base: Commercial grows 8-10%, DIY stays flat, margins hold near 53%. EPS growth of 7-9% annually. The stock drifts toward the analyst consensus price target near $3,666.
Bear: Consumer stress deepens, DIY traffic stays negative, and tariff tailwinds reverse. Operating deleverage bites harder than guided. The CFO transition disrupts capital allocation discipline mid-cycle.
Action Plan
The CFO noise is real but temporary. Use any additional softness tied to that headline as an entry point. Scale in at current levels with a second tranche if the stock revisits $3,100 or below. Watch the Q1 FY2027 results, expected around December 8, 2026, for whether domestic commercial comps hold above 8% and whether DIY traffic turns positive.
Cheap Investor Checklist
- Commercial same-store sales: must stay above 8% quarterly
- DIY traffic counts: watch for a return to positive
- Gross margin: hold near 53% without tariff refund tailwind
- New store openings: 400 target for FY2027 is the floor
- CFO successor named: timing matters for capital allocation clarity
- Forward P/E vs. O’Reilly: AZO should trade at parity or tighter
- Operating cash flow: $3.25B run rate must be sustained
Bottom Line
If commercial sales hold double-digit growth and the CFO transition is clean, AZO at 18.8x forward earnings is a reasonable price for a compounder. If DIY traffic deteriorates further and the new CFO alters the buyback cadence, the multiple compresses. Watch December 8, 2026.