From the man who tabbed NVIDIA before it soared 6,271%
over 7 years at its peak
Wall Street’s Hottest Stock Has a Waiting List. Here’s How to Skip It.
Wealthy investors are lining up for Anthropic shares and coming up empty. Tech Visionary, Matt McCall, says you can get into a backdoor opportunity today for less than $100 a share.
Anthropic, the company behind Claude, is set to go public at a record $2 trillion valuation.
It could top SpaceX as the biggest IPO in history.
And right now, almost nobody can buy a single share.
One Wall Street broker, whose firm trades about 1,000 private stocks, told TechCrunch:
“The hardest stock to source in our marketplace is Anthropic. There’s just no sellers.”
Even Goldman Sachs is charging clients 15% to 20% of their profits just for a way in.
The Line Is Out the Door
Meanwhile, people who already own a piece of Anthropic are holding on tight.
While everyone else is stuck in line. Even wealthy investors are struggling to get shares.
And it’s all leading to the most anticipated IPO in history.
When Anthropic finally goes public, millions of regular folks will rush to buy whatever they can get.
But tech legend Matt McCall isn’t getting in line.
“Most people are going to wait for Anthropic to go public and then buy as many shares as possible,” he says. “But I think that’s a huge mistake.”
Who Is Matt McCall?
There is a short list of analysts in America who were early on the AI boom.
Matt McCall is one of them.
He’s the Head Innovation Strategist at Monument Traders Alliance and editor of The McCall Innovation Report.
Over the past two decades, McCall has written about 50 stocks that went on to peak gains of 1,000% or more. Including:
- Tesla, before it climbed as high as 3,129%
- NVIDIA, before it soared a peak 6,271% in 7 years
- AMD, which he singled out in 2009
That’s why people call him “Mr. 1,000%.”
On March 6, 2009, McCall went on FOX Business and gave away nine stocks. One was AMD, trading around two dollars. By 2026 it rose 25,000%, enough to turn a $5,000 stake into more than $1.28 million.
No Waiting List Required
McCall’s play isn’t Anthropic. It’s a stock linked to Anthropic that you can buy right now in a regular brokerage account.
No waiting list. No special broker. No fighting Wall Street for scraps.
He calls it a “Second IPO.”
It may sound too good to be true. But it has happened before.
When Rivian went public in 2021, Ford owned a 12% stake. In the six months around Rivian’s IPO, Ford shares roughly doubled.
Yahoo quietly built a huge stake in Alibaba. In the two years around Alibaba’s IPO, Yahoo shares could have tripled your money.
It happened again shortly after EchoStar acquired $8.5 billion in SpaceX shares. In the months leading up to the SpaceX IPO, its shares soared 600%.
Now it’s happening again!
Anthropic’s “Silent Partner”
Years before the IPO frenzy, a much smaller firm took a $100 million stake in Anthropic. It beat Apple, NVIDIA, Amazon and Google to the punch.
Today, the entire company is valued at less than $15 billion. That’s 100x smaller than Anthropic.
McCall believes its early stake could cause it to double or triple in the years ahead.
And you can buy it for less than $100 a share.
We sat McCall down in front of our cameras to get the whole story. He even gave away the name and ticker.
For the time being, you can watch it free.
|
“If history repeats… investors could double or triple their money in the years ahead.” – Matt McCall
APTV Is Down 50%. Its Executives Are Buying.
Market Snapshot
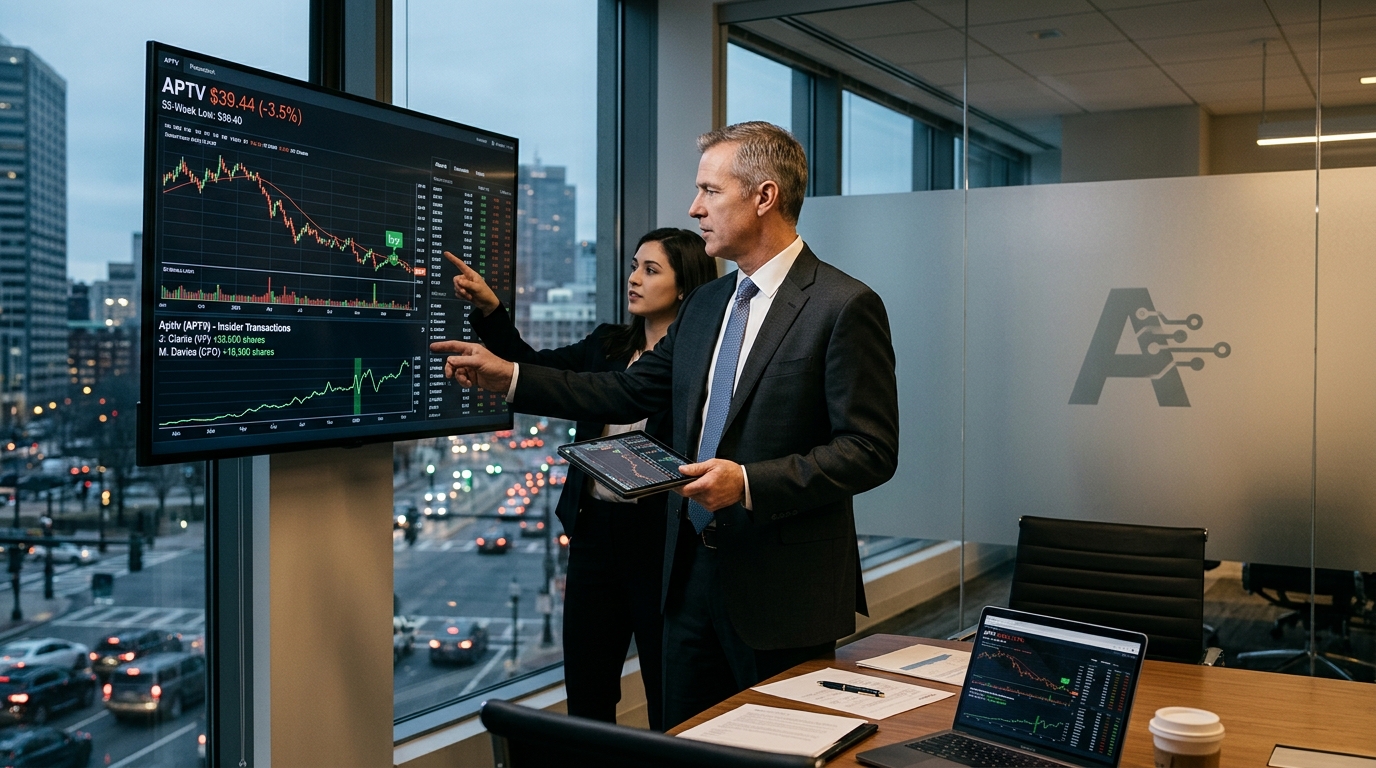
Aptiv closed Friday at $39.44, down about 3.5% on the session. The stock has traded between a 52-week high of $88.93 and a low of about $39.40, leaving it roughly 56% off its peak with no technical floor in sight. With a market cap of roughly $8.3 billion, it remains more than 50% below its 52-week high. VIX remains elevated; Aptiv is amplifying every broad-market down day.
Stocks in Focus: APTV
What happened. Aptiv beat third-quarter estimates but issued forward guidance that disappointed investors. The crux of the selloff was Q4 2026 guidance: the company projected adjusted EPS in a range of $1.35 to $1.55, with a midpoint of $1.45 that sits roughly $0.16 to $0.17 below analyst consensus.
Why it matters. The selloff punishes the guidance miss, not the underlying business. Q3 revenue reached about $3.2 billion, up 2%, driven by a 16% increase in nonautomotive markets. Aptiv said it secured roughly $4 billion in new business awards in Q3, bringing the year-to-date total to more than $13 billion, with China bookings growth of 30% and non-automotive awards of $3.8 billion, more than double the year-ago level. Those bookings convert into revenue over multi-year vehicle and industrial programs. The market is pricing the near-term miss; it is not pricing the backlog.
The insider signal. Insider activity has been notably positive over recent months, but the exact dollar total varies by tracker and time window, and it is not accurate to state there has been no insider selling without specifying the source and period. Executives are deploying real capital at prices they clearly consider dislocated. GF Value currently places Aptiv below its estimated intrinsic value, but that figure is a third-party model estimate, not a company figure.
What to watch. Management flagged roughly $700 million in anticipated 2027 semiconductor and memory-related inflation. That is the legitimate risk embedded in next year’s cost structure. Against it: management said the company repurchased more than $230 million of stock in Q3, bringing the year-to-date total to more than $550 million, and plans to repurchase at least $650 million by year-end, returning 100% of free cash flow to shareholders. Buybacks at these prices are mathematically accretive.
Sector Watch
Traditional auto suppliers are under uniform pressure from European production declines and Chinese OEM market-share gains. Aptiv’s bet is that the category itself expands. Management has highlighted accelerating non-automotive awards, including in adjacent industrial markets. The company has discussed a long-term goal of building a larger non-automotive mix by 2030. If that mix shift happens even partially on schedule, the current valuation looks like a structural mispricing, not a value trap.
Risk Radar
- 2027 memory inflation: roughly $700 million in flagged semiconductor cost pressure is not trivial at current margins.
- Analyst target compression: Morgan Stanley lowered its price target to $45 from $55. Citigroup maintained its Buy but lowered its target from $77 to $68. Multiple target reductions in one week suppresses sentiment even when the Buy ratings hold.
- Institutional exit risk: Some commentary has circulated about large holders trimming or exiting after Q3. Treat this as unconfirmed unless you can tie it to a specific filing or manager letter.
The Cheat Sheet
- Top theme: Auto supplier selloff has pushed APTV to levels where management is buying while the company builds a non-automotive revenue base the market is not yet pricing.
- Stock to watch: APTV. The gap between insider conviction and market price is at its widest point in over a year.
- Sector to watch: Industrial technology, specifically the intersection of automotive hardware expertise and robotics.
- Biggest risk: Memory and semiconductor inflation in 2027 compresses margins before non-automotive revenue scales enough to offset it.
- One thing to remember: Executive buying near 52-week lows is a stronger signal than most headlines, but it is not a guarantee. The more-than-$13 billion year-to-date bookings figure suggests the order pipeline is still there even if the near-term guide is not.