September 21, 2026
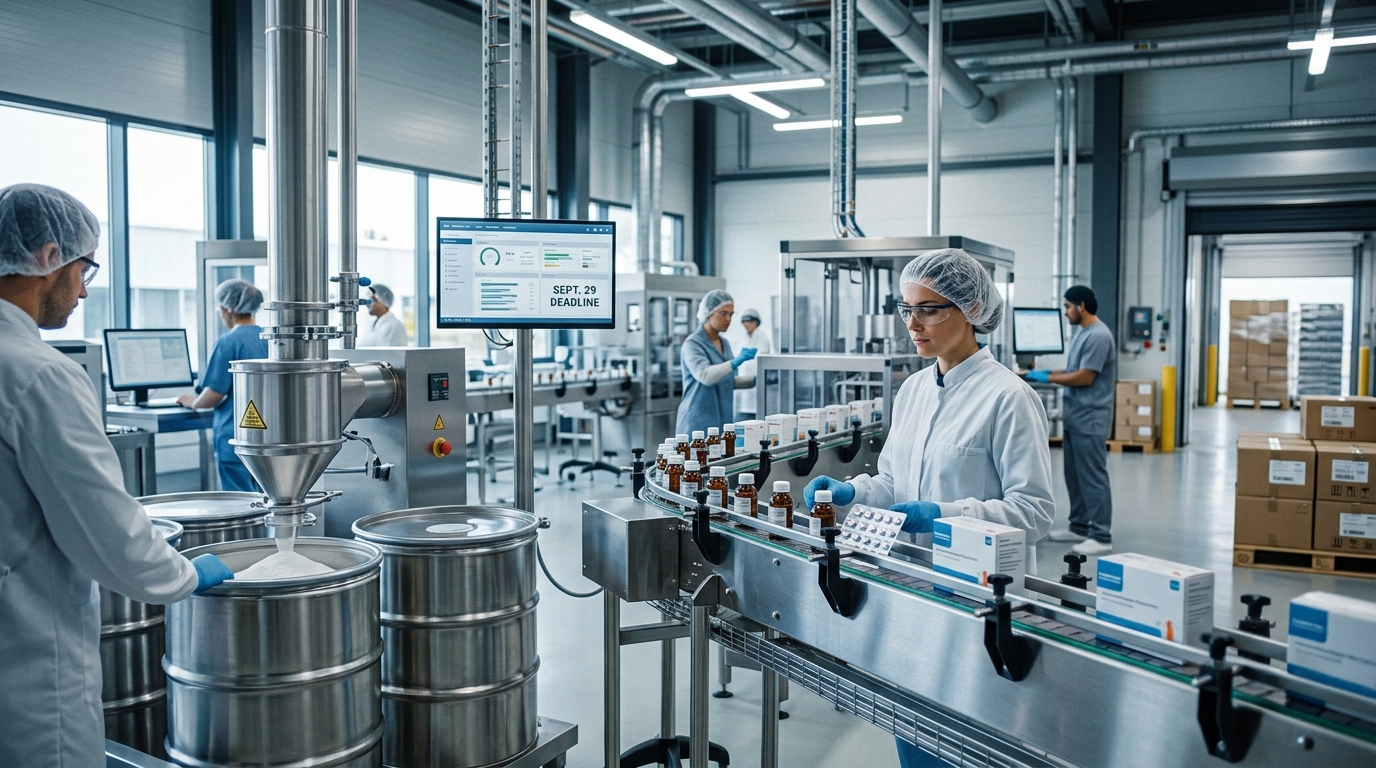
With Section 232’s Sept. 29 deadline near, Patheon collects contracts
When Proclamation 11020 landed on April 2, the pharmaceutical industry got a structural jolt, not a temporary headache. The proclamation imposes a 100% ad valorem tariff on imports of patented pharmaceutical products and their active pharmaceutical ingredients, effective July 31, 2026 for companies listed in Annex III and September 29, 2026 for other companies. The first wave already hit. The second arrives Tuesday, September 29, 2026.
Trump Takes on Foreign “Cartel” (and You Could Profit)
Trump is finishing a 25-year battle against a foreign “cartel.” And a single ticker is handing investors the chance at payouts like $8,704 in six days from the fallout.
What the Rate Map Looks Like
The standard Section 232 tariff rate for covered patented pharmaceuticals and associated ingredients is 100%. Companies with Commerce-approved onshoring plans can qualify for a 20% rate, and companies that have fully executed, or are negotiating, MFN pricing and onshoring agreements with HHS and Commerce can qualify for a 0% rate until January 20, 2029. Separately, the proclamation also establishes a 15% rate for products of Japan, the European Union, the Republic of Korea, and Switzerland and Liechtenstein jointly, unless a lower rate applies, and a 10% rate for products of the United Kingdom that could later be reduced under a future agreement.
The onshoring application window is shut. A Commerce notice requested applications by June 12, 2026. Companies working without an approved pathway when the September 29 clock runs out face the 100% rate for covered imports.
The Commerce Department’s investigation, citing FDA data, found that approximately 53% of patented pharmaceutical products distributed domestically are produced outside the country. That is the vulnerability the tariff regime is designed to eliminate, and it explains why the policy is calibrated to last years, not months.
Thermo Fisher’s Position in the Reshuffle
Thermo Fisher Scientific has repeatedly told investors it is well positioned to benefit from U.S. policy pushing drug manufacturing back onshore, as large pharma companies expand domestic capacity and look for near-term workarounds.
JPMorgan says gold is headed to $6,300. Bank of America says $8,000. But gold recently dropped over $500.
A former hedge fund manager says there’s a way to profit from gold’s wild moves without buying or selling a single ounce.
He calls it “Gold Skimming.” And now he’s revealing the full strategy for the first time.
At the Morgan Stanley 24th Annual Global Healthcare Conference on September 15, CEO Marc Casper laid out how that advantage translates into revenue. He described a near-term first phase centered on U.S. CDMO contracts, where customers can commit to domestic production through contract development and manufacturing organizations without building new plants, and he said Thermo Fisher has already won contracts in that area.
Expansion of existing sites is the second phase, with customers expected to buy more equipment and lab supplies as projects move forward. New greenfield manufacturing sites represent the third phase, driving additional equipment and inventory demand later in the cycle. The contract activity happening right now is the earliest and most immediate expression of that multi-year arc.
Casper told investors Thermo Fisher got back to 5% organic growth in the second quarter, its strongest organic growth rate since 2021, while adjusted EPS increased 13% in the quarter. Full-year expectations reflect that momentum. As of the latest update, Thermo Fisher expects full-year 2026 revenue of between $47.4 billion and $48.1 billion. In its first-quarter report, Thermo Fisher said revenue for the quarter ended March 28 was $11.01 billion, up 6% from $10.36 billion in the same quarter last year, above the consensus estimate of about $10.86 billion.
What Could Go Wrong
TMO is not a pure tariff play. End markets in academic and government segments remained weak, and diagnostics declined mid-single digits in Q1.
The CDMO contracts Casper referenced are only the opening act. Tech transfers require validated processes, and any manufacturing site change must clear FDA before commercial production can begin. Casper himself placed the larger revenue contribution from reshoring in 2027 and 2028, not this quarter. Signing a contract is not the same as running a compliant production line.
5 Little-Known Stocks Behind Today’s Defense Tech Shift
Behind the headlines, a major transformation is underway.
Modern warfare is being driven by AI, autonomous systems, and next generation technology. A handful of lesser known companies are helping power this shift.
This report uncovers five stocks quietly playing a critical role in the future of defense.
Companies that secured MFN and onshoring agreements before the June 12 application deadline also get breathing room. The zero-rate pathway removes urgency for that cohort, narrowing the addressable pool of immediate CDMO demand. The remaining universe is still substantial, just not the entire global patented drug market.
The Longer Timeline
The September 29 deadline is a hinge, not an endpoint. Section 232 introduces a staged tariff regime: 100% default for covered patented drugs and APIs, reduced 20% with approved onshoring plans, and temporary 0% if paired with MFN pricing until January 20, 2029. Every company operating at the 20% rate is still on a clock to build or contract domestic capacity before that rate resets to 100% on April 2, 2030.
Thermo Fisher’s pharma services business, through its Patheon division, runs one of the world’s largest CDMO networks, with FDA-registered U.S. sites spanning oral solids, sterile injectables, biologics fill-finish, and cell and gene therapy. That is not something a competitor assembles in a quarter. It took decades to build, and right now that existing footprint is precisely what multinational drugmakers need when they cannot wait for a new plant.
Stock to Watch: TMO. Sector to Watch: Pharma services and CDMOs. Key Risk: Execution lag between contract signing and validated commercial output. Key Opportunity: Multi-year equipment, lab supply, and manufacturing demand as companies move through all three reshoring phases into 2028.