Hi Trader,
Most “gurus” who teach beginners how to trade options start in the wrong place…
Because they immediately launch into complicated concepts like Greeks, spreads, and implied volatility.
And before long, most new traders are completely lost… and move on.
The free guide I want to share with you today takes a different approach.
Instead of overwhelming you with technical details…
It starts with the basics and shows you exactly how options work, why traders use them, and how they can fit into a simple trading plan.
If you’ve ever wanted to understand options but didn’t know where to start…
This is your chance.
Click here and get your free copy now.
To your trading success,
Dave Aquino
Lead Options Trader, Base Camp Trading
GD Holds 2.5 Years of Revenue in Backlog. Q3 Decides if It Converts.
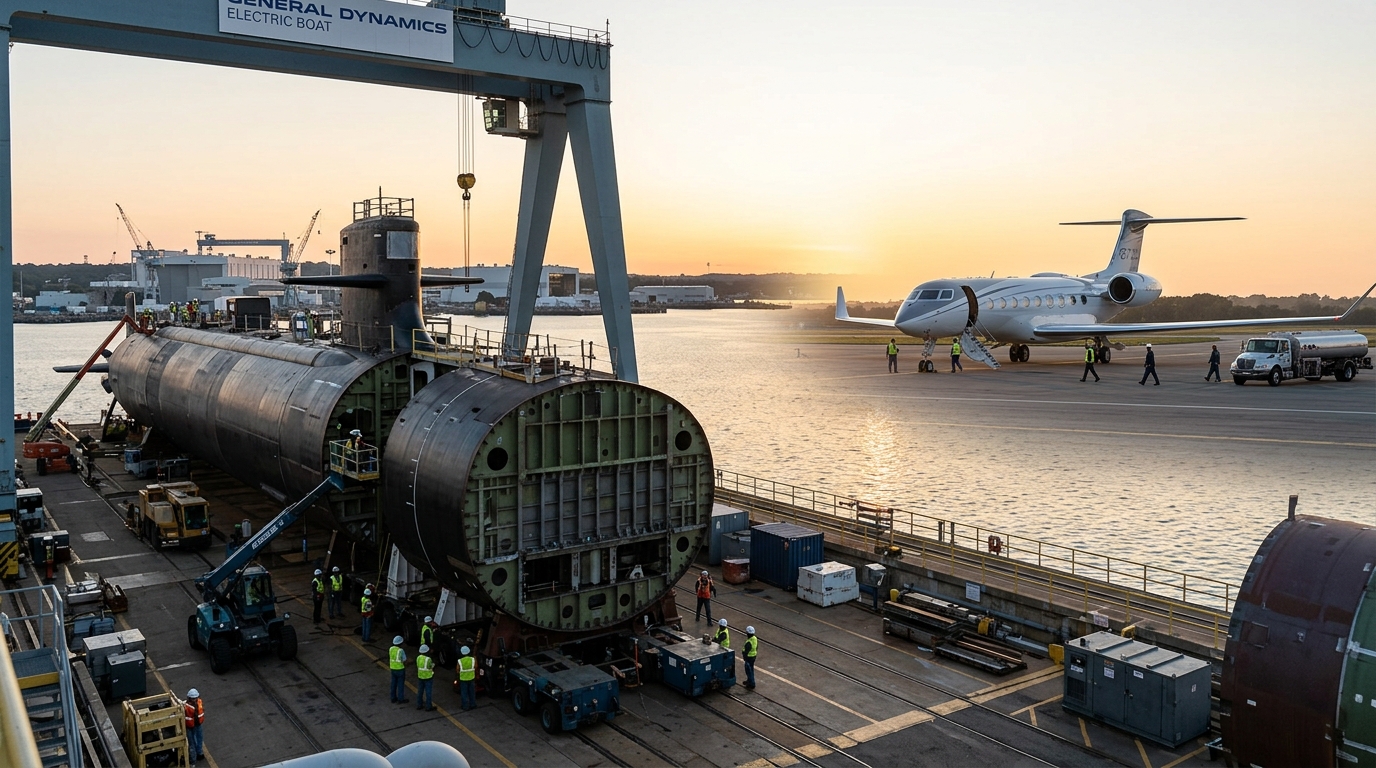
Two catalysts landed on the same trading day, July 29, 2026. General Dynamics reported Q2 earnings that beat consensus by $0.28 on diluted EPS of $4.24, up 13.4% year-over-year. Separately, Electric Boat was part of a Navy package totaling $76.6 billion that included $29.5 billion for five Columbia-class submarines and $42.1 billion for nine Virginia-class submarines. The stock moved sideways. That tells you something useful: the market is not debating whether demand exists. It is debating whether GD can actually ship fast enough to justify a premium.
Market Snapshot
Defense names have benefited from a rate environment that rewards long-duration revenue visibility. Multi-year government contracts do exactly that, and GD’s raised full-year guidance of roughly $55.7 billion in revenue with EPS of $16.80 to $16.90 gives traders a clear anchor. At roughly 21 times forward earnings against a backlog representing nearly 2.5 years of current revenue, the valuation math works only if throughput trends hold. GD closed at $343.39 on September 22, 2026. Bernstein has a $407 price target. GD’s Q3 earnings date has not been formally confirmed by the company as of September 24, 2026.
Stocks in Focus: GD
- Q2 headline numbers: Revenue $14.1B, up 8.1%; diluted EPS $4.24, up 13.4%; operating margin 10.4%, up 40 basis points year-over-year.
- Backlog: Record $136.5B at quarter-end, up 32% year-over-year; company-wide book-to-bill 1.4-to-1; total estimated contract value including options and IDIQ work at $186.9B.
- Electric Boat contracts: $29.5B for five Columbia-class and $42.1B for nine Virginia-class submarines, part of the Navy’s $76.6B package announced July 29, 2026.
- Aerospace: $3.5B in revenue, up 15.1%; 41 aircraft delivered; operating earnings $510M, up 26.6%; margin 14.5%; Aerospace backlog $24.0B, up year-over-year.
- Marine Systems: $4.7B in revenue, up 10.4%; operating earnings $342M, up 17.5%.
- Combat Systems: Book-to-bill of 2.1-to-1, the strongest across all segments, driven by allied armored vehicle orders including Canadian Armed Forces contracts.
- Cash: Operating cash flow exceeded $4B in the first half; quarterly dividend $1.59 per share, with an ex-date of October 9, 2026.
Sector Watch
Defense and aerospace are absorbing capital in ways that most other sectors cannot compete with right now. Single-source supplier constraints remain the principal bottleneck, and the Navy’s pending Block VI Virginia-class award would add further demand certainty once finalized.
Gulfstream is the cleaner story. Orders in the first half of 2026 were the strongest for the Aerospace segment since 2022, with a 1.5-to-1 book-to-bill in Q2.
Technical Radar
GD peaked near $380 on the Q2 earnings day, then gave back ground through September. The stock settled near $343 on September 22. Watch $340 as near-term support; a clean hold there keeps the consolidation range intact ahead of Q3 earnings. Analyst consensus and the 52-week range depend on the data vendor and the date pulled.
Risk Radar
- Marine margin compression: Operating margin at 7.3% is the segment constraint. Columbia and Virginia-class production ramp dilutes consolidated margins even as revenue accelerates. A slip below 7% in Q3 would pressure the multiple.
- Gulfstream completions: Supply chain stabilization is ongoing but not complete. A delivery shortfall against the roughly 160-aircraft full-year target is the swing variable for Aerospace EPS contribution.
- Execution at scale: The July submarine awards lock in demand. The question is whether the industrial base, single-source suppliers included, can match that commitment with production cadence.
The Cheat Sheet
- Top Market Theme: Record defense backlog meets a capacity ceiling; execution data, not order volume, moves GD’s multiple from here.
- Stock to Watch: GD into Q3 earnings; Marine Systems margin is the number that matters most.
- Sector to Watch: Defense and shipbuilding; NATO spending commitments are converting into funded contracts at a pace not seen in a generation.
- Biggest Risk: A Marine margin miss or Gulfstream delivery shortfall compresses full-year EPS toward the low end of guidance and resets price targets downward.
- Biggest Opportunity: A record backlog paired with any credible evidence that throughput is accelerating.
- One Thing to Remember: The orders are not the trade. The trade is whether Q3 throughput data confirms the bull thesis or invites a re-rating toward sector average multiples near 19 times forward earnings.