September 24, 2026
Bonus Content: TJX Turned Tariff Turbulence Into a Buying Spree
Gold and copper prices are rising fast. That’s a fact that’s impossible to ignore.
What many people are missing is that the opportunity to gain early exposure to companies exploring for these metals in Tier-1 jurisdictions may not last forever.
That’s where one little-known Canadian explorer comes into play. It has a small market cap and low share price alongside a strong treasury and major-company-funded drilling underway now in two premier Australian mineral belts.
Successful drilling could bring greater market attention to the copper-gold potential the company is targeting across its portfolio.
Access our brand-new FREE report to get the full story.
Inside, you’ll learn the company’s name and ticker symbol, explore its Australian project portfolio, and get the latest on drilling now underway.
Access the report by clicking here and learn just why this overlooked copper-gold explorer is well-positioned for significant upside.
TJX Turned Tariff Turbulence Into a Buying Spree
The conventional read on TJX Companies is straightforward: cost-conscious shoppers trade down, off-price wins. That part is true. But it understates what is actually happening inside TJX’s supply chain right now, and why the company’s earnings trajectory looks harder to interrupt than the simple trade-down story implies.
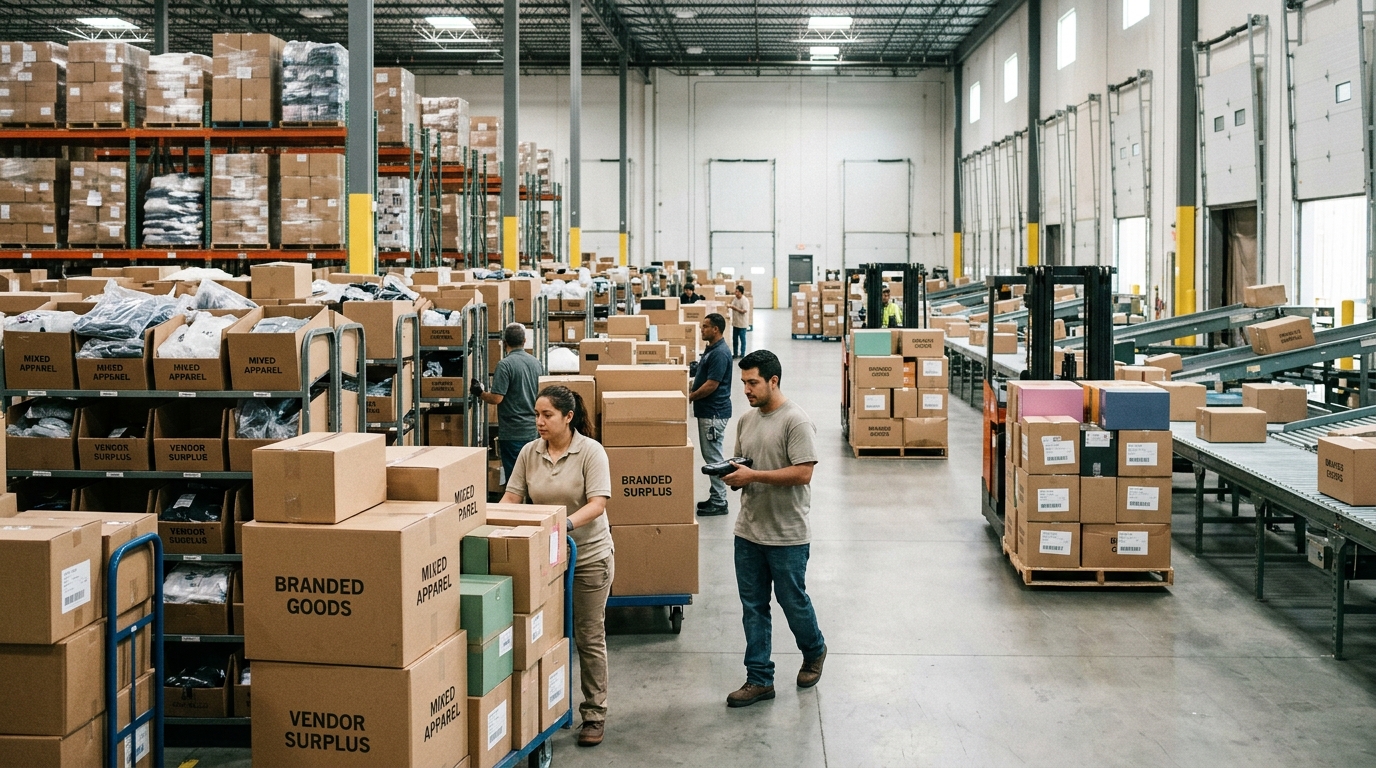
The mechanism is tariff-driven inventory dislocation. CEO Ernie Herrman told analysts that the threat of higher tariffs could prompt vendors and manufacturers to bring goods in early, creating a surplus of inventory TJX could acquire at advantageous prices. That surplus became fuel. With more than 1,300 buyers sourcing from over 21,000 vendors across more than 100 countries, TJX has become a critical channel for manufacturers looking to move excess goods. When supply chains seize up for everyone else, TJX’s buying network converts that chaos into cheaper cost of goods.
Herrman has also pointed to an “outstanding availability of quality, branded merchandise” in the marketplace, a direct signal of how TJX converts industry turbulence into margin protection. The fiscal results back that up. In the quarter ending May 2, 2026, net sales rose 9% year over year to $14.3 billion, comparable sales increased 6%, and diluted earnings per share jumped 29% to $1.19.
What matters for traders is not just the demand side of this equation. The consumer spending shift is well understood. Research from Deloitte has argued that value perceptions can matter more than price perceptions alone in driving purchase intent. TJX captures that shift through its domestic banners. But the supply-side edge is what lets margins expand at the same time traffic grows.
CFO John Klinger has said the company’s guidance assumes it can offset tariff pressures, and the Q1 FY27 results suggest that confidence is not misplaced. Klinger said the comparable sales gain was driven by both a higher average basket and an increase in customer transactions, meaning more shoppers coming in and spending more per visit.
The valuation is the honest complication. TJX’s forward price-to-earnings ratio has been quoted around 32, well above typical retail multiples, and the stock is not cheap. The valuation leaves little room for error: one quarter of disappointing comparable sales or unexpected margin pressure would likely push the stock lower. That is the risk traders carry into each earnings cycle.
The counterargument is structural. Brands like T.J. Maxx, Marshalls, and HomeGoods benefit directly when shoppers trade down from full-price department stores, and a softer consumer spending environment can actually strengthen TJX’s value proposition. The company has now built a model where macro headwinds strengthen both sides of its business simultaneously: more shoppers at the door and more brands willing to sell inventory cheap. That is not a cyclical trade. It is a compounding advantage, and at $60.4 billion in fiscal 2026 revenue, it is still accelerating.