September 25, 2026
Record bookings, 82% growth guidance, and a 160x multiple walking into Q3 earnings. One of those things has to give.
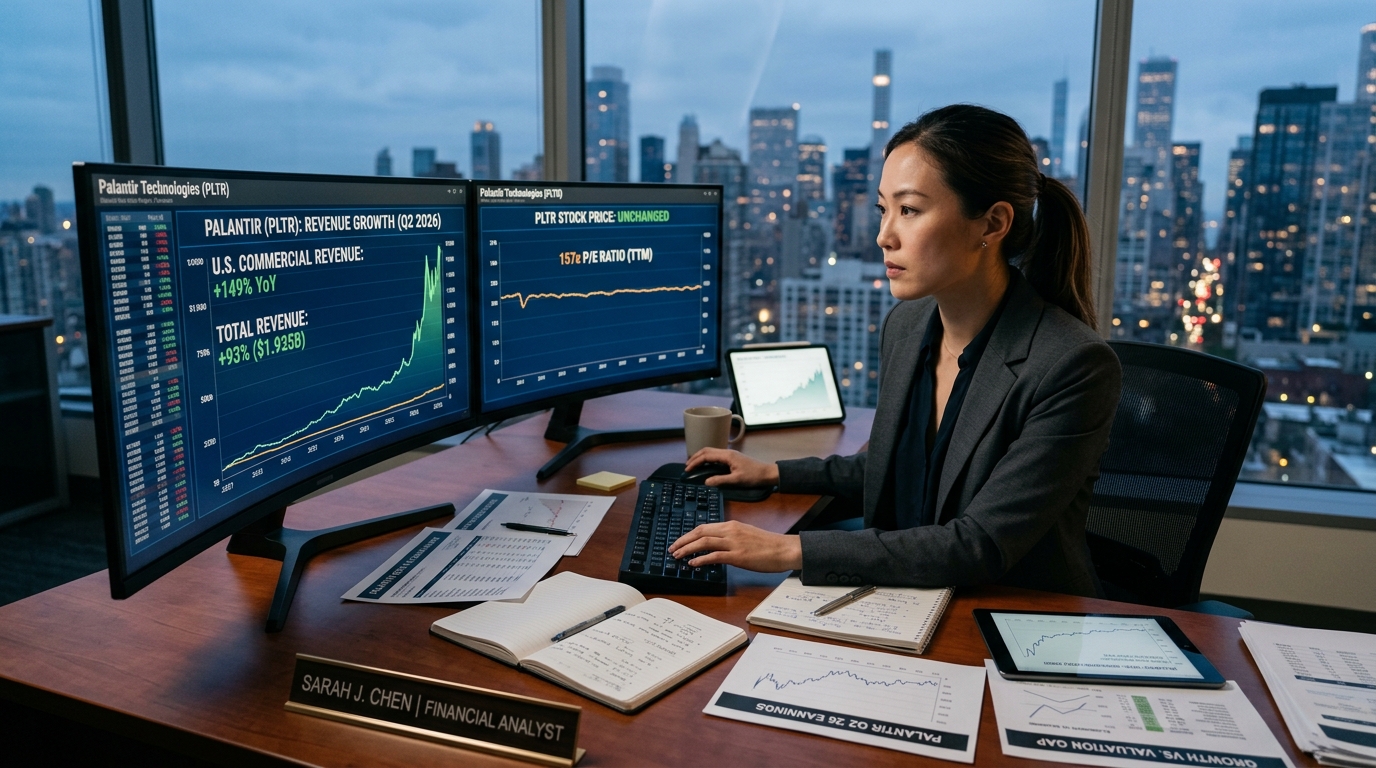
Palantir Technologies has spent 2026 posting numbers that most enterprise software companies would need a decade to approach. U.S. commercial revenue grew 149% year over year in the second quarter, and total quarterly revenue rose 93% to $1.935 billion, the fastest pace in company history. Then the stock went essentially nowhere. That divergence is the actual trade.
If You Had to Start Over Today with Just $500…Where Would You Put It?
Hey, Tim Sykes here.
I recently sat down with one of the most successful traders I know, he’s a $24 million trading legend.
And I asked him point blank – one simple question:
“If you had to start over today with just $500…where would you put it?”
What he said next blew me away.
This has nothing to do with AI or the Magnificent 7.
Click here to watch this free presentation now – before it’s too late
Palantir closed $2.132 billion in U.S. commercial total contract value in a single quarter, a record and a 153% jump from a year earlier, the clearest sign yet that enterprise buyers are committing to AI platforms at a scale and speed that outpaces most vendor projections. The deal count reinforced that point: the company closed 220 deals worth at least $1 million, record highs.
Management now targets 2026 revenues of $8.15 billion to $8.158 billion, representing 82% year-over-year growth and up from its prior forecast in the mid-$7 billions. Yet the stock trades near $192, roughly 7% below its November 3, 2025 all-time closing high of $207.18.
Some investors think Elon’s next move is hiding in plain sight
Most people dismissed the “xPhone” rumors immediately.
That’s probably why this setup caught my attention. According to recent SpaceX documents, Elon may be approaching the mobile market from a completely different angle than the crowd expects.
And fast movers are starting to notice.
The explanation sits in the valuation. Palantir carries a trailing price-to-earnings ratio in the mid-160s on GAAP figures, and a market cap around $460 billion as of September 24, 2026. The stock has traded sideways in 2026 despite strong financial results, primarily because investors are divided over its extremely rich valuation. Bears have a point: at roughly 160x trailing earnings, even a minor miss on Q3 guidance could reset the multiple sharply lower.
The bull case, however, is not just about domestic momentum. Only 26% of 2025 revenue came from customers outside the United States, which means the international commercial opportunity is largely untapped. Bain and Company expanded its lead global management consulting partnership with Palantir in March 2026 to route AIP deployments to its multinational client base. Palantir Technologies Japan has a strategic partnership with Fujitsu under which Foundry and AIP are incorporated into the data infrastructure supporting Fujitsu Uvance solutions. The company is also expanding into commercial use cases in legal, construction, and insurance, and deepening ties through Google Cloud integrations.
Average revenue from the top 20 customers grew 67% year over year to $124 million in the trailing twelve months ended June 30, 2026, which shows the expansion-within-existing-accounts engine is running. A substantial portion of Palantir’s commercial growth came from organizations already using its software. As customers add use cases, Palantir generates more revenue without repeating the full acquisition cycle, improving operating leverage and raising switching costs.
Inside the Nuclear Revival Reshaping Energy Markets
Governments worldwide are investing billions to revive a proven energy source. Supply chains are tightening, demand is rising, and select companies stand to benefit. The Nuclear’s Second Act report explains what’s happening next.
Morgan Stanley analyst Sanjit Singh has described Palantir as a strong setup heading into earnings, while Bank of America’s Mariana Perez Mora carries a $255 price target. The other side of that ledger: former fund manager Michael Burry has disclosed put positions tied to Palantir since fall 2025.
The heading into Q3 earnings is binary in a way few large-cap stocks achieve. The commercial acceleration is verifiable. The question is whether the market finally prices the international ramp, or decides the domestic run has already been reflected at roughly 160x.