If you still haven’t downloaded my “Simple Options Trading For Beginners” book…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge for this book, so do yourself a favor and download it now…
That way, no matter how much it is in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Simple Options Trading For Beginners << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of my “Simple Options Trading For Beginners” book to your computer before I start charging for it.
CoreWeave’s $1.1B Bond Deal Reveals the Cost of AI Debt
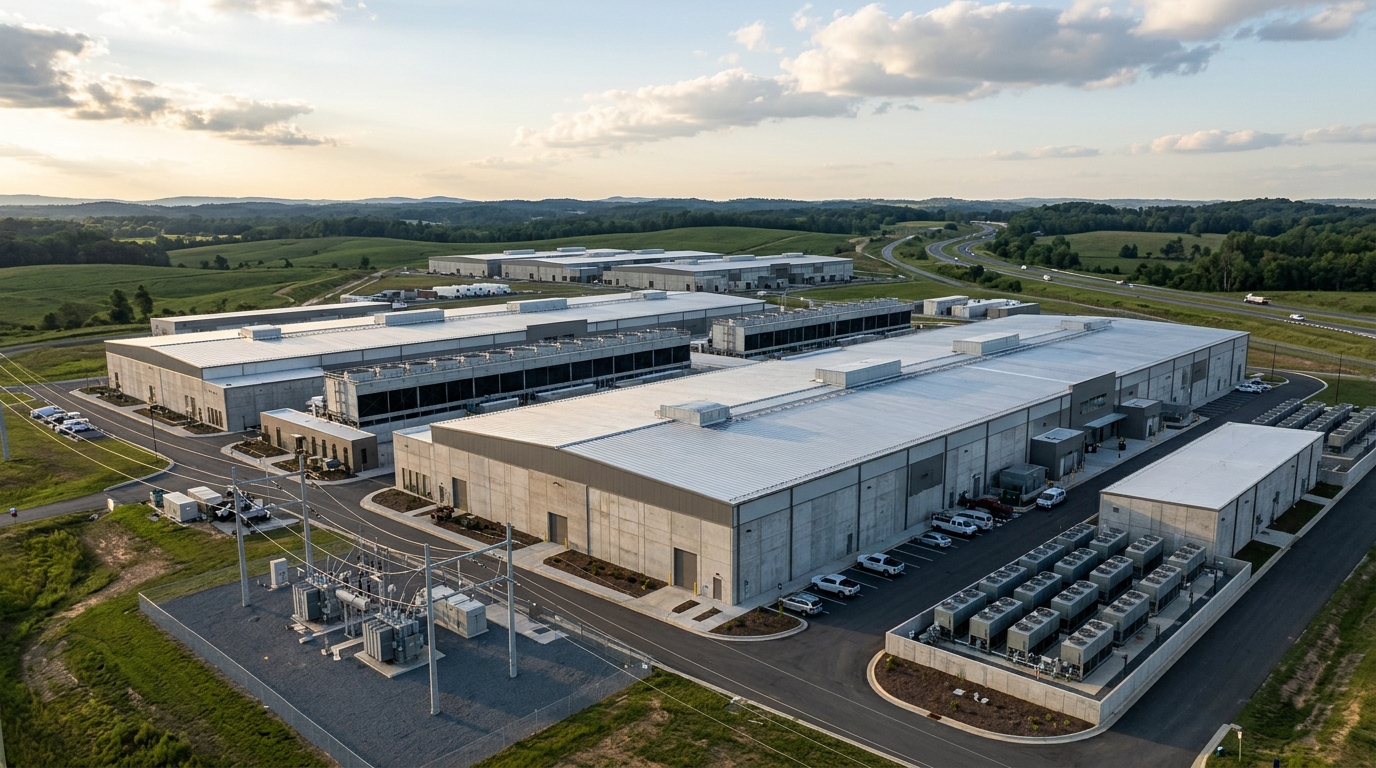
The number traders should carry into this week: 9.25%. That is the yield at which a Goldman Sachs-led syndicate placed $1.1 billion of junk bonds for a Blue Owl-sponsored data center campus near Richmond, Virginia, on Wednesday, September 23, 2026. The five-year notes were sold at about 98.5 cents on the dollar to yield 9.25%, roughly 2.7 percentage points above the average yield for similarly rated debt. That spread is not noise. It is the market’s real-time assessment of what speculative-grade AI infrastructure credit costs right now, landing as sovereign yields test multi-decade highs.
Market Snapshot
The 30-year Treasury yield touched 5.501%, a level not seen since June 2004. The benchmark 10-year yield touched 5.223%, levels not reached since June 2007. The long end has been moving fast on the back of stronger U.S. data, hawkish Fed tone, and firmer oil. Those moves are the backdrop against which this CoreWeave-linked deal landed. Borrowing at 9.25% looks different with the risk-free rate at multi-decade highs than it would in a calmer rate environment.
Stocks in Focus: CRWV, OWL, GS
The Digital Drive facility is designed for about 76 megawatts of IT capacity, and CoreWeave has signed a 15-year, $2.94 billion contract, which gives lenders a clear source of future rent once the site is running. The catch is the gap between now and then. Operations are not expected until 2027 to 2028, so bond buyers are underwriting a pre-revenue stretch where construction delays, cost overruns, or commissioning problems can derail the plan before the first contracted dollar arrives.
S&P Global Ratings assigned a BB- issue-level rating to the senior secured notes and a B+ issuer credit rating to the issuing entity. S&P highlighted the concentration risk in plain terms: the project’s exposure to a single, speculative-grade tenant remains the key risk. Blue Owl (OWL) structured the deal; Goldman (GS) led the syndicate. For CoreWeave (CRWV), every new financing at elevated rates raises the question of whether its long-term lease economics hold once debt service is fully accounted for across its expanding footprint.
Sector Watch: AI Infrastructure Credit
This financing joins a broader push to fund artificial intelligence infrastructure in the high-yield market, where investors have been demanding richer coupons to bankroll new construction, especially when the tenant is not investment grade. The pattern is becoming consistent in the sense that deals are coming with high single-digit to low double-digit yields.
But the comparison point matters. Reporting earlier this summer said Galaxy Digital was pitching a roughly $3.5 billion debut junk-bond sale tied to a CoreWeave lease at about a 9% yield, not that it completed a $3.5 billion offering at a 10% yield. Two data points is not a trend, but the direction is the message: the market is demanding a meaningfully higher cost of money to fund single-tenant, construction-stage AI campuses than many investors became accustomed to in the last cycle.
If this bond sale clears easily, it strengthens the case that single-tenant data centers with long leases can be valued more like infrastructure: steady payments, long contracts, and financing that leans on one big customer. The stress test is whether that framing survives a rate environment where even the safest long-duration paper is under pressure.
The Cheat Sheet
- Top Theme: AI infrastructure debt is pricing as genuine credit risk, not as a proxy for investment-grade real estate. The roughly 270-basis-point pickup over peer-rated paper is the market saying so explicitly.
- Stock to Watch: CRWV. The 9.25% deal yield puts a live cost of capital on its leased-campus model ahead of the 2027 to 2028 operational window.
- Sector to Watch: High-yield data center credit. Each successive deal sets the clearing rate for the next. Watch whether future offerings tighten or widen from here.
- Biggest Risk: Rate path uncertainty into the late-October FOMC meeting. As of late September 2026, CME FedWatch-style pricing has implied a meaningful chance of another 25 bp hike, but with the larger probability still on a hold. Any further upward shock in long-end yields compresses the economics of pre-revenue AI projects already in the financing queue.
- One Thing to Remember: A 9.25% yield on a fully pre-leased, 15-year AI campus deal is not a distress signal for one company. It is the current market price for single-tenant, speculative-grade AI infrastructure debt. Any model that assumed cheaper financing should be updated now.