The insurance sector is running a rare double. Underwriting books are genuinely profitable, and the float those same books generate is compounding at Treasury yields that were unimaginable five years ago. The combination is not fragile, it is structural, and it is not over yet.
Market Snapshot
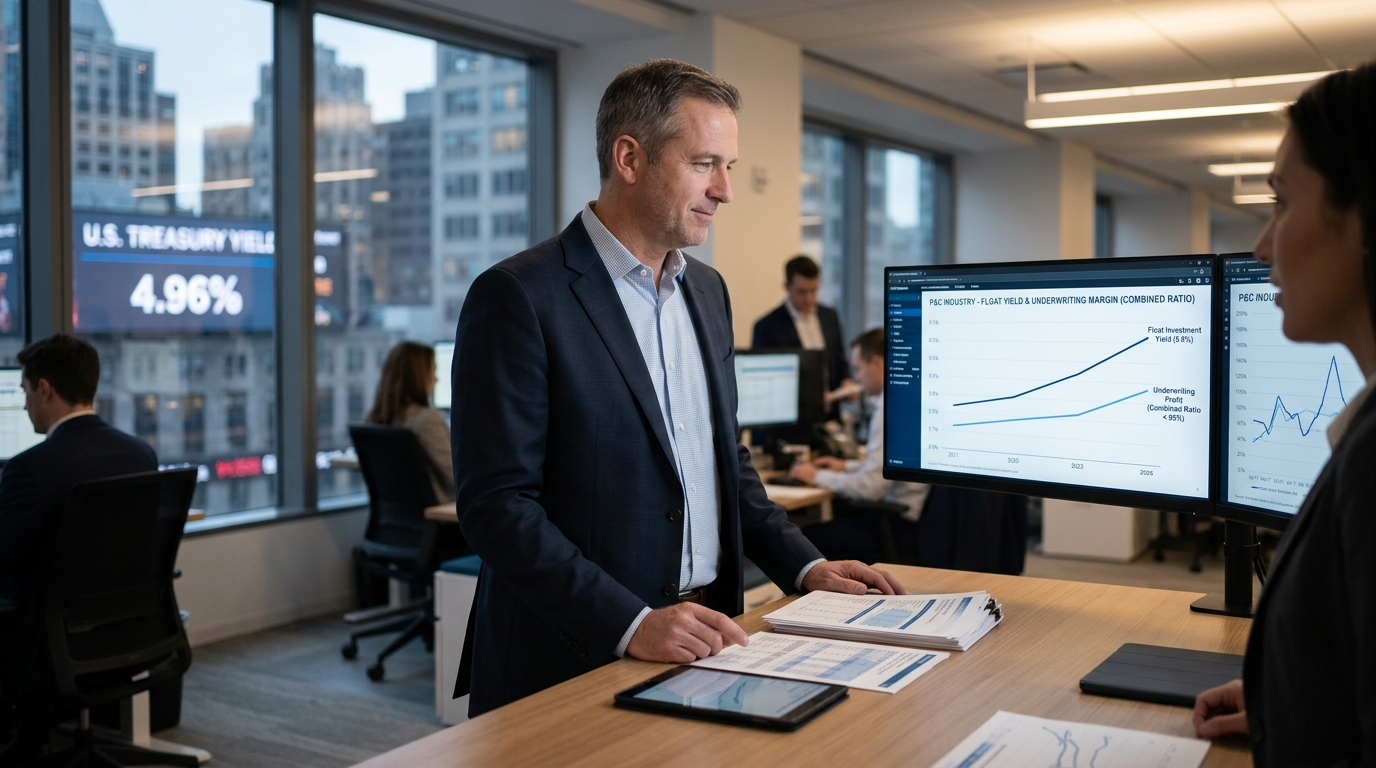
With the 10-year Treasury yield at about 4.96% as of September 22, P&C insurers are turning that tailwind into durable income: every quarter that bonds roll over, the float earns more. Meanwhile, the U.S. P&C industry posted an estimated net underwriting gain of $31.7 billion in H1 2026, more than double the $11.6 billion recorded in H1 2025. Policyholders’ surplus hit $1.30 trillion by midyear, and the industry’s combined ratio improved to 92.7 from 96.5 a year earlier.
Stocks in Focus
Travelers reported Q2 2026 core income of $10.04 per share. Net investment income rose 11% to $2.078 billion pre-tax, driven by a higher yield and growth in average invested assets. The consolidated combined ratio improved to 83.6% from 90.3% a year earlier.
Chubb reported Q2 2026 core operating earnings of $7.26 per share, with the bottom line up 18.2% year over year. Chubb’s record adjusted net investment income of $1.88 billion, up more than 11%, came from strong performance across its investment portfolios. Both engines, underwriting and float, hit record marks simultaneously.
Sector Watch
The cycle is softening unevenly. U.S. casualty lines including commercial auto continue to harden, reflecting social inflation and nuclear verdicts. Carriers with casualty-weighted books still have pricing power. Those leaning into commercial property face a different reality. Average commercial P&C premiums declined 1.2% in Q1 2026, the first overall decrease since Q3 2017, ending a 33-quarter streak of increases.
The transition from a hard to a soft market is one of the most strategically consequential periods in the insurance cycle. The question for the next two quarters is whether discipline holds as competitive pressure builds on property lines.
Catalyst Calendar
- Q3 earnings season (October): Travelers, Chubb, and Progressive will reveal whether H1 underwriting momentum extended through a relatively benign third quarter for catastrophes, or whether casualty reserve development turns adverse.
- Treasury refunding (October 29): When long rates stay high, the float earns more each quarter as bonds roll into higher yields. Any surprise dovish shift in rate guidance compresses the reinvestment advantage.
- Legal system abuse legislation: States such as Florida that enacted legal system abuse reforms have pointed to stabilizing conditions and insurer filings for rate decreases in parts of the market. More states adopting similar measures would meaningfully expand casualty margins.
Risk Radar
Verisk’s 2026 Global Modeled Catastrophe Losses Report indicates the industry faces approximately $171 billion in average annual insured catastrophe losses globally, with the U.S. accounting for about $117 billion. The H1 result benefited from an unusually quiet catastrophe period relative to last year’s California wildfires. A single major Atlantic hurricane landfall in Q3 reshapes the full-year picture fast.
Higher-for-longer interest rates are an important stabiliser, supporting investment income even as underwriting margins face pressure. That cushion thins if the Fed pivots more aggressively than currently priced. Margins are likely to deteriorate in both personal and commercial lines if persistent supply chain disruptions and labor shortages continue driving goods prices and wage inflation into claims costs.
The Cheat Sheet
- Top Market Theme: P&C insurers are simultaneously profitable on underwriting and compounding float at a 5% Treasury yield, a combination that does not depend on the economic cycle.
- Stock to Watch: Chubb (CB). The combined ratio of 83.8 and record adjusted net investment income of $1.88 billion represent the fullest expression of the dual-engine model.
- Sector to Watch: U.S. casualty lines, commercial auto and excess liability, where pricing is still hardening against the broader softening trend.
- Biggest Risk: A late-season catastrophe event or an adverse casualty reserve development in Q3 earnings that resets the H1 underwriting gain story before the market can finish pricing it in.
- Biggest Opportunity: The insurance industry is currently undervalued. A sector running 92.7 combined ratios with reinvestment yields near 5% is not a value trap, it is a valuation gap.
- One Thing to Remember: The float does not care about macro sentiment. It earns every quarter whether equity markets are risk-on or risk-off, and right now it earns at the highest reinvestment rates in over a decade.