The diesel crack spread closed at more than $100 per barrel in September. That number does not describe a transient spike. It describes a structural condition that the two largest U.S. refiners turned into the most profitable quarter in their histories, and the conditions generating it have not materially changed heading into Q3 earnings season.
Market Snapshot
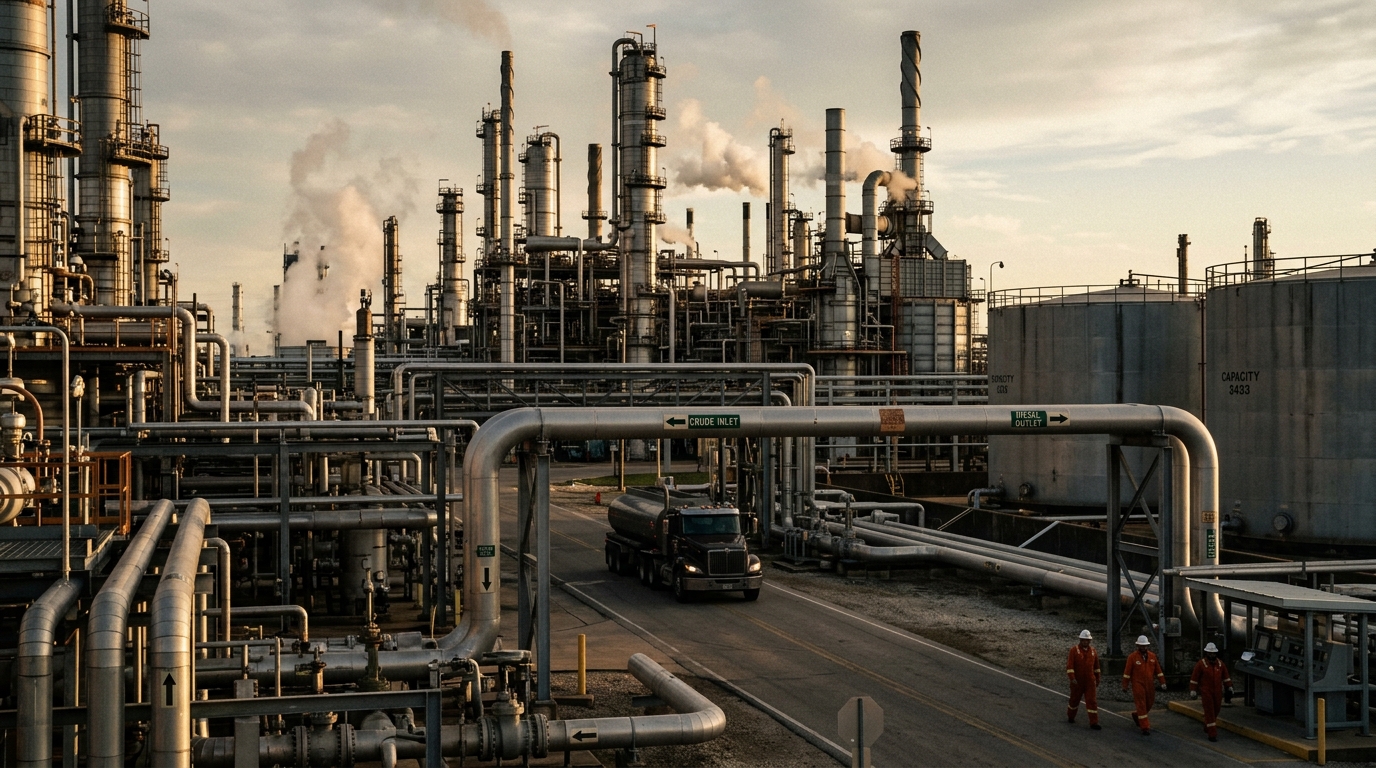
The refining trade is being driven by two forces operating simultaneously. Global refinery runs remain constrained, with Middle East export refineries still offline, Russian throughput curtailed by Ukrainian strikes, and Asian refiners running below normal utilization. At the same time, domestic capacity has been structurally trimmed: operable U.S. atmospheric distillation capacity fell to 18.2 million barrels per calendar day as of January 1, 2026, after LyondellBasell began decommissioning its Houston refinery in 2025 and Phillips 66 moved to cease operations at its Los Angeles-area refinery in the fourth quarter of 2025. Those two sites alone represented roughly 400,000 b/d of capacity.
The result is a domestic fleet running at the edge of its physical limits. Shell hit a record 102% utilization in Q2. Valero and Chevron both ran above 97%. When refineries operate above nameplate capacity, there is no slack to absorb an unplanned outage or a demand spike, which is exactly the kind of brittleness that keeps crack spreads elevated even as crude itself has pulled back from earlier peaks.
Stocks in Focus
Marathon Petroleum (MPC) is the clearest beneficiary. Its refining and marketing margin reached $36.33 per barrel in Q2 2026, more than double the $17.58 it earned a year earlier, and adjusted EBITDA for that segment jumped from $1.9 billion to $6.7 billion in a single year. Earnings per share came in at $17.73. The company then returned over $2.8 billion to shareholders in the quarter, with roughly $6 billion remaining on its share repurchase authorizations. MPC trades near $251. TD Cowen carries a $320 target.
The sourcing angle matters. CEO Maryann Mannen stated on the Q1 call that MPC is “largely insulated from global crude supply disruptions” because its barrels come almost entirely from the United States and Canada. That insulation converted a geopolitical shock into record cash generation rather than a feedstock cost problem.
Valero Energy (VLO) posted refining margin per barrel of $23.62 in Q2, up from $12.35 a year earlier, with segment operating income rising to about $4.5 billion from about $1.3 billion. Valero sent $2.6 billion to shareholders in the same quarter. A separate structural tailwind: European flows of gasoline into the United States are closed while Latin American demand pulls Gulf Coast product outward, leaving net gasoline imports down roughly 400,000 barrels per day and extending Valero’s regional pricing advantage. Q3 results are expected around October 22.
Sector Watch
The distillate trade is the dominant theme. U.S. refiners have shifted product yields to maximize diesel and jet fuel output because those crack spreads far exceed gasoline. Since March, the New York Harbor distillate crack has averaged 74 cents per gallon above the gasoline crack. Distillate inventories as of the week ending August 28 sat 14% below the five-year seasonal average. The EIA expects diesel crack spreads to remain elevated into the fall in its September 2026 outlook.
Catalyst Calendar
- October 22, 2026: Valero Q3 earnings. Margin per barrel and throughput guidance will be the read on whether September’s extreme crack levels translated into another blowout quarter or whether seasonal maintenance and some spread compression changed the math.
- Fall maintenance season: Distillate production typically falls as refineries cycle through turnarounds while harvest-season agricultural demand rises. Low starting inventories amplify the seasonal price effect.
- Strait of Hormuz: Any restoration of tanker flows would relieve Asian refiners and narrow global crack spreads. The EIA flags this as a primary variable in its forward outlook.
Risk Radar
The bull case is well understood, which is precisely the risk. Marathon has nearly doubled in 2026; Valero is up close to the same. Phillips 66, which closed the Los Angeles refinery contributing to the capacity shortage and is now running at 96% utilization on its remaining fleet, has risen 66%. At these levels, both MPC and VLO are pricing in a meaningful continuation of peak-cycle margins. If Hormuz traffic recovers faster than consensus expects, or if Asian refinery restarts accelerate, crack spreads could compress sharply with limited warning. Marathon’s own guidance acknowledges margins have moderated from Q2 peaks into Q3.
The Cheat Sheet
- Top Market Theme: Domestic refiners are earning record per-barrel margins because global capacity is broken and they are the only fleet capable of filling the gap.
- Stock to Watch: MPC. The sourcing insulation, buyback scale, and Q3 throughput guidance of 3,005 mbpd make it the cleanest way to hold the refining trade into earnings.
- Sector to Watch: Downstream energy. Distillate and jet fuel crack premiums are not seasonal anomalies; they reflect a multi-year underinvestment in global refining capacity that closures in Houston, Los Angeles, and Benicia have made structurally worse at home.
- Biggest Risk: A rapid reopening of Middle East product flows would be a simultaneous negative for every refiner in this trade.
- One Thing to Remember: The record crack spread is a margin window, not a permanent floor. Q3 earnings are the first real test of whether September’s diesel crack converted into cash, or whether maintenance and modest spread compression already began to close the gap.