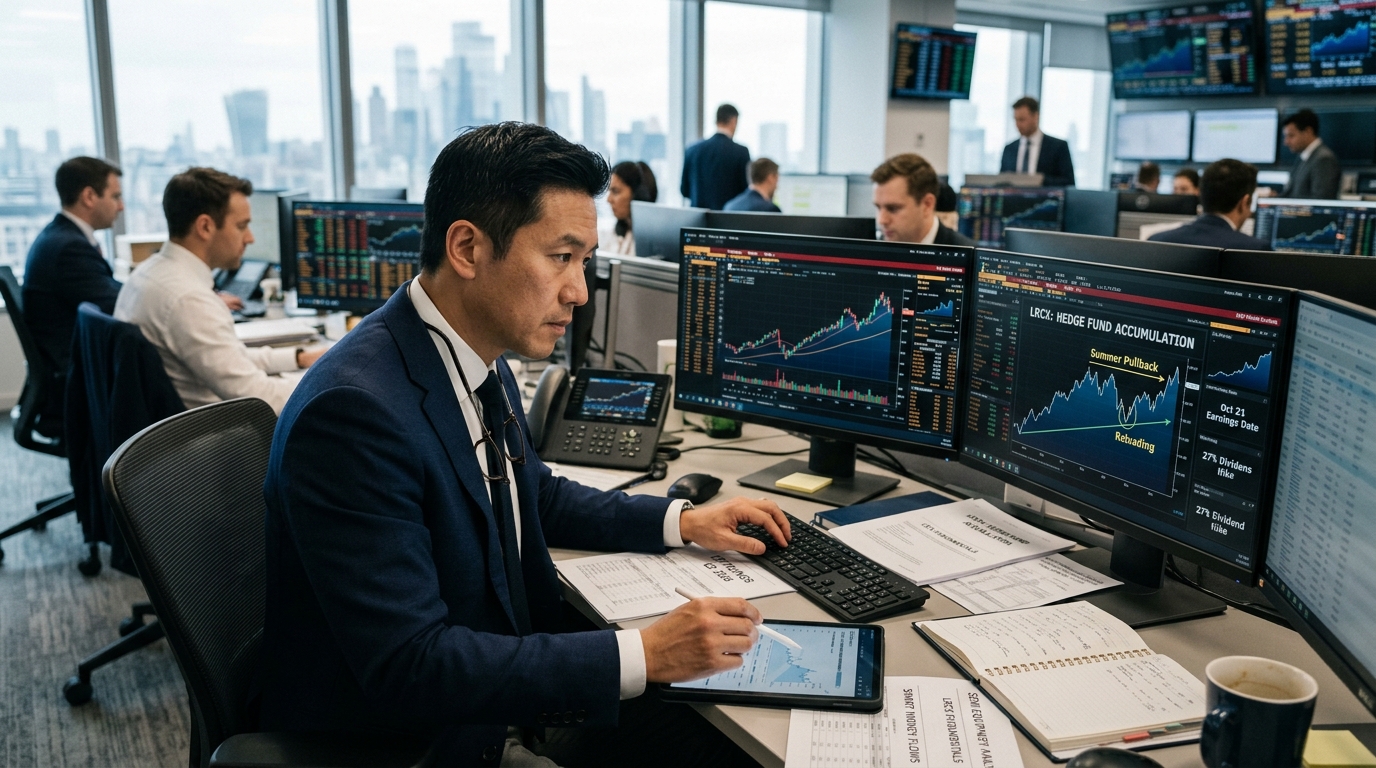
The Q2 2026 13F filing season is closed, and the data points to one theme that cuts across fund style: hedge funds are still buying semiconductor equipment, and one name keeps surfacing on buying lists that span growth desks, quant shops, and fundamental long/short managers alike.
The macro read first. After a stretch of macro uncertainty and crowding concerns, global hedge funds rebuilt exposure to technology stocks at one of the fastest clips of the year, with Reuters reporting in late May that a Goldman Sachs Prime Brokerage client note said funds bought technology shares at the fastest pace in nearly three months. The buying was not confined to software. The trade has broadened from a few mega-cap names into a hunt for companies that can monetize AI demand through chips, data centers, power infrastructure, and networking equipment.
Where the Consensus Is Building
From Q2 2026 13F filings, clustered buying appeared in enterprise software and aerospace, but semiconductor equipment names drew some of the most deliberate new money.
Whale Rock Capital Management’s flagship hedge fund gained 72.5% through the first half of 2026, putting the tech-focused firm among the year’s top performers, according to Bloomberg. Among Whale Rock’s top new positions for the period: Lam Research (LRCX). Across institutional filers, hundreds of investors increased Lam Research positions in the most recent quarter, while hundreds reduced positions.
The LRCX Case in Plain Terms
Lam Research is one of the largest providers of wafer fabrication equipment for semiconductors, with a strong portfolio positioned to capture AI-driven demand. The company historically skewed toward memory chipmakers but has gained meaningful share in logic chip equipment.
The stock ran hard and then gave back ground. The all-time high closing price was $432.87 on June 30, 2026. That kind of reset is exactly what brings value-conscious funds back in.
Lam posted non-GAAP earnings of $1.82 per share for the quarter ended June 28, 2026. The company also guided for September 2026 quarter revenue of $8.10 billion plus or minus $400 million and non-GAAP EPS of $2.15 plus or minus $0.15.
In late August, Lam boosted its quarterly dividend by 27%. That move matters beyond income: a company returning that much cash while guiding to higher revenue is signaling confidence in forward cash generation that few equipment peers can match.
What to Watch
Lam is scheduled to report earnings on October 21, 2026. The question heading into the report is whether demand commentary from memory and foundry customers justifies a move back toward June highs.
Funds that added LRCX in the pullback are effectively betting that the October report reopens that gap. Traders watching the name should mark the prior high zone as the level that confirms a fresh leg. Below $300, the thesis starts to require revision.