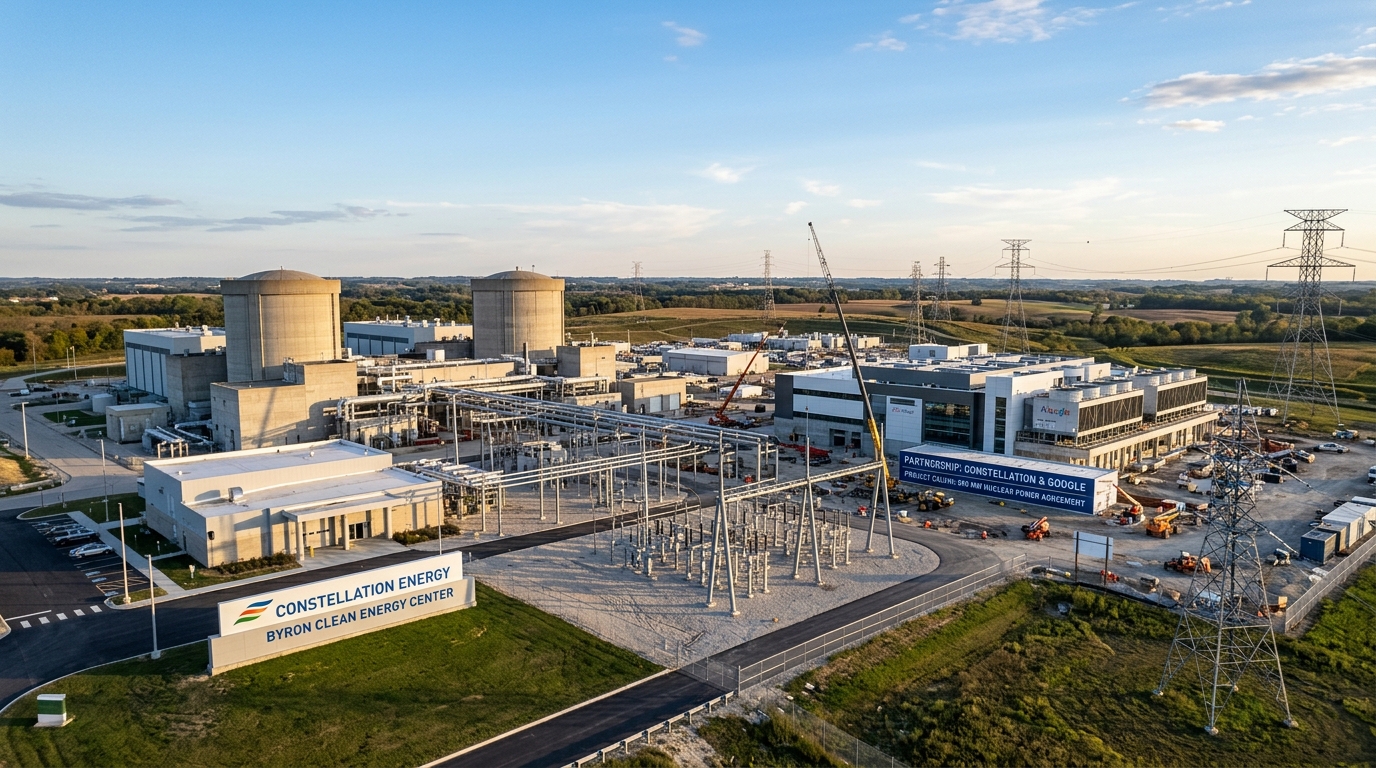
Two days ago, Constellation Energy was a utility company struggling under the weight of its own record high. The stock hit $412.70 on October 15, 2025 and has spent much of 2026 sliding away from it. Then Google signed a 20-year nuclear deal, the shares jumped about 12%, and the conversation changed. The question now is whether this is a trading bounce or the beginning of a genuine re-rating.
The Business
Constellation is the largest nuclear fleet operator in the United States, running 21 reactors across the country after absorbing Calpine in a transaction that closed on January 7, 2026. With the nation’s largest nuclear fleet at the core of its strategy, the company pairs the grid’s most reliable power with flexible resources to meet accelerating demand driven by electrification and the data economy. That combination of baseload generation and flexible natural gas assets is exactly what hyperscalers are hunting for.
Why Wall Street Is Paying Attention
The Google deal is not a rumor or a letter of intent. The 20-year power-purchase agreement supports more than $4.3 billion of Constellation investment to upgrade systems across 11 Constellation-owned nuclear units in Illinois, Pennsylvania and New Jersey. The first uprate is expected to be delivered by 2028, with capacity added in phases after that.
This is Google committing two decades of demand and tying it to billions of dollars of investment in existing reactors, not to promised future capacity, but to plants already running. The deal funds equipment and efficiency upgrades at Constellation-owned nuclear units in Illinois, Pennsylvania and New Jersey, so the added capacity comes from reactors already operating. The structure matters because it avoids new-build construction risk on Google’s portion.
Constellation already had long-term contracts with Microsoft and Meta. Those agreements with Microsoft and Meta demonstrate how the company is putting its expanded portfolio to work while maintaining reliability for customers. Google is now another major tech customer, and the deal is a large commitment by volume.
What’s Driving the Opportunity
Constellation reported Q2 2026 adjusted (non-GAAP) operating earnings of $2.55 per share and raised its full-year 2026 adjusted operating earnings guidance to a range of $11.50 to $12.50 per share.
The stock’s valuation can still look modest against that earnings trajectory and against the duration of contracts that are now landing. With long-dated PPAs increasingly tied to upgrades inside an existing fleet, the forward multiple can compress further with each new agreement. Analysts broadly cite data center-driven power demand as a key driver of incremental contracted value.
What Could Go Wrong
Execution risk is real. Reactor uprates are complex projects, and the first Google-linked capacity is not expected until 2028. Regulatory changes at the federal level could affect nuclear incentives that Constellation currently relies on. Key risks include potential plant restart delays, regulatory hurdles, and high valuation pressures.
The stock is also still down significantly from its peak. Even after the Google-related rally, shares remain down about the mid-teens year to date. That gap reflects genuine investor skepticism about whether contracted revenues fully justify the valuation, particularly in a rising-rate environment where utility-like income streams get discounted harder.
The Bottom Line
Constellation is one of the few companies with the fleet, the grid relationships, and the contract track record to close deals of this size repeatedly. Tech companies have been embracing nuclear as an alternative source of power for AI data centers, with power-grid constraints driving concern that infrastructure bottlenecks could crimp the AI buildout. Constellation sits directly in the path of that spending. With 20-year revenue visibility now attached to multiple hyperscalers, the case for owning this stock is stronger today than it was before the Google announcement.