October 29, 2026
Bonus Content: Chipotle Beat on Revenue. The Margin Slide Is the Real Problem.
Trump’s About to Unleash His $16 Trillion Midterm Weapon?
Dear Reader,
I just received an urgent FedEx package from one of my closest contacts… a former CIA insider who knows Trump personally.
I now believe Trump is about to deploy a $16 trillion chess move… just as folks head to the polls for the midterm elections.
This move could help him secure a big win on November 3.
To put the size of this move into perspective…
$16 trillion works out to roughly $46,650 for every man, woman and child in America.
Inside that FedEx package, Trump’s plan is laid out in black and white.
It could be the most important public document I’ve come across in my entire career…
In my new presentation, I open it LIVE on camera for everyone to see.
Click here to see the cold, hard proof.
Matt McCall
P.S. This move could result in a HUGE WIN for Trump, America, and savvy investors who can connect the dots. Click here for the details.
Chipotle Beat on Revenue. The Margin Slide Is the Real Problem.
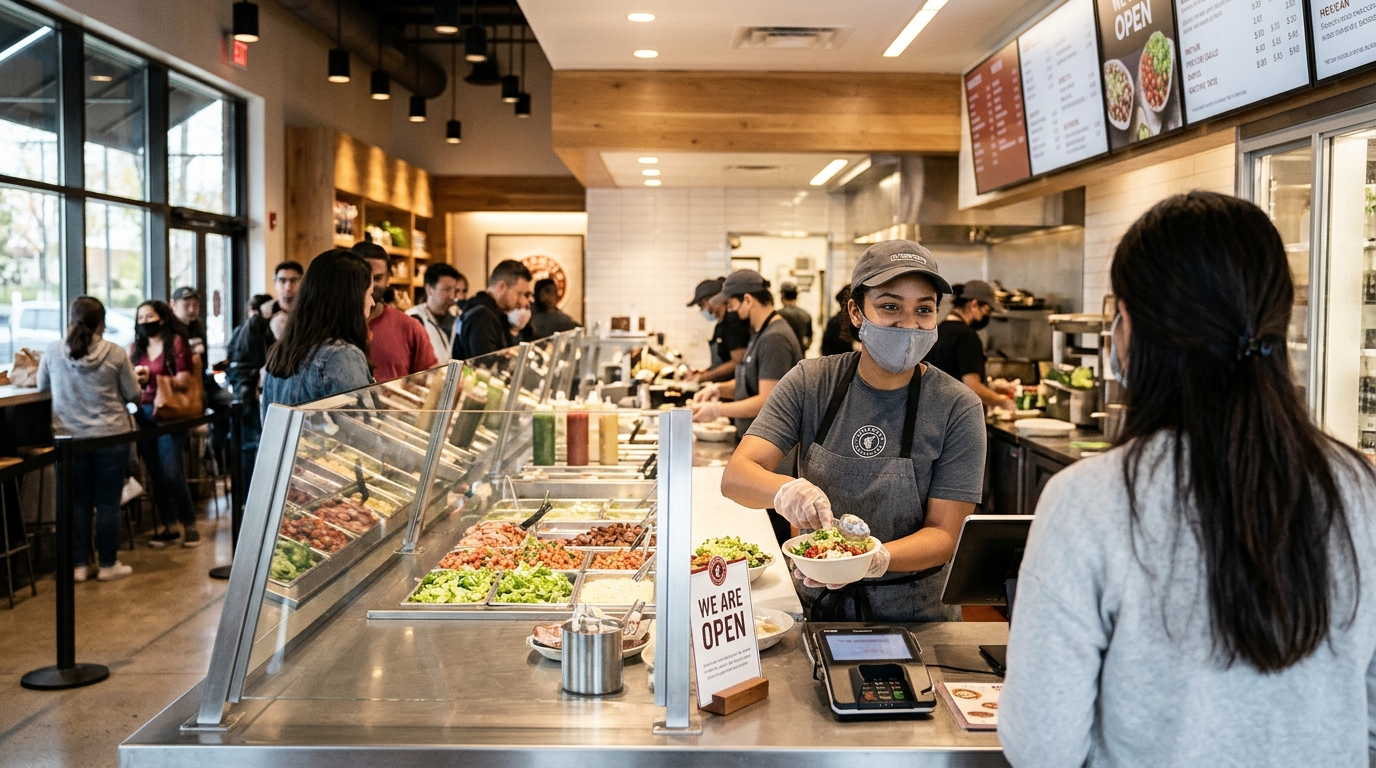
Chipotle reported mixed third-quarter results Tuesday: adjusted earnings of $0.27 per share, below what Wall Street expected, while revenue rose 9.6% to $3.3 billion and edged past forecasts. The stock rallied sharply after hours anyway, and that reaction tells you almost everything about where CMG stands right now.
Investors are not buying the earnings number. They are buying the idea that traffic is finally healing.
Transactions grew 0.8%, the third consecutive positive quarter. September comparable sales hit 3.8%. That is real progress after a bruising 2025. Digital sales were a record $1.3 billion, representing 38.8% of food and beverage revenue. Loyalty accounted for 33% of sales. The marketing investment is working.
But the cost of buying that traffic back is the number that should keep holders honest.
Operating margin fell to 13.7% from 15.9% a year ago. Restaurant-level margin dropped 120 basis points to 23.3%, with higher labor, freight, and marketing costs contributing to the decline. For full-year 2026, management continues to anticipate full-year comparable restaurant sales growth in the low single-digit range. That is not a recovery story. That is a company spending to hold its footing.
The analyst response after the results confirms the tension. Consensus sits at Moderate Buy with an average price target around the low $40s and roughly 27 buy ratings against about 9 to 11 holds, depending on the tracker. But the direction of individual targets is uniformly lower. Guggenheim cut its target to $32 from $36, reducing its 2026 EPS estimate to $1.09 from $1.13. Bernstein maintained Outperform but dropped its target from $50 to $43. Citigroup trimmed its target from $43 to $41. JPMorgan, BNP Paribas, and Wells Fargo all made cuts too.
Full-year 2026 EPS is widely estimated around $1.1 to $1.2. A company still struggling to push per-share earnings higher after two years of effort is a company that has not yet earned the re-rating it needs.
The near-term catalyst is the Smoked Brisket return. That limited-time item comes back November 5 and is expected to test the 3% to 4% comparable sales exit-rate target management has discussed. Sales have softened in early Q4 alongside the broader industry, and Chipotle is counting on a reacceleration in the back half of the quarter and into 2027.
The bull case rests on that reacceleration actually arriving. If November brisket traffic validates the 3% to 4% exit rate, the margin story shifts from liability to investment. If it does not, the stocks sitting near $28 to $31 with price targets clustering around $32 to $36 from the cautious camp will look more accurate than the bulls at $43 to $50. Watch the Q4 comp trajectory above everything else.